Jack Bogle Was Fired in 1974 After a Merger He Championed Went Sour. The Company He Started Next Put an Index Fund in Millions of Retirement Accounts
Getting fired over a botched merger deal sounds like a career ending, but for Jack Bogle in 1974, the terms of his ouster contained a loophole that would reshape how ordinary Americans build wealth for retirement.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
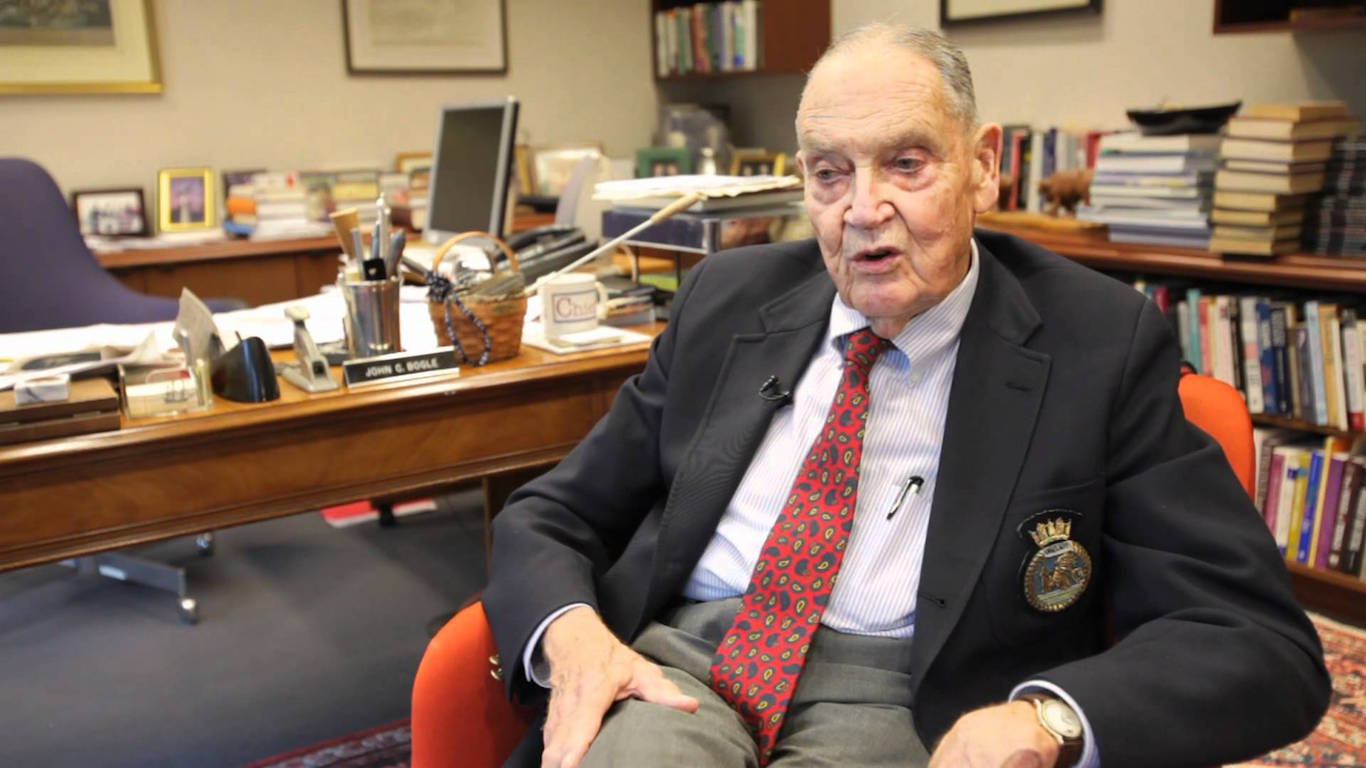
In 1974, the board of Wellington Management fired Jack Bogle. Bogle had joined the firm straight out of Princeton in 1951, and the reason for his firing was a deal he had pushed for himself: the 1966 merger with Thorndike, Doran, Paine & Lewis, a Boston investment firm. That merger gave the Boston firm’s owners a 40% share of the equity in the enlarged Wellington. When the partnership went bad, those partners helped push out the man who had brought them in.
Bogle never blamed anyone else. “The great thing about that mistake, which was shameful and inexcusable and a reflection of immaturity and confidence beyond what the facts justified, was that I learned a lot,” he said later.
The firing is worth a fresh look this year. The fund that came out of it turned 50 this summer, and the indexing idea it introduced now sits in millions of 401(k) and IRA accounts held by people at or near retirement.
How Getting Fired Gave Bogle the Blueprint for the Index Fund
Bogle founded Vanguard in 1974 with an unusual structure: the company is owned by the funds it oversees. Because there are no outside owners taking a cut, the savings from Vanguard’s size go back to fund shareholders.
The terms of the breakup also shaped what came next. Under the merger’s aftermath, Bogle was prohibited from managing money directly on behalf of clients. A fund that simply tracked a Standard & Poor’s index needed no stock picker, so Bogle could launch one without breaking that rule. Nobel laureate Paul Samuelson gave him the intellectual backing. In his autumn 1974 essay “Challenge to Judgment,” Samuelson called for someone to build a portfolio that tracks the S&P 500.
Wall Street Mocked It as Bogle’s Folly
First Index Investment Trust finished its public offering on August 31, 1976, only 16 months after Vanguard opened for business. The four biggest retail brokers on Wall Street underwrote the deal, aiming to raise $150 million. They brought in $11.3 million, a 93% shortfall. The underwriters suggested calling it off because the money wasn’t enough to buy all 500 stocks in the index. Bogle refused: “Don’t you realize that we now have the world’s first index fund?”
Critics called it “Bogle’s Folly.” His case rested on simple arithmetic. As a group, actively managed funds earn the market’s return minus advisory fees, sales loads, trading costs and taxes. A fund with tiny costs would therefore give its investors close to their fair share of what the market returned.
Where Bogle’s Folly Shows Up in Your 401(k) Today
The Vanguard Total Stock Market ETF (NYSEARCA:VTI), which tracks the whole investable U.S. stock market, rose 243.79% in price over the past decade. That figure leaves out dividends. Over five years, its price rose 56.84%.
Who owns those gains matters more. Federal Reserve data for the second quarter of 2026 show that the top 1% of households hold 50.9% of stocks and mutual fund shares held outside workplace retirement plans. The bottom half of households holds 0.6%. Workplace plans such as 401(k)s look different: households between the 50th and 90th percentiles of wealth own 39.7% of those balances. For the middle class, the retirement plan is how they own the stock market.
That is why Bogle’s lesson about costs matters most to savers near retirement. Their balances are at their largest, so every dollar of fees costs more, and they have the least time to make up for it. One thing to watch is the Fed’s next quarterly update. The middle group’s share of retirement-plan wealth rose 0.4 points over the past year, and the update should reveal if that pace holds as markets swing. Another is your plan’s annual fee disclosure, which lists the expense ratio for every fund on the menu. That page shows whether Bogle’s 1976 arithmetic is working for you or against you.
Contact [email protected] for any questions or corrections.
Jake has been been working in financial media for almost 15 years. He focuses on all things personal finance for 24/7 Wall St. with high hopes to educate and entertain. Most recently, Jake spent 12 years working various roles at The Motley Fool. He started copy editing fool.com content, worked on premium and marketing campaigns, and helped launch The Ascent, a personal finance brand.
His work has been featured on platforms like MSN, Yahoo Finance, USA Today, and more. He's written about credit cards, social security, ETFs, savings accounts, and just about anything else you can imagine when thinking about money. Jake love to cook, play golf, and tell people he's never had a cavity. (It's true!)