Jack Bogle Said ‘Just Buy the Haystack.’ $200 a Month Starting at 30 Could Mean $668,000 by 65
Jack Bogle built a fortune-growing philosophy on one ruthless statistical truth about stock markets, and most investors are unknowingly working against it every time they pick a stock. The cost of getting this wrong compounds just as quietly as the…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

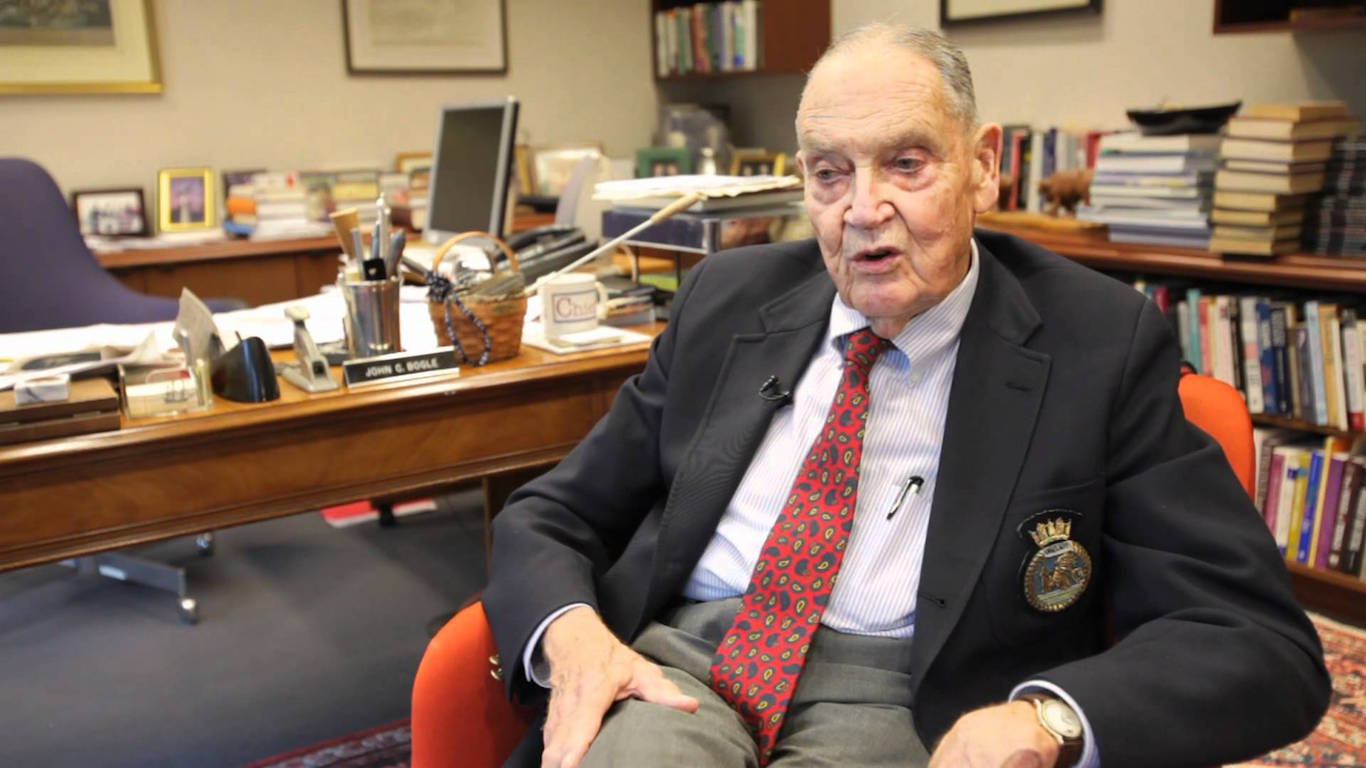
“Don’t look for the needle in the haystack. Just buy the haystack,” said Jack Bogle, who founded Vanguard in 1975 and launched the first retail index mutual fund. That line sums up his career: a precise statistical argument. Get it wrong and you could give up hundreds of thousands of dollars over a working life.
Bogle was right. The needle is the one stock that runs a decade. The haystack is the entire market. Own the haystack and you never have to find the needle.
Why Missing the Needle Costs So Much
Stock market returns are uneven. Over long periods, a small group of companies produces most of the market’s gains, while most other stocks add very little as a group and many lose money.
That skew makes stock picking dangerous. A portfolio of 10 or 20 hand-picked names will probably miss most big winners, and missing them means you trail the market badly, even if most picks are decent businesses.
An index fund owns every needle because it owns everything, and you give up beating the market by a mile. In return, you hold the winners that drive long-run returns.
How $200 a Month Grows Into $668,000
Take, for example, a saver who starts at 30 and invests $200 a month into an index fund for 35 years, culminating at age 65. When assuming for a constant 9.5% annual return, the ending balance is about $668,000. Total money put in: $84,000. The other $584,000 is growth from compounding: earning returns on earlier returns.
Most growth comes late. By the final decade, the balance is large enough that one good year adds more than several years of deposits. Early dollars count most because they have the most time to compound. No real market returns 9.5% every year. Stocks drop sharply in some years and jump in others. Treat $668,000 as a straight-line example of how compounding works.
Starting Late Costs More Than You Think
When you start matters more than anything else in this equation. Keep the same $200 a month and the same 9.5% return, but begin at 40 instead of 30. After 25 years, the balance is about $244,000 on $60,000 contributed.
Waiting a decade costs about $424,000 in ending value. The missed deposits were small. The real damage is losing the last and biggest decade of compounding. Behavior is the second variable. The math only holds if you keep buying through crashes. Selling in a panic locks in losses and misses the rebound.
Total Market or S&P 500: Two Different Haystacks
The Vanguard Total Stock Market ETF (NYSEARCA:VTI) tracks the entire investable U.S. equity market. It includes small and midsize companies. Its share price is up about 243% over the past 10 years, not counting dividends.
The Vanguard S&P 500 ETF (NYSEARCA:VOO) holds only the large-cap companies in the S&P 500. It comes directly from Bogle’s original index fund. Its fact sheet lists an expense ratio of 0.03%, so fees barely touch the compounding math.
Large companies make up most of the total market’s value, so the two funds usually move closely together. VTI suits investors who want every needle, including small companies that could grow into tomorrow’s giants. VOO suits investors who would rather focus on established large caps.
Set Up Your Haystack Before Another Year Slips Away
- Open the right account: A Roth IRA, traditional IRA, or regular brokerage account all work. Bogle’s approach calls for one broad, low-cost index fund tracking either the total U.S. market or the S&P 500.
- Automate the deposit: Schedule $200, or what you can afford, to move on payday. Automatic buying spreads purchases across good and bad markets and removes the urge to time them.
- Run your own numbers: Do the math yourself. Plug your age, monthly amount, and a conservative return into the free compound interest calculator at Investor.gov. Run it again with a 10-year delay to see the cost of waiting.
- Limit how often you look: Turn off daily price alerts and check the account once a year. Raise your contribution with every raise.
Savers who buy the whole haystack early win. Keep adding to it and hold it and modest monthly deposits can grow into a six-figure retirement.
Contact [email protected] for any questions or corrections.
Joel South covers large-cap stocks, dividend investing, and major market trends, with a focus on earnings analysis, valuation, and turning complex data into actionable insights for investors.
He brings more than 15 years of experience as an investor and financial journalist, including 12 years at The Motley Fool, where he served as an investment analyst, Bureau Chief, and later led the Fool.com investing news desk. He has also co-hosted an investing podcast and appeared across TV and radio discussing market trends.