This One Customer Is Now 44% of Super Micro’s Revenue
Super Micro just disclosed that a single unnamed customer now controls a staggering slice of its quarterly sales, and the identity of that buyer could reshape how investors see every AI infrastructure stock in the sector.

When Super Micro Computer (NASDAQ:SMCI | SMCI Price Prediction) reported fiscal first-quarter 2027 results on November 3, 2026, the key figure was the share of revenue. CFO Mark Long said one large data center customer represented 44% of quarterly revenue, compared with 28% for fiscal 2026 as a whole.
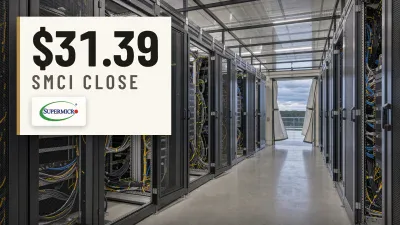
Super Micro did not name the customer, and no analyst on the call named one. The stock closed at $31.39, up 3.12% in the regular session, and reached $33.65 at 7:59 p.m. ET, a 7.20% after-hours gain. That bounce followed a 28.15% drop over one month and a 38.15% decline over one year. Revenue rose 298%, and the full-year outlook improved, but one buyer now heavily influences sales, receivables, and margins.

How Big This One Customer Has Become
At 44% of $19,945.8 million in net sales, this customer’s implied revenue is about $8.8 billion for the quarter. Two customers also held 49% and 17% of accounts receivable (bills not yet paid) at quarter end.
Long linked that to project size. “A single deployment today can exceed our total quarterly revenue from just one year ago.” He expects concentration “to stay elevated while these build outs run,” though his comparison did not say the same customer led in both periods.
Why SpaceX and xAI Top the Suspect List
SpaceX acquired xAI in an all-stock deal in February. On June 12, 2026, Chief Executive Charles Liang posted on X that he was “proud to co-build another new Gigawatt AI datacenter for @SpaceX and @XAI within a year.”
SpaceX’s CFO put its compute capacity at 1.7 gigawatts. By the end of the third quarter, 2.2 gigawatts; by the end of October, and possibly 3 gigawatts by the end of the fourth quarter. The link remains unconfirmed; Liang’s posts carry no dollar figures, and Super Micro shares that work with Dell Technologies (NYSE:DELL). The power and cooling behind those gigawatt-scale projects is the quieter side of the AI trade, and we featured seven suppliers riding it in a free report here.
A Beat Built on Thinner-Margin AI Work
Revenue exceeded the $14.5 billion-$15.5 billion guide, the October 20 preliminary range of $18.5 billion-$19.5 billion and the $16.39 billion consensus. Adjusted EPS of $1.81 exceeded the $1.23 estimate, and net income reached $1,594.2 million against $168.3 million a year earlier.
About $2.3 billion came from deployments originally scheduled for earlier periods, so underlying revenue was about $17.6 billion. AI solutions rose to about 71% of revenue from 59%, and those large deployments carry lower margins. Non-GAAP gross margin was 12.8%, and Super Micro guided to 12%-12.5% for the December quarter and 11.8%-12.2% for fiscal 2027.

Prepayments Ease the Cash Strain
Free cash flow was negative $481 million after $434 million used in operations and $47 million of capital spending, compared with negative $7 billion for fiscal 2026. Deferred revenue rose about $3.1 billion, mostly from customer prepayments.
Debt still exceeds cash. With $8.6 billion of bank debt and convertible notes against $6.9 billion in cash, Long said, “At this point, we don’t have any plans to consider equity raises.”
What Super Micro’s Raised Outlook Signals for Investors
Super Micro raised its fiscal 2027 revenue outlook to $72 billion-$82 billion from $65 billion-$72 billion and guided the December quarter to $19.5 billion-$21.5 billion.
The concentration risk looks more manageable than the recent selloff implies. Large customers prepay and pay quickly. That lowers the credit risk that normally comes with concentration, and at about 9 times trailing earnings, the shares sit well below their $44.94 close on October 7.

The outlook weakens if the December-quarter report shows revenue below $19.5 billion or gross margin under 12%, because that would mean the big buyer is setting terms. If receivables concentration rises above 49% in the next 10-Q, that would also count against the stock.
Contact [email protected] for any questions or corrections.
Omor Ibne Ehsan is a writer at 24/7 Wall St. He is a self-taught investor with a focus on growth, cyclical, and dividend equities that have strong fundamentals, value, and long-term potential. He also has an interest in high-risk, high-reward investments such as penny stocks.