UPS Has Paid the Same $1.64 Dividend for 7 Quarters. Should Retirees Worry?
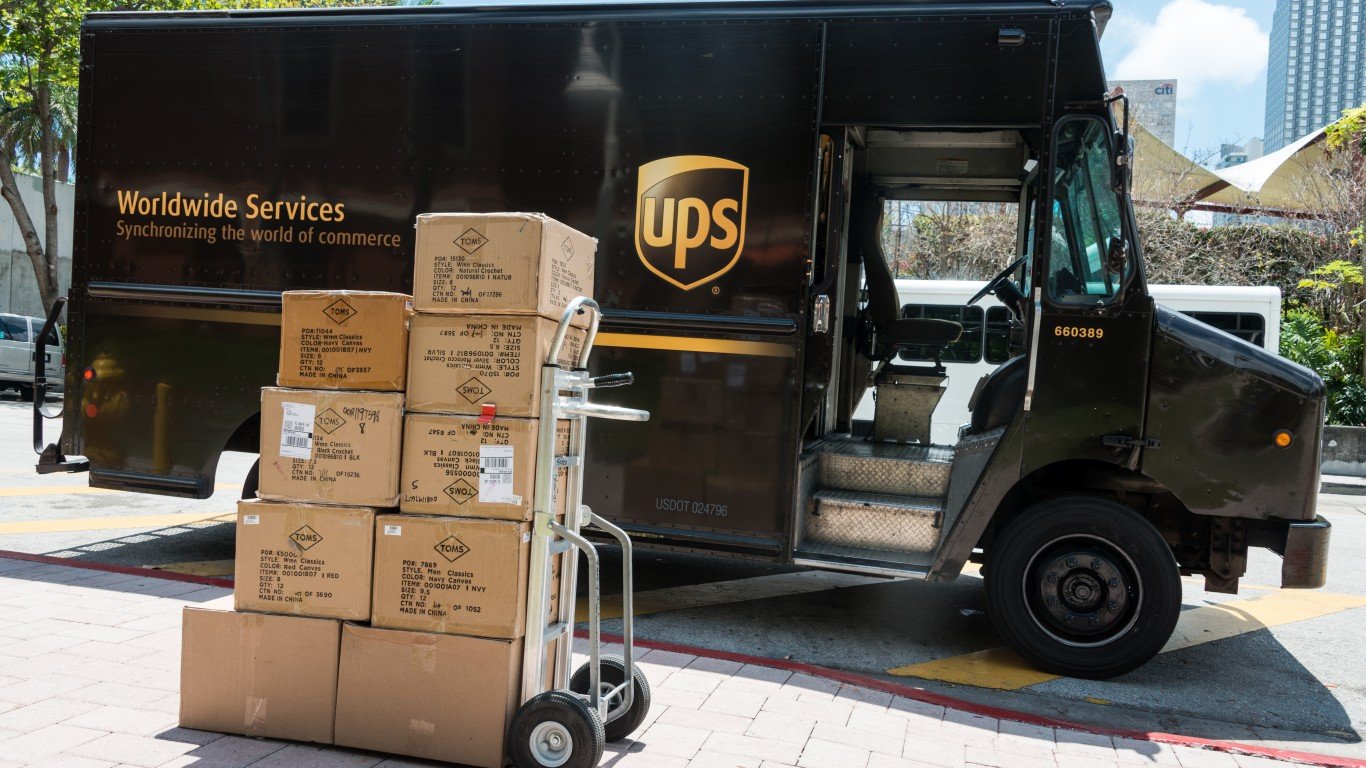
UPS has held its dividend flat for seven straight quarters while paying out nearly 90 cents of every free cash flow dollar, a combination that puts retirees on edge and raises a question management has not fully answered.

United Parcel Service (NYSE:UPS | UPS Price Prediction) has paid $1.64 per share every quarter since the February 18, 2025 ex-dividend date. That raise was a single penny, up from $1.63. It has stayed flat for seven straight quarters since then. Over the past quarter century, UPS raised its quarterly dividend from $0.17 in 2000, so a freeze this long is the first thing income investors should study.
A Frozen $1.64 Shows How Thin the Cushion Is
UPS expects to pay around $5.4 billion in dividends in 2026, against adjusted free cash flow guidance of approximately $6.1 billion. That means dividends take up roughly 89% of cash flow. The annualized $6.56 payout also equals about 90% of the approximately $7.28 in adjusted EPS that management is guiding to. At $109.14, the stock yields about 6%. A payout that high leaves little room for raises while the company pays for its restructuring (a 6% yield coupled with a 90% payout is exactly the setup we flag in our free dividend trap guide, which walks through the seven warning signs that a big yield is about to be cut).
Revenue Per Piece Is the Engine Behind Any Future Raise
Dividend growth depends on one operating number: U.S. Domestic revenue per piece. In the third quarter, it rose 6.1%, even as U.S. average daily volume fell 3.3% because UPS is, by choice, cutting its volume from Amazon (NASDAQ:AMZN). Revenue per piece grew 60 basis points faster than cost per piece, and the segment’s adjusted margin expanded to 7.0% from 6.4%. The trend goes back four quarters, with gains of 8.3% in Q4 2025, 6.5% in Q1 2026, and 9.3% in Q2. Fuel matters here too: management said about half of the Q3 gain came from base rates and customer mix, and higher fuel rates supplied the rest.

Cash and Debt Signals Point to 2027
UPS ended the third quarter with $6.8 billion in cash and no outstanding commercial paper. It issued $1.3 billion in debt to refinance a maturity. This year’s free cash flow also covers a $1.4 billion cash cost for the Driver Choice Program, the buyout offered to drivers, and that cost does not repeat. Chief Financial Officer Brian Dykes said 2027 free cash flow should “continue to move up and improve our dividend coverage.” Management added, “Clearly our dividend is safe and secure.” Management gave no timeline for a raise.
What Would Restart Growth or Force a Cut
Signs that could lead to a raise:
- Revenue per piece keeps beating cost per piece within management’s expected spread of 50 to 100 basis points
- U.S. Domestic margins keep climbing toward the approximately 10.5% guided for Q4
- Free cash flow rises once the Driver Choice cost goes away
Pressure would build if that spread turns negative, if pension funding uses more cash, or if tariffs and trade tensions hurt international volume for a long stretch. A cut would likely take free cash flow falling below dividend payments for several years in a row, and the current guidance does not show that.
Verdict for Retirees
The $1.64 dividend looks safe, backed by rising revenue per piece, a solid cash balance, and management’s clear support for the payout. The payout points to a steady check until 2027 cash flow shows up. In the meantime, U.S. Domestic revenue per piece is the most useful early signal of when the next raise could come.
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.