IREN is Only Fit for a Specific Investor Currently
IREN has Microsoft and NVIDIA as customers, billions in financing, and a stock that has lost nearly half its value in a month. Its AI pivot now faces a delivery test, and the next two earnings reports could settle which…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
IREN (NASDAQ:IREN) trades at $21.71. Its profile combines high volatility with a multi-year return horizon. The stock has fallen 46.37% in a month, so investors need to decide whether a costly AI shift is breaking down or simply running behind schedule.
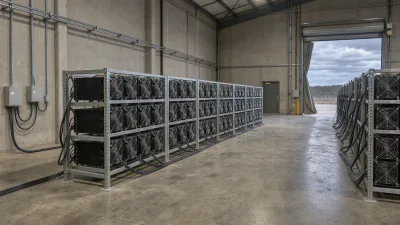
IREN builds renewable-powered data centers and is moving out of Bitcoin (CRYPTO:BTC) mining and into AI cloud services. Its customers include Microsoft (NASDAQ:MSFT | MSFT Price Prediction) and NVIDIA (NASDAQ:NVDA). Fiscal 2026 revenue rose 41.1% to $707M, and AI cloud revenue grew about 8x to $128.8M. The fourth quarter was tougher. Revenue of $137.2M missed estimates and fell 26.8% year over year. A $450.4M impairment on retired mining hardware helped produce a $684M net loss.
A $4 Billion ARR Target Backed by Microsoft and NVIDIA
Management says 2026 capacity is largely sold out. It is targeting $4B of contracted ARR in operation by year-end, up from $1B at the last update. Pricing is rising too. Pricing in current talks is near $25M per MW, above recent contracts at $20M. NVIDIA has signed a $3.4B five-year contract and committed to invest up to $2.1B.
The expansion is funded. IREN holds $5.90B in cash and has $14B in committed GPU financing and prepayments. Analysts expect fiscal 2027 revenue to average $2.81B, yet the stock trades at just 2.1 times book value. IREN is one of the non-chipmaker suppliers doing the actual AI expansion, the group we profiled in a free report on seven stocks powering the AI boom. The CEO put it simply: “IREN was built for this moment.”
Losses Widen as Capital Needs Keep Climbing
IREN lost $702.6M in fiscal 2026. It spent $4.33B on capex against operating cash flow of $2.10B and raised $9.68B through financing. Debt-to-equity now stands at 1.87. Revenue missed consensus in every quarter of fiscal 2026, and adjusted EBITDA fell to $19.2M from $59.5M the quarter before.
Estimates are falling fast. The average fiscal 2027 EPS forecast is now -$3.4211, compared with -$0.94 sixty days ago. Heavy reliance on a few customers and the risk of GPUs becoming obsolete add to the pressure.
Delivery Proof Arrives Within Two Quarters
The contracts and the cash pile support the bull case. Growing losses and falling estimates make the downside risk clear. The next earnings report will be measured against average revenue forecasts of $221.7M. After that, the test is whether the $4B ARR target lands on time and whether 2027 customer contracts support the 0.8GW delivery goal.
Wall Street Targets Tower Over a Stock at Fresh Lows
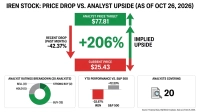
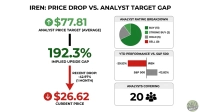
The $75.42 consensus target implies 247.4% upside, based on 20 analysts. Targets often lag selloffs this sharp, so they should be considered alongside other indicators, and none of them is a guarantee. The ratings break down as follows:
- Strong Buy: 2
- Buy: 13
- Hold: 5
- Sell: 0
IREN is down 42.52% year to date, while the S&P 500 is up 12.45%. Over one year the gap is wider: IREN is down 67.42% and the index is up 13.56%. Shares trade at 12.6 times sales and well below the $44.21 200-day moving average.
Delivery Milestones Will Decide What Comes Next for IREN
At $21.71, IREN’s outlook depends on execution.
Demand and funding are in place, so the stock now trades on proof of delivery. One or two more earnings reports will show whether estimate cuts continue.
A stronger case needs ARR close to $4B by year-end, adjusted EBITDA margins recovering from 14%, and new 2027 contracts priced near $25M per MW. A worse case would follow Horizon delivery delays, another revenue miss, or equity raises at these lower prices.
With a beta of 4.335, IREN has posted weekly drops as steep as the recent 24.72%. The contracts point to upside and the losses point to risk, leaving delivery as the key variable at $21.71.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.