Marvell’s $115 Billion Deal Has Lost More Than a Third of Its Value
Analysts see Marvell doubling, yet the market is pricing something very different. A fixed exchange ratio with no safety net has turned a premium into a discount, and Lumentum investors are the first to show they doubt the deal.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Marvell Technology (NASDAQ:MRVL | MRVL Price Prediction) closed at $159.80, and the average analyst price target is $321.87. That gap implies about 101% upside.

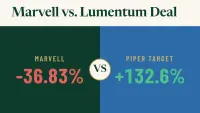
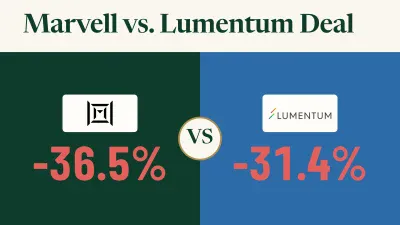
A gap that wide usually means analysts have not caught up with events. Marvell agreed to buy Lumentum (NASDAQ:LITE) in an all-stock deal with an implied enterprise value of $115 billion. Marvell shares have fallen 36.5% from the last unaffected close.
The terms remain as originally set. Each Lumentum share still converts into 4.500 Marvell shares. But that stock’s market value has dropped by more than a third.
For Marvell holders, a company growing data center revenue 46% a year looks cheaper at a lower price. But a stock tied to a merger the market dislikes can stay cheap until the deal closes in 2028.
A Fixed Ratio With No Collar Passes Every Loss Through
The headline value of about $1,132 per Lumentum share, a 23.9% premium, was set using unaffected prices. The ratio adjusts only for changes in share count or type, and it comes with no collar or price protection.
At Marvell’s latest close, 4.500 shares are worth $719.10. That is 21.3% below the $913.95 Lumentum traded at before talks were reported, so the premium has turned into a discount.
At that price, the equity portion is worth about $65 billion. Roughly $12 billion of debt does not fall with the stock. So enterprise value stands near $75 billion to $77 billion, down about 33% to 35%.
Marvell holders would keep about 67% of the combined company and hand 33% to Lumentum holders. That split stays the same no matter how far Marvell falls.
Lumentum Trades Below Even the Smaller Offer
Lumentum closed at $626.75. It fell 7.85% on the day and is down 31.4% from its unaffected close, leaving it 12.8% below the $719.10 offer.
A spread that wide signals doubt about the deal closing on these terms, about Marvell’s stock, or both. Both sets of stockholders must vote, and antitrust and foreign-investment reviews must clear, with closing expected in the first half of calendar 2028.
Walking away is costly. In certain cases, Lumentum would owe $2.9 billion and Marvell a matching $5.8 billion. Marvell would also owe $3.2 billion if regulators block the deal or it misses its outside date.
Marvell Fell Harder Than the Chip Selloff Explains
Much of the slide came before the announcement. At Marvell’s last close before the deal, $196.40, the 4.500 shares were already worth only $883.80. That was just 5.1% above Lumentum’s $840.70. Marvell has since dropped another 18.6%, including 7.08% in the latest session.
A broad chip selloff explains part of this. Over the same week, however, the VanEck Semiconductor ETF (NASDAQ:SMH) fell only 11.2%, and Coherent (NYSE:COHR) fell 18.6%.
Marvell lost about $81 billion of market value, compared with about $26 billion for Lumentum. With $3.9 billion of cash against $5.0 billion of debt, stock was the only practical way for Marvell to pay.
Analyst Targets Still Describe the Pre-Deal Marvell
Analyst conviction has not shifted. With 9 Strong Buy and 34 Buy ratings, only 4 of 47 analysts sit at Hold and none at Sell. That support looks dated, since the $321.87 average stands near the $329.73 52-week high, so many targets were likely set before the deal.

The business behind those targets is strong. Fiscal second-quarter revenue rose 36.5% to $2.739 billion, and management guided third-quarter revenue to $3.150 billion.
Marvell Technology and Lumentum Holdings project more than $1 billion in annual cost savings. NVIDIA (NASDAQ:NVDA) also invested $2 billion in each company this year.
Marvell is still up 88.36% year to date, compared with 12.45% for the S&P 500. Lumentum’s $1,110.07 average target implies about 77% upside, although its price now moves with Marvell’s.
What Would Change the Marvell Math Before 2028
The stock case looks weaker than the business case. The business is performing well. But the stock now has a long merger uncertainty and gives a third of the company to new holders. Analyst targets haven’t caught up with either.
A narrowing of Lumentum’s spread toward the offer value would show the market accepting the deal. At $626.75, Lumentum effectively prices Marvell exposure at about $139.28 per Marvell share if the deal closes.
If the deal falls apart, Lumentum keeps a business whose revenue grew 136.5% last quarter, and in certain cases it would collect a breakup fee that Marvell holders would fund.
Contact [email protected] for any questions or corrections.
Omor Ibne Ehsan is a writer at 24/7 Wall St. He is a self-taught investor with a focus on growth, cyclical, and dividend equities that have strong fundamentals, value, and long-term potential. He also has an interest in high-risk, high-reward investments such as penny stocks.