Marvell Slipped Over The Last Month and Then Crashed Massively on the Lumentum Announcement: This Wall Street Desk Doubled Down on Its 130% Gains Prediction
Marvell cratered nearly 37% in a month while every AI chip rival held up far better, yet one Wall Street desk just reaffirmed a price target that implies triple-digit gains from here. The question is whether that optimism survives contact…

Marvell Technology (NASDAQ:MRVL | MRVL Price Prediction) currently trades at $171.97, while Wall Street’s average price target sits at $333.09. That gap means about 93.7% upside.
Marvell sells custom AI chips, optical DSPs and Ethernet switches to hyperscalers. Data Center sales made up 79% of revenue last quarter. One deal announcement has now opened the widest price-to-target gap in its peer group.
A Month-Long Slide Capped by an All-Stock Lumentum Shock
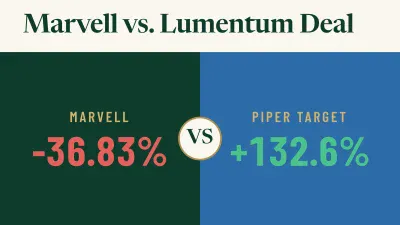
Marvell’s agreement to buy Lumentum (NASDAQ:LITE) in an all-stock transaction did the damage. Shares fell 29.4% over the past week and 36.83% over the past month. The selloff is steep, well past 30%. The stock had already slipped from $272.23 to $243.57 before deal week began.
Investors didn’t like paying in stock. Lumentum holders get Marvell shares at a fixed exchange ratio, which dilutes current owners. Marvell is also still integrating Celestial AI and XConn Technologies, and it has $4.963 billion in long-term debt. A CNBC headline warned the stock could plunge on the acquisition. Management forecast cost synergies and first-year non-GAAP EPS accretion, but that did little to steady the stock.
Weakness across the sector played a part. Large AI chip peers fell between 6.48% and 23.66% over the same month, and the S&P 500 slipped 1.99%. Marvell’s drop was still the steepest.
Piper Sandler Holds Its $400 Target as Other Desks Retreat
Of 47 analysts, 9 rate Marvell Strong Buy, 34 rate it Buy and 4 rate it Hold. None rate it Sell. Recent revisions have moved lower, as several firms cut targets after the deal news.
Piper Sandler went the other way. David O’Connor’s desk kept its Overweight rating and $400.00 target, which means about 132.6% upside. The firm called the selloff an overreaction. It said that long-term demand for optical interconnects and laser infrastructure validates the combination.
In support of that view, second-quarter fiscal 2027 revenue reached $2.739 billion, up 36.5%. Non-GAAP EPS of $0.94 exceeded the $0.9289 estimate. Management guided third-quarter revenue to $3.15 billion plus or minus 5% and raised its fiscal 2028 outlook to about $18 billion. On the earnings call, CEO Matt Murphy said “the magnitude of our scale-up optics opportunity next year is much larger than we thought just a quarter ago.”
Keep an eye on three things. The next earnings report should show the custom silicon ramp. Non-GAAP operating margin is expected to reach the 38% to 40% target range in the fiscal fourth quarter. Custom revenue should more than double in fiscal 2028, and the expanded Google partnership pays off most in fiscal 2029 and beyond. One catch: most targets were set before the deal, so the average could drift lower.
Every AI Chip Peer Slipped, but Marvell Fell Hardest
The whole group sold off together. Marvell just fell much further than its closest rivals.
The most direct custom silicon rival, Broadcom (NASDAQ:AVGO), fell 6.48% over the month. At $332.13 against a $530.14 target, it has about 59.6% implied upside. Ratings stand at 8 Strong Buy, 41 Buy and 2 Hold. That upside trails Marvell’s.
NVIDIA (NASDAQ:NVDA) slipped 11.65%. At $206.69 against a $328.95 target, it has about 59.2% implied upside. Analyst recommendations include 10 Strong Buy ratings, 49 Buy ratings, 2 Hold ratings and 1 Sell ratings.
Advanced Micro Devices (NASDAQ:AMD) dropped 23.66%, the closest to Marvell’s fall. At $483.90 against a $646.74 target, its implied upside of about 33.7% is the lowest of the group. Ratings stand at 5 Strong Buy, 39 Buy and 11 Hold.
Marvell has the largest analyst-implied upside in the group by a wide margin. Targets are estimates, and that gap mostly shows how far the price fell.
Triple-Digit Gains Survive a Steep Monthly Drop for Marvell
At $171.97, Marvell has about 93.7% implied upside to the $333.09 consensus from 47 analysts:
- Strong Buy: 9
- Buy: 34
- Hold: 4
- Sell: 0
Even after the selloff, the stock is up 102.7% year to date, while the S&P 500 is up 10.62%. Over the past month, Marvell fell 36.83% and the index fell 1.99%. Shares trade at about 26 times forward earnings with a beta of 2.327, which points to big swings in either direction.
Why the Lumentum Discount Looks Too Steep to Me
The case for Marvell strengthens if the next earnings report confirms the custom ramp and management shows that Lumentum’s synergies can arrive without stalling margin expansion. But the case weakens if more hyperscalers design their own silicon, if China trade restrictions tighten, or if dilution pushes analysts to cut targets toward the current price.
Bulls need three things: execution on guidance, a clean close and optical demand that makes Lumentum a growth engine. Bears point to concentration. A few hyperscalers drive most of the revenue, and a large stock deal adds integration risk on top of two acquisitions still in progress.
I lean bullish. The price assumes integration goes badly, while the core business keeps speeding up. With that much volatility, the stock may stay choppy while the deal closes. For readers trying to spot the next monster run in AI silicon early, we listed the traits past winners shared before their runs in a free playbook here.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.