If You Invest $1,000 in Marvell Today, Here’s What It Could Be Worth by 2030
Marvell shares just dropped 11% on acquisition rumors even as the stock sits on a 162% year-to-date gain, and where it lands by 2030 depends entirely on which version of its AI ambitions plays out.

Marvell Technology (NASDAQ:MRVL | MRVL Price Prediction) shares traded at $222.97 at midday, a decline of 11.4% on the session. The drop followed reports that the chipmaker is close to a megadeal for Lumentum (NASDAQ:LITE) as part of an AI push.
Even after the selloff, the stock is up 162.82% year to date. For a $1,000 investment held until 2030, the key question is whether Marvell’s AI data center business can keep compounding at this pace.

Base Case Turns $1,000 Into About $1,549 by Late 2030
The price-prediction model covers 1-year and 5-year horizons. The 5-year run ends October 27, 2031, so the 2030 figures below are illustrative milestones along that projected path. On the base-case path, a $1,000 investment might grow to about $1,549.31 by October 2030, a total return of 54.93%. That rests on a projected per-share value of $376.39 at that point.
At the full 5-year endpoint, the primary target is $401.59. It works out to a total return of 65.3%, which turns $1,000 into $1,653, or 10.58% a year. Over the nearer term, the 1-year base target is $284.80, and projected confidence is rated high (0.9).
All scenario returns start from the model’s reference price of $242.94, set on October 27. Shares now trade below that level, so a buyer at today’s price would start from a lower cost basis.
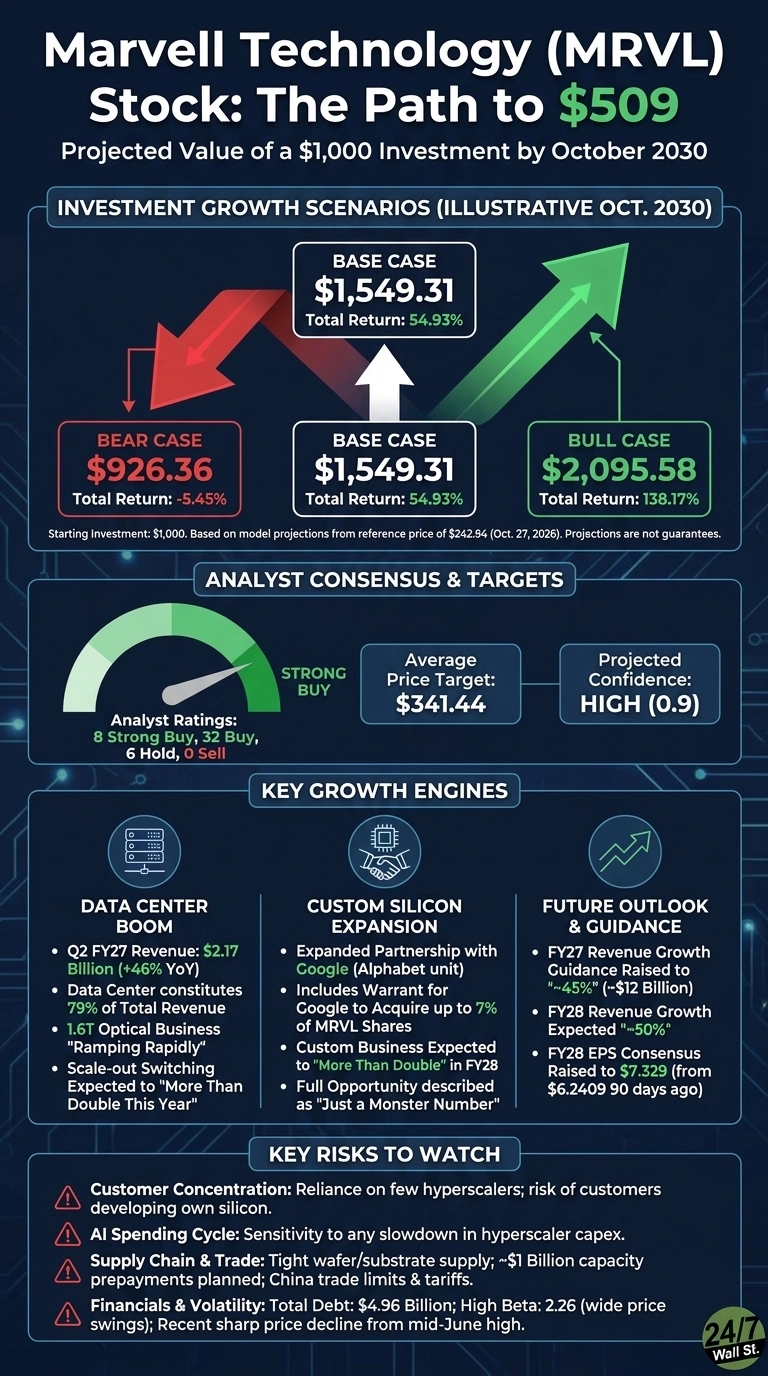
Bull, Base, and Bear Outcomes for a $1,000 Stake
| Scenario | Oct. 2030 Price (Illustrative) | $1,000 at Oct. 2030 (Illustrative) | 5-Year Target (Oct. 2031) | 5-Year Total Return | $1,000 at 5 Years |
|---|---|---|---|---|---|
| Bull | $509.10 | $2,095.58 | $578.61 | 138.17% | $2,381.70 |
| Base | $376.39 | $1,549.31 | $401.59 | 65.3% | $1,653 |
| Bear | $225.05 | $926.36 | $229.71 | -5.45% | $945.50 |
Wall Street leans heavily bullish. The stock has 8 strong buy, 32 buy, and 6 hold ratings with zero sells, and the consensus analyst target is $341.44.

Three Growth Engines Behind the Upside
Guidance Keeps Climbing
Second-quarter fiscal 2027 revenue reached $2.74 billion, up 36.5% from a year earlier and ahead of consensus. Non-GAAP EPS was $0.94 against a $0.93 estimate.
Management now expects fiscal 2027 revenue to grow “approximately 45% year over year to roughly $12 billion”, with fiscal 2028 growth of approximately 50%. Analysts have raised their fiscal 2028 EPS consensus to $7.329, up from $6.2409 90 days ago.
Custom Silicon Gets a Hyperscaler Anchor
Marvell expanded its custom silicon partnership with Alphabet (NASDAQ:GOOGL) unit Google. The deal includes a warrant that lets Google acquire up to 7% of Marvell’s shares tied to revenue milestones.
Management expects the custom business to “more than double year over year in fiscal 2028 and accelerate significantly in fiscal 2029,” and called the full opportunity “just a monster number.”
Optics and Switching Scale With AI Clusters
Data Center revenue rose 46% to $2.17 billion. The 1.6T optical business is “ramping rapidly,” and scale-out switching is expected to “more than double this year” on the strength of 51.2T products.
The acquisitions of Celestial AI and XConn Technologies, which closed in February 2026, add photonic fabric and chiplet connectivity for next-generation AI data centers.
Marvell sits in the layer of suppliers driving that expansion alongside the chipmakers, and we covered seven more of those non-chipmaker AI infrastructure names in a free report.

Risks That Could Leave a $1,000 Stake Underwater
The downside scenario shows how real the risk is: the model’s 5-year path ends at $945.50. The newest worry is the possible Lumentum purchase. Morningstar warned that the deal risks a steep overpay, and integration of the Celestial AI and XConn acquisitions is still underway.
- Concentration: Data Center made up 79% of revenue, and a small group of hyperscalers drives much of that total. Those customers could also design more of their own silicon.
- AI spending cycle: Any slowdown in hyperscaler capex would hit the growth story directly.
- Supply and trade: Wafer and substrate supply is tight. Marvell plans about $1 billion in capacity prepayments this fiscal year, and China trade limits and tariffs add uncertainty.
- Balance sheet and volatility: Total debt stands at $4.96 billion, and the stock’s beta of 2.26 means wide moves. Shares went from $278.67 in mid-June to $188.30 a month later.
What $1,000 in Marvell Could Mean by 2030
On the model’s illustrative October 2030 milestones, a $1,000 investment ranges from $926.36 in the bear case, reaching $2,095.58 in the bull case, with the base case near $1,549.31. At the fixed 5-year horizon, the range runs from $945.50 to $2,381.70.
The scenarios has no guarantee. Watch the stock as the Lumentum talks develop and the next earnings report comes. The projections should not be read as investment advice.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.