Not One Analyst Rates Microsoft a Sell. Is the Consensus View Right?
Jim Cramer calls Microsoft and its megacap peers millstones around investors' necks, while nearly every analyst on Wall Street says buy. One number due after December 31 will decide which side looks foolish.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Wall Street is bullish on Microsoft (NASDAQ:MSFT | MSFT Price Prediction), and the verdict is close to unanimous. The consensus target of $633.13 implies about 13.6% upside from the $557.22 premarket quote on November 5, 2026. Shares closed at $555.80 on November 4.

What Bulls Are Paying for at Microsoft
The fiscal first quarter, reported October 28, 2026, supported the sentiment. Non-GAAP EPS of $4.89 exceeded the $4.72 consensus, the sixth consecutive beat. Revenue reached $92.28 billion, up 18.8%. Azure expanded 48%, and commercial remaining performance obligations rose 73% to $677 billion. Management guided Azure to 49% to 50% growth in constant currency next quarter, and CFO Amy Hood said, “Customer demand continues to exceed available supply.”

Estimates are rising. The fiscal 2027 EPS consensus of $20.0232 was $19.7613 seven days ago, with five upward and no downward revisions over 30 days. The fiscal 2028 consensus is $24.1416. On those numbers, the stock trades at a forward P/E of 25 and a PEG of 1.5.
Cramer’s Case Against Megacap Tech
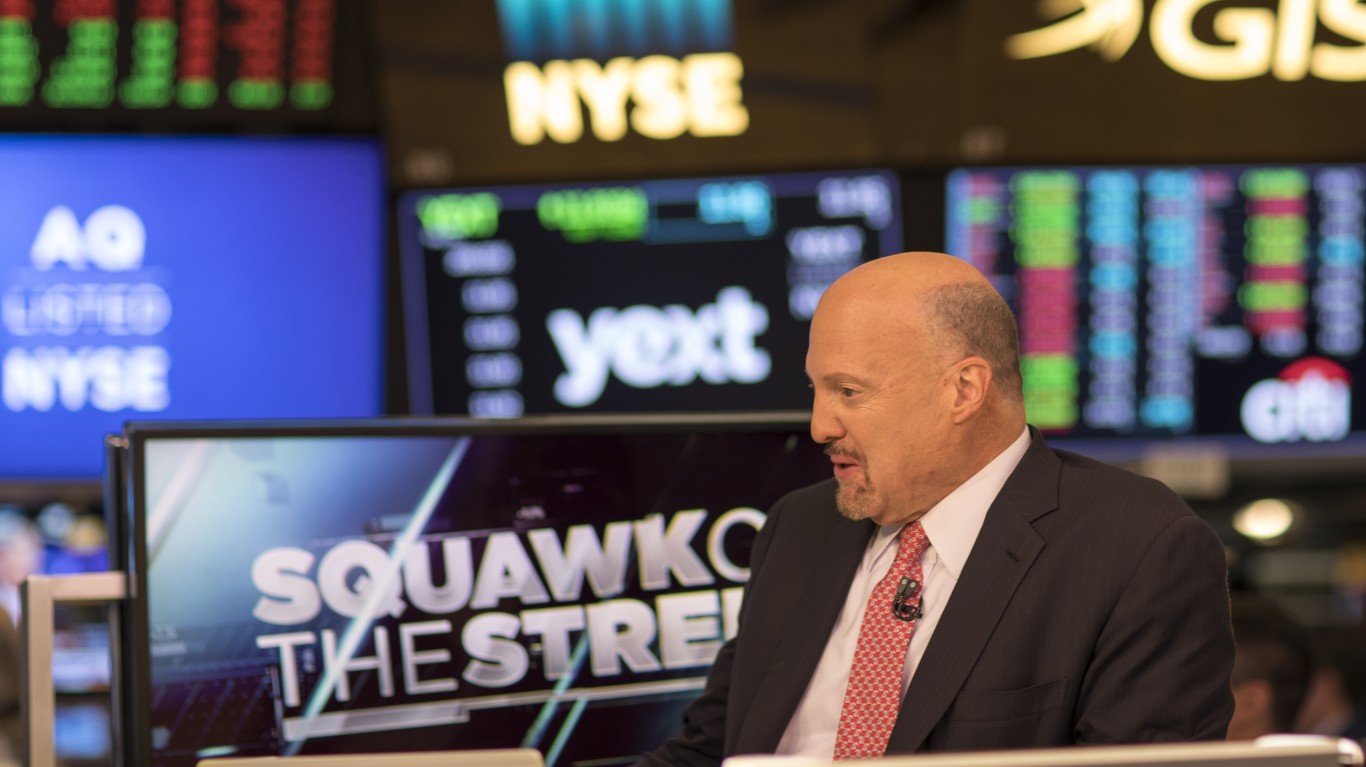
Jim Cramer took the opposite view on November 3, listing Microsoft among the tech leaders that “have almost been millstones. Millstones around investors.” He added that he would “wait for the crescendo before I commit too much money back to tech.”
The one-year chart backs part of his complaint. Microsoft gained only 9.6% over 12 months, and capital spending reached $39.37 billion in the quarter, up 102.99%, with calendar-year capex expected near $170 billion (that spending has to be powered, cooled, and networked by somebody, and we covered seven of those suppliers in a free AI infrastructure report). Commercial bookings fell 12%, and Windows OEM and devices revenue dropped 22%. Recent momentum cuts against him, though. Shares rose 2.8% in a week as hyperscalers rallied after election results removed investor uncertainty, leaving the stock just below its 52-week high of $559.15.
When Everyone Agrees on One Stock
A unanimous Buy list works as a contrarian warning for a simple reason: once nearly every analyst is already positive, few upgrades are left to draw in new buyers, and any stumble forces the whole group to revise at once. A crowded consensus also reflects what is already priced in.
It also reflects a business that keeps beating estimates. Institutional positioning is less unified than the ratings. Institutions own 75.7% of shares, yet among 20 tracked hedge fund filers as of June 30, 2026, nine trimmed, six added, and three exited. Millennium Management and Coatue Management increased their stakes, while D. E. Shaw and Viking Global reduced theirs.
What the Signal Means for Retail Investors
The analysts have the better evidence. Upward EPS revisions, a $677 billion backlog, and accelerating cloud growth outweigh a lagging one-year return, and the stock trades well above its 50-day average of $513.39 and its 200-day average of $438.18. The tradeoff is a modest 13.6% gap to the target from a price already near its 52-week high, so the remaining return depends on execution, with little help from a rerating.

One verifiable trigger settles the debate: Azure growth for the quarter ending December 31, 2026. A result below the 49% to 50% constant-currency guidance would show that $170 billion in spending is outpacing demand, supporting Cramer’s view. A result inside or above that range keeps the consensus intact. Until then, the data favors Wall Street.
Contact [email protected] for any questions or corrections.
Trey has been an editor and author at 24/7 Wall St. for more than a decade, where he has published thousands of articles analyzing corporate earnings, dividend stocks, short interest, insider buying, private equity, and market trends. His comprehensive coverage spans the full spectrum of financial markets, from blue-chip stalwarts to emerging growth companies.
Beyond 24/7 Wall St., Trey has created and edited financial content for Benzinga and AOL's BloggingStocks, contributing additional hundreds of articles to the investment community.
Trey's editorial expertise extends across multiple publishing environments. He served as production editor at Dearborn Financial Publishing and development editor at Kaplan, where he helped shape financial education materials. Earlier in his career, he worked as a writer-producer at SVE. His freelance editing portfolio includes work for prestigious clients such as Sage Publications, Rand McNally, the Institute for Supply Management, the American Library Association, Eggplant Literary Productions, and Spiegel.
Outside of financial journalism, Trey writes fiction and has been an active member of the writing community for years, moderating workshop sessions at regional conventions.