Piper Sandler Raises Microsoft Target, Sees Billions in Potential From E7 and AI
Piper Sandler just set one of Wall Street's boldest Microsoft targets, and the reasoning goes well beyond last quarter's blowout earnings. The case hinges on a new enterprise licensing tier that two months in is already reshaping how Microsoft charges…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Piper Sandler analyst Billy Fitzsimmons raised the firm’s price target on Microsoft (NASDAQ:MSFT | MSFT Price Prediction) to $610 from $550 and kept an Overweight rating.
He cited the company’s “Super App” announcement, the new E7 enterprise licensing plan and consumption-based pricing for Copilot and Cowork. The raised target shows growing Wall Street confidence that Microsoft can earn more per enterprise user from its AI tools.
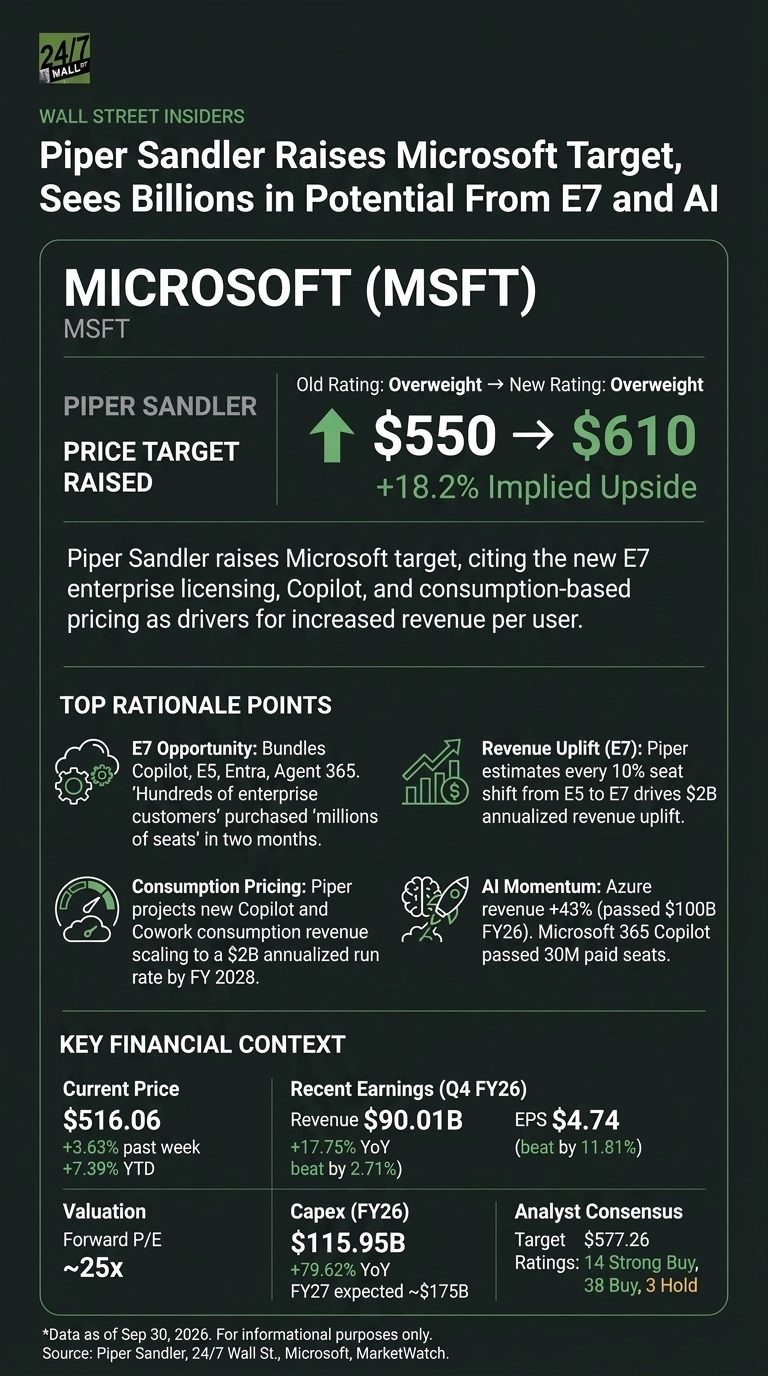
| Ticker | Company | Firm | Action | Old Rating | New Rating | Old Target | New Target |
|---|---|---|---|---|---|---|---|
| MSFT | Microsoft | Piper Sandler | Price Target Raised | Overweight | Overweight | $550 | $610 |
Analyst’s Case: E7 Could Unlock Billions in New Revenue
Piper estimates that every 10% shift of seats from E5 to E7 drives a $2B annualized revenue uplift. It also projects new Copilot and Cowork consumption revenue scaling to a $2B annualized run rate by fiscal 2028. It now has more confidence in the outlook for Microsoft 365.
E7 bundles “Copilot, E5, Entra and Agent 365”. Management said that “just two months after launch, hundreds of enterprise customers have already purchased millions of seats.”
EY rolled out E7 to 400,000 employees, which Microsoft called its largest win to date. Management also described a move from per-seat licensing to “seat plus usage” pricing.

Company Snapshot: Azure and Copilot Momentum
Fiscal Q4 2026 revenue came in at $90.01B, up 17.75% year over year and ahead of the $87.63B consensus. Non-GAAP EPS of $4.74 beat the $4.24 estimate. The result marked the company’s 5th straight EPS beat, and a $3.2B gain on Anthropic investment helped the result.

- Azure grew 43% and passed $100B in full-year revenue
- Microsoft 365 Copilot passed 30 million paid seats
- Commercial remaining performance obligations (signed future revenue) reached $678B, up 84%
Why the Move Matters Now for Microsoft Stock
Shares trade near $516.06. They are up 7.39% year to date and 3.63% over the past week. MarketWatch reported the stock is on track for its biggest quarterly gain in 28 years. Piper’s new target is above the consensus of $577.26. Among covering analysts, 14 rate the stock Strong Buy, 38 Buy and 3 Hold.

The stock trades at about 25x forward earnings. Estimates are going up: fiscal 2027 EPS forecasts saw 21 upward revisions and 8 downward revisions over the past 30 days. Management expects Microsoft 365 commercial cloud growth to accelerate through the fiscal year, driven by “momentum in co-pilot E5 and E7” and usage-based billing.
What It Means for Your Portfolio
Piper’s thesis rests on Microsoft 365, a subscription business with steady cash flow that is now adding AI pricing on top. Microsoft pays a 0.70% dividend yield and announced a quarterly dividend increase on September 15.
Spending is the main risk. Fiscal 2026 capex rose 79.62% to $115.95B, and management expects about $175 billion in fiscal 2027. Microsoft itself warns that large AI investments may not deliver the expected returns.
Things to watch next are how fast customers move to E7, how quickly Copilot consumption revenue grows and whether margins hold up as spending rises. For long-term investors, Piper’s view is worth a closer look, though short-term swings are still a real risk.
The scale of that capex, about $116B in fiscal 2026 with more on coming, is the reason the picks and shovels behind the data centers matter as much as the hyperscalers themselves (we covered seven of those suppliers, from power to cooling, in a free report you can download here: 7 Stocks Powering the AI Boom (That Aren’t Chipmakers)).
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.