Dell’s AI Server Business Could Unlock a New Growth Phase in 2027

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Dell Technologies (NYSE:DELL | DELL Price Prediction) has had a breakout 2026. Shares are up 165.55% year to date as AI servers moved from a side business to the center of Dell’s revenue.
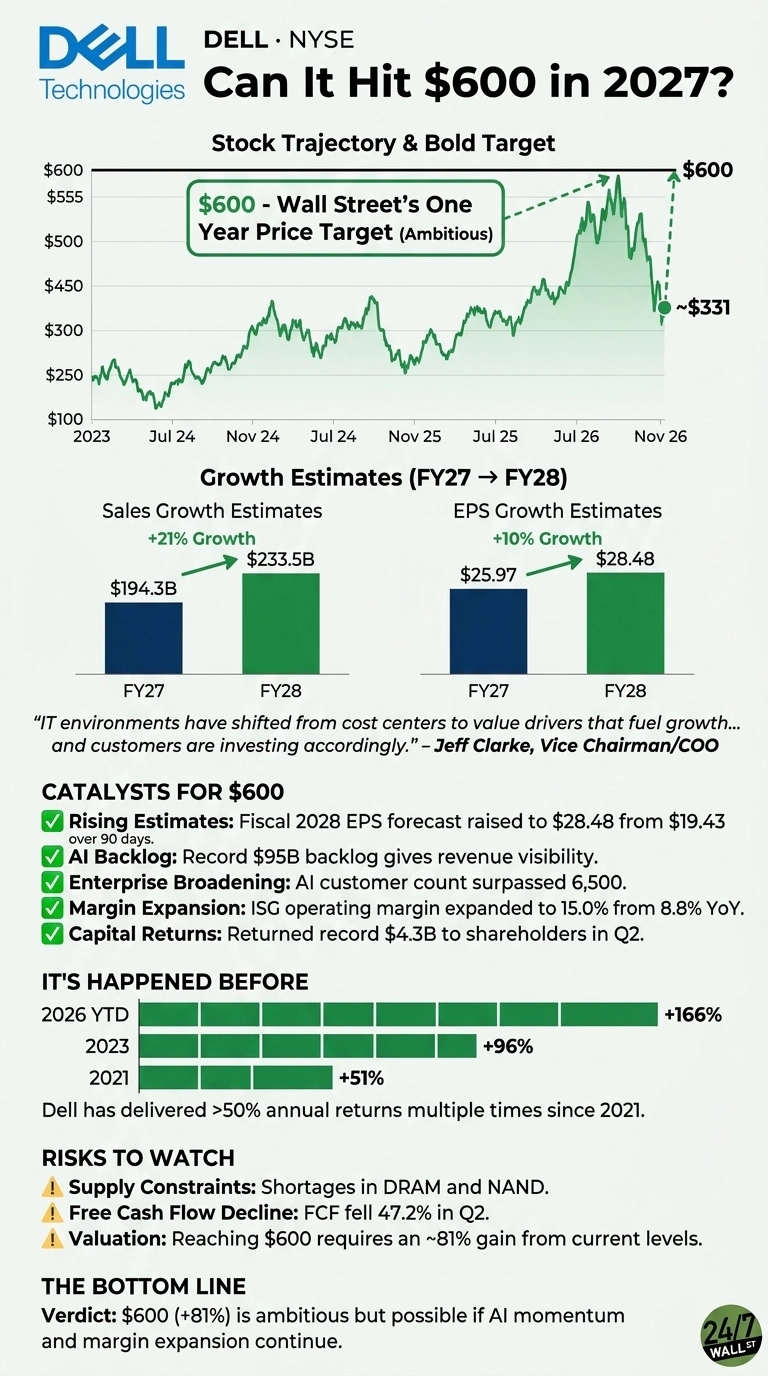
The run has been volatile. The stock fell 26.68% over the past month, and the current price of $330.75 stands far below the 52-week high of $594.69. Barron’s even ran a “time to sell” call this week. Below, I lay out how Dell could still hit $600 per share in 2027.

The business case starts with demand. In fiscal Q2, Dell booked a record $60.9 billion[1] in AI orders and ended the quarter with a $95 billion backlog. Jeff Clarke put it this way: “IT environments have shifted from cost centers to value drivers that fuel growth and competitive advantage, and customers are investing accordingly.”[1]
Wall Street Already Sees Big Upside for Dell
The consensus 1-year target is $583.68, which implies 76% upside. Analysts expect fiscal 2027 revenue of about $194.3 billion, and that figure climbs to $233.5 billion for fiscal 2028, the year that covers most of calendar 2027.
Estimates are also rising. Ninety days ago, the fiscal 2028 EPS forecast was $19.4275. Today it is $28.4833.

Here’s What It Takes for Dell to Reach $600
At $330.75, Dell trades at roughly 12x fiscal 2028 earnings estimates. At $600, the multiple would be about 21x, which still looks reasonable for a company guiding to 148%[1] non-GAAP EPS growth this year. Getting there mostly requires the market to give back the valuation it took away this fall.

Several factors could push Dell to $600.
- Earnings beat run: Dell has exceeded EPS estimates five straight quarters, including a 43.69% surprise in fiscal Q2. If that pattern holds, current forecasts are probably too low.
- Raised guidance: Management lifted fiscal 2027 revenue guidance to $192 billion[1], with AI server revenue of $74 billion.
- Enterprise broadening: AI customers have passed 6,500[2], and management said “the acceleration is enterprise.”
- Margin expansion: ISG operating margin expanded to 15%[1] from 8.8%, and traditional servers grew 122%.
- Product leadership: Dell was “the first to ship RAC systems engineered on the NVIDIA Vera Rubin platform.”[2]
- Capital returns: Dell returned a record $4.3 billion[1] to shareholders in Q2.

Among the key challenges are supply constraints in DRAM and NAND, along with free cash flow that fell 47.2%[1] in Q2.
Dell’s Track Record Says $600 Is Within Reach
Reaching $600 requires a gain of about 81%. Dell has done that recently.
In 2023, shares returned about 96%, and the 2026 gain of 165.55% is even larger. In 2024 and 2021, Dell gained roughly 56% and 51%. A $600 price would also sit less than 1% above the 52-week high, so the stock has already traded near that level.
$600 Is a Stretch, but the Blueprint Exists
Reaching $600 would mean an 81% gain in 2027. Analysts already expect 76% upside, EPS estimates keep rising and the $95 billion[1] backlog gives Dell revenue visibility.
If supply eases and the beat run continues, a return to a higher earnings multiple gets Dell there. Returns this large are rare, and this is the guide for how Dell could deliver outsized gains in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.