Amazon Could Be Building Toward Its Next Big Stock Market Breakout
AWS just delivered its fastest growth in years, but Amazon shares are sliding ahead of a make-or-break earnings report. What the next quarter reveals about cloud momentum could determine whether this stock surges past $300 or stalls out entirely.

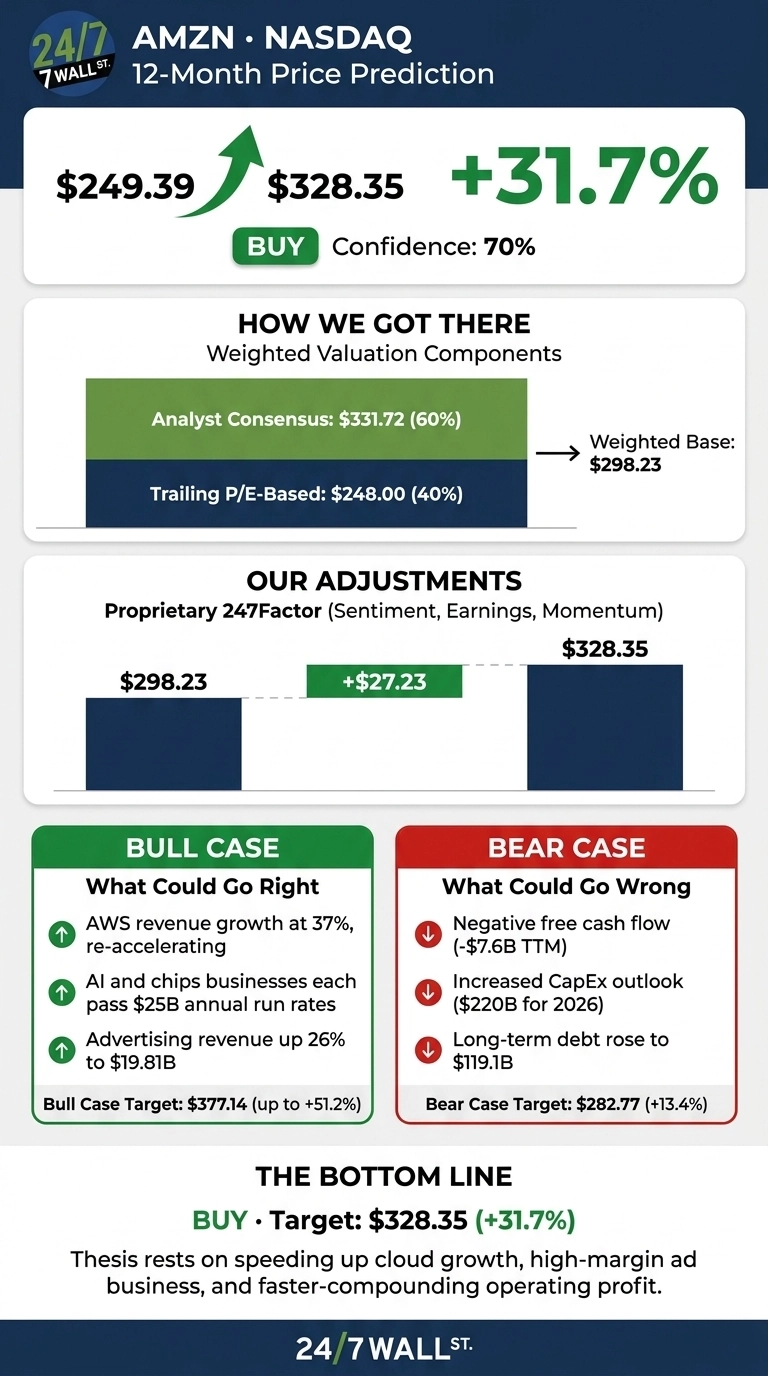
The 24/7 Wall St. price target for Amazon (NASDAQ:AMZN | AMZN Price Prediction) is $328.35 over the next 12 months. That sits roughly 31.7% above the current $249.39. We rate the stock a buy with 70% confidence, which reflects solid but measured conviction.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $249.39 |
| Price Target from 24/7 Wall St. | $328.35 |
| Upside/Downside | 31.7% |
| Recommendation | BUY |
| Confidence Level | 70% |

Amazon is expected to report third-quarter results on October 29, and the stock heads into that report with AWS growing faster than at any point in years.
Our thesis rests on three things: speeding up cloud growth, a high-margin ad business and an operating profit line that is compounding faster than revenue.
A Pre-Earnings Pullback Follows a Blowout AWS Quarter
Shares fell 4.98% over the past week. They are essentially flat over the past month (-0.11%) and up 8.05% year to date. The stock trades 13.2% below its 52-week high of $287.20 and 27.2% above its $196 low.
Second-quarter revenue rose 19.6% to $200.61 billion, beating the $196.43 billion estimate. GAAP EPS of $5.75 was raised by a $53.4 billion Anthropic gain. Comparable EPS of about $1.88 exceeded the $1.83 estimate. For the third quarter, Amazon guided operating income to $22.5 billion to $26.5 billion, compared with $17.4 billion a year earlier.
Why Bulls See $377 and Beyond
AWS revenue grew 37% to $42.23 billion, with a 39.4% operating margin. Backlog reached $496 billion, and Amazon’s AI and chips businesses each passed $25 billion run rates. CEO Andy Jassy said AWS could “very possibly be a trillion-dollar annual revenue business for us in time.”
Advertising grew 26% to $19.81 billion. Wall Street is nearly unanimous, with 16 strong buys, 43 buys and zero sells. The bull case reaches $377.14, about 51.2% upside.

Cash Burn Is the Risk Worth Watching
Amazon raised its 2026 capex outlook to about $220 billion, up from $200 billion, because memory costs are rising. Trailing free cash flow stands at -$7.6 billion, and long-term debt rose to $119.1 billion. Tariffs and FX challenges add pressure.
Management counters that servers break even in “a little less than three years” and that most AI capacity is signed for at least five-year terms. The bear case of $282.77 still sits 13.4% above today’s price.
The AI expansion driving that capex is also powering a wave of suppliers in data-center electricity, cooling, and networking (we broke down seven of them, none of them chipmakers, in a free report here: 7 Stocks Powering the AI Boom).
Is Amazon Pricier Than Microsoft and Alphabet?
Microsoft (NASDAQ:MSFT) is AWS’s most direct cloud rival. Azure grew 43%, and Microsoft trades at 30x earnings with a 46.8% operating margin. That margin is far higher than Amazon’s because Microsoft has no retail arm reducing it.
Alphabet (NASDAQ:GOOGL) competes with Amazon in both cloud and ads. Google Cloud grew 82%, and its 14x P/E is inflated by a $99.03 billion equity gain.
| Company | P/E | Cloud Growth | Operating Margin |
|---|---|---|---|
| Amazon | 35x | 37% | 11.16% |
| Microsoft | 30x | 43% | 46.8% |
| Alphabet | 14x | 82% | 32.1% |
Amazon carries the highest earnings multiple of the three, so the peer group makes the 24/7 Wall St. price target look reasonable but dependent on continued margin gains at AWS.
I’d Buy Amazon Ahead of Its Next AWS Leg
The 24/7 Wall St. price target is $328.35, with a buy rating at 70% confidence. AWS tips the scale for me: growth has speeding up for the fifth straight quarter.
I’d be a buyer if the October 29 report shows AWS holding mid-30s growth. I’d step aside if capex keeps rising while cloud growth stalls.

| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $254.41 |
| 2027 | $334.45 |
| 2028 | $395.10 |
| 2029 | $467.00 |
| 2030 | $502.25 |
These projections assume Amazon keeps executing on its AI infrastructure strategy. Faster Trainium adoption could drove the stock well above these levels, while extended negative free cash flow could pull it below them.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.