TSMC’s AI Opportunity Is Expanding. Here’s the Question That Matters for Its Stock Price
TSMC just posted its third straight earnings beat while AI demand outstrips supply, yet shares have dropped nearly 11% in a month. One question from the CFO's own playbook now determines whether the stock recovers or stalls from here.

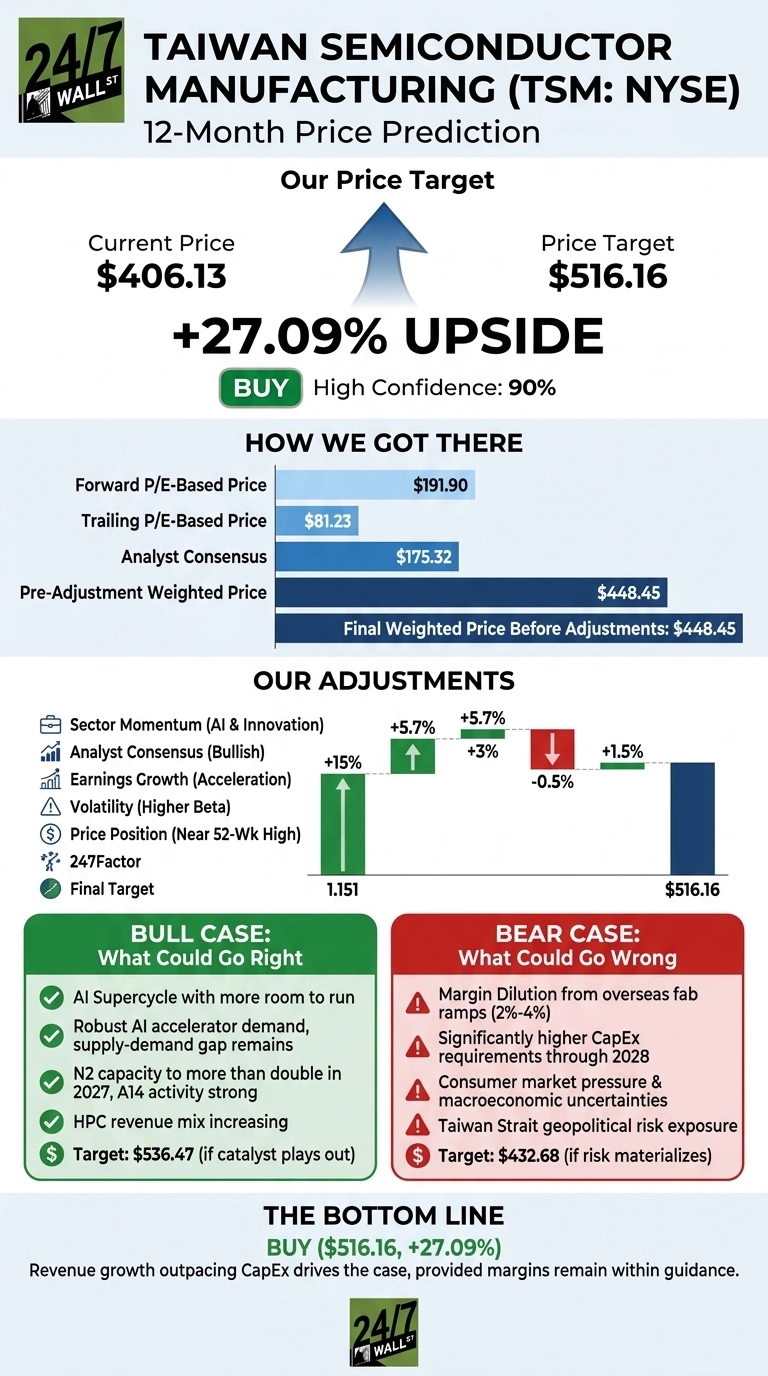
Taiwan Semiconductor Manufacturing (NYSE:TSM | TSM Price Prediction), better known as TSMC, last closed at $406.13. For TSMC, the 24/7 Wall St. price target is $516.16 over the next 12 months. That implies 27.09% upside, and our model rates the stock a buy with high confidence.
| Metric | Value |
|---|---|
| Current Price | $406.13 |
| Price Target from 24/7 Wall St. | $516.16 |
| Upside/Downside | 27.09% |
| Recommendation | BUY |
| Confidence Level | 90% |

For TSMC, the key question is whether it can convert surging AI demand into profit while 2nm ramps and spending rises.
Chief financial officer Wendell Huang framed it directly: “If we do our job right, the increase in revenue will outpace the increase in CapEx, and that is still the case from what we are looking at.”
A Sharp October Pullback Follows a Record Quarter
Shares fell 2.96% over the past week and 10.97% over the past month, including a 5.95% drop on October 30. TSMC is still up 34.67% year to date and sits 16.7% below its 52-week high of $487.47 and 53.6% above its low of $264.34.
Third-quarter EPS of $4.60 beat the $4.46 consensus, the third straight beat. Revenue reached $46.72 billion, up 41.2% in dollars. Fourth-quarter guidance of $52.3 billion to $54.3 billion implies 58% growth at the midpoint, and full-year growth is now guided to roughly 44%.
Bulls See an AI Supercycle With More Room to Run
Our bull case reaches $536.47. Asked about AI accelerator growth, C.C. Wei said “It probably will be higher,” adding that “the gap between demand and supply is still quite big.” N2 capacity should more than double in 2027, and A14 customer activity already exceeds 2nm. HPC made up 68% of revenue.
Analysts are generally in agreement: 20 of 21 rate TSMC a buy or strong buy, with a consensus target of $584.39. The foundry benefits no matter which accelerator wins, and we identified seven other suppliers riding the same AI expansion in a free report here.

Margin Dilution Is the Risk Worth Tracking
Our bear case lands at $432.68. Gross margin fell 1.3 points sequentially, and management expects overseas-fab dilution to increase from about 2% to 3%–4%.
Capex through 2028 will run significantly higher, consumer markets face pressure, and Taiwan Strait exposure persists. Bullish observers note that the dilution comes from the 2nm ramp, and guided margins of 65% to 67% remain far above TSMC’s 56%+ long-term target.

Is TSMC Cheaper Than NVIDIA and Broadcom?
NVIDIA (NASDAQ:NVDA) designs the AI accelerators TSMC makes. The company trades at a lower forward multiple while growing revenue about twice as fast.
Broadcom (NASDAQ:AVGO) competes for the same custom AI silicon and networking budgets, and it carries a far higher trailing multiple.
| Company | Forward P/E | Trailing P/E | Revenue Growth (YoY) |
|---|---|---|---|
| TSMC | 18x | 26x | 50.9% |
| NVIDIA | 13x | 26x | 105.9% |
| Broadcom | 17x | 42x | 85.5% |
TSMC’s slight forward premium buys diversification across every AI architecture. That makes the 24/7 Wall St. price target look reasonable.
Our Verdict: TSMC Earns a Buy Rating
Our 24/7 Wall St. price target of $516.16 and a buy rating at 90% confidence rest on one factor: revenue growth that is outpacing capex.
The case strengthens if fourth-quarter margins land within guidance as 2nm scales. I’d turn cautious if margins slip below 65% or hyperscalers cut spending. Our model’s bull case sits further above the current price than its bear case sits below it.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $424.04 |
| 2027 | $516.16 |
| 2028 | $578.84 |
| 2029 | $649.12 |
| 2030 | $727.95 |
The outlook depends on TSMC continuing to execute on 2nm and A14. Faster AI adoption could push results higher, while Taiwan Strait tensions or a capex burden could pull them lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.