Price Prediction: TSMC Could Reach $600 as Capacity Constraints Drive the AI Boom Forward
TSMC is booking capacity it cannot build fast enough, and a $60 billion capital bet suggests management sees something the market has not yet priced in. Here is what the numbers reveal about how far this stock can run.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Taiwan Semiconductor Manufacturing (NYSE:TSM | TSM Price Prediction) has become the plumbing of the AI economy, and the stock has responded in kind. Shares trade at $449.17, up 48.95% year to date and 60.52% over the past year.
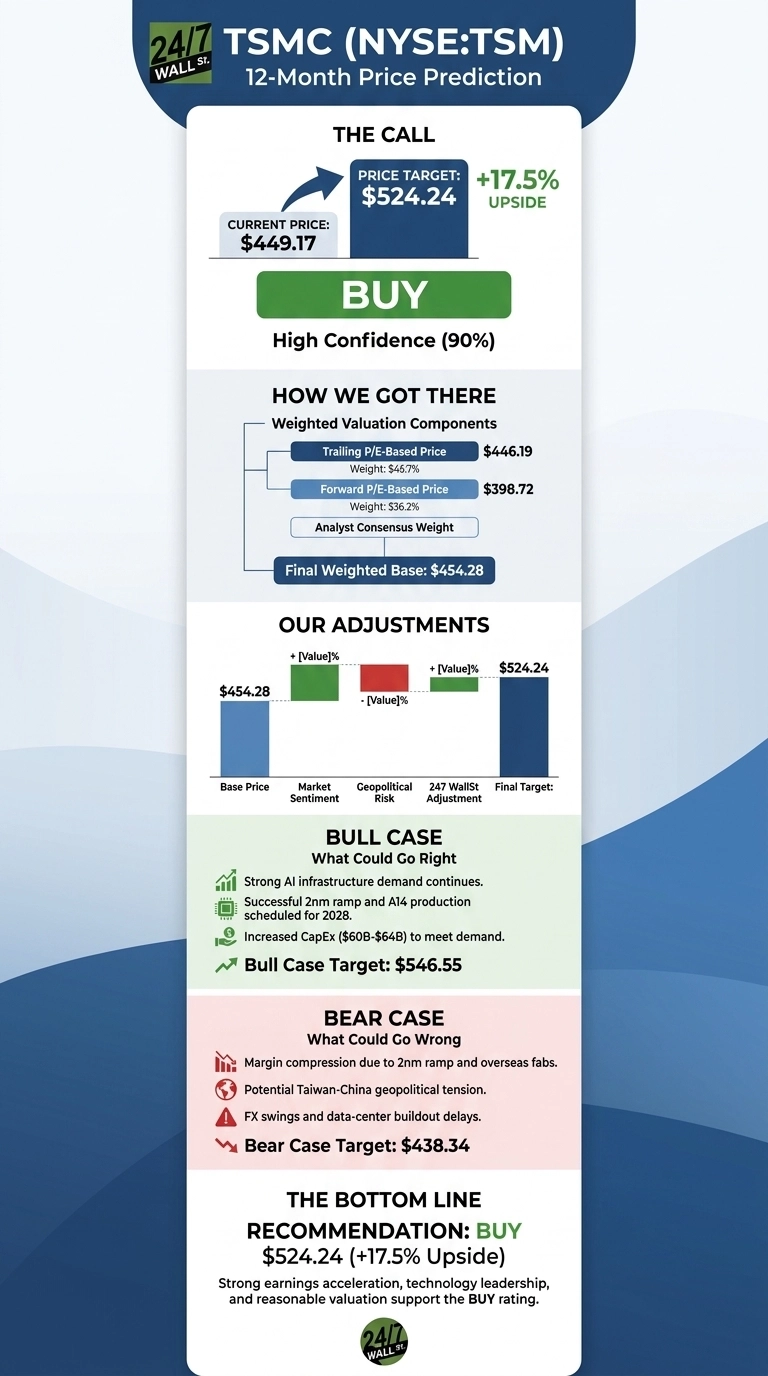
Our 24/7 Wall St. price target for TSMC is $524.24, implying 17.49% upside over the next 12 months. Our recommendation is buy, with a high confidence reading of 90%.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $449.17 |
| 24/7 Wall St. Price Target | $524.24 |
| Upside | 17.49% |
| Recommendation | BUY |
| Confidence Level | 90% |

A Blowout Quarter and a Raised Full-Year Outlook
TSMC’s second-quarter 2026 report set the tone. Revenue reached $40.20 billion, up 36.05% year over year, with EPS of $4.31 beating expectations. Gross margin expanded to 67.7%, and advanced nodes at 7 nanometer and below made up 77% of wafer revenue.
Management raised full-year 2026 revenue guidance to slightly above 40% growth in U.S. dollar terms. August monthly filings showed revenue up 53.3% year over year, with year-to-date sales up 39.3%.
Why Bulls See a Path to $600+
The bull case rests on capacity TSMC cannot build fast enough. Management characterized conviction in the AI megatrend as “very high” and lifted the 2026 capital budget to $60 billion to $64 billion.
The 2nm ramp already contributes 3% of wafer revenue in its first quarter, A14 volume production is scheduled for 2028, and advanced packaging capacity is insufficient to meet demand.
With the 2027 consensus EPS estimate now at $21.93, up from $19.66 ninety days ago, a re-rating toward the Street’s $552 target is realistic. A bull-case path to $546.55 in 12 months would represent roughly 22% upside.

What Could Go Wrong for TSMC
The near-term risk is margin compression. Management flagged the 2nm ramp as likely to dilute gross margin by 3 to 4 percentage points in the second half, with overseas fabs adding another 2% to 3% of dilution. Q3 guidance calls for gross margin of 65% to 67%, down from Q2.
This reflects deliberate investment: capex is pulled forward to lock in customer commitments. Longer-term risks include Taiwan-China geopolitical tension, FX swings against the NTD, and AI data-center buildout delays. The bear scenario sees the stock at $438.34 one year out.
How TSMC Compares to NVIDIA and ASML
NVIDIA (NASDAQ:NVDA) is TSMC’s largest AI customer. NVIDIA trades at a forward P/E of 25 against TSMC’s 22, with quarterly revenue growth of 105.9%. That NVIDIA commands a premium despite far higher volatility (beta 2.22) suggests TSMC’s multiple is reasonable.
ASML (NASDAQ:ASML) sits upstream as TSMC’s EUV lithography supplier. ASML trades at a forward P/E of 28 with quarterly revenue growth of 21.3%, materially slower than TSMC’s 36%. The peer set supports our 24/7 Wall St. price target as reasonable.
| Company | Forward P/E | YoY Revenue Growth |
|---|---|---|
| TSMC | 22 | 36.0% |
| NVIDIA | 25 | 105.9% |
| ASML | 28 | 21.3% |
Why TSM Screens Attractive at This Level
The 24/7 Wall St. price target of $524.24 backs a buy rating with 90% confidence. Accelerating earnings, undisputed technology leadership, and a forward multiple aligned with fundamentals support the call.
The setup strengthens if Q3 gross margins come in at the high end of guidance and the 2nm ramp stays on track. The thesis weakens if Q3 margins slip below 65% or AI capex commentary from hyperscalers softens into year-end.
Our model projects TSM could trade in the coming years, assuming current growth trajectories and market conditions hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $455 |
| 2027 | $524 |
| 2028 | $602 |
| 2029 | $637 |
| 2030 | $697 |
These projections assume TSMC continues executing on its 2nm and A14 roadmap and that AI infrastructure demand holds through 2029.
Significant upside or downside could come from a Taiwan-Strait geopolitical event or a faster-than-expected shift by hyperscalers toward custom in-house silicon. Spotting the next chipmaker to run like this one starts with the same early traits we cataloged in a free playbook here.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.