This Company Behind the World’s AI Chips Could Be a Huge Winner
Every major AI chip bears the fingerprints of one manufacturer, and that company just raised its full-year growth outlook for the third time. Whether the stock's recent pullback is an opportunity or a warning sign depends on a few critical…

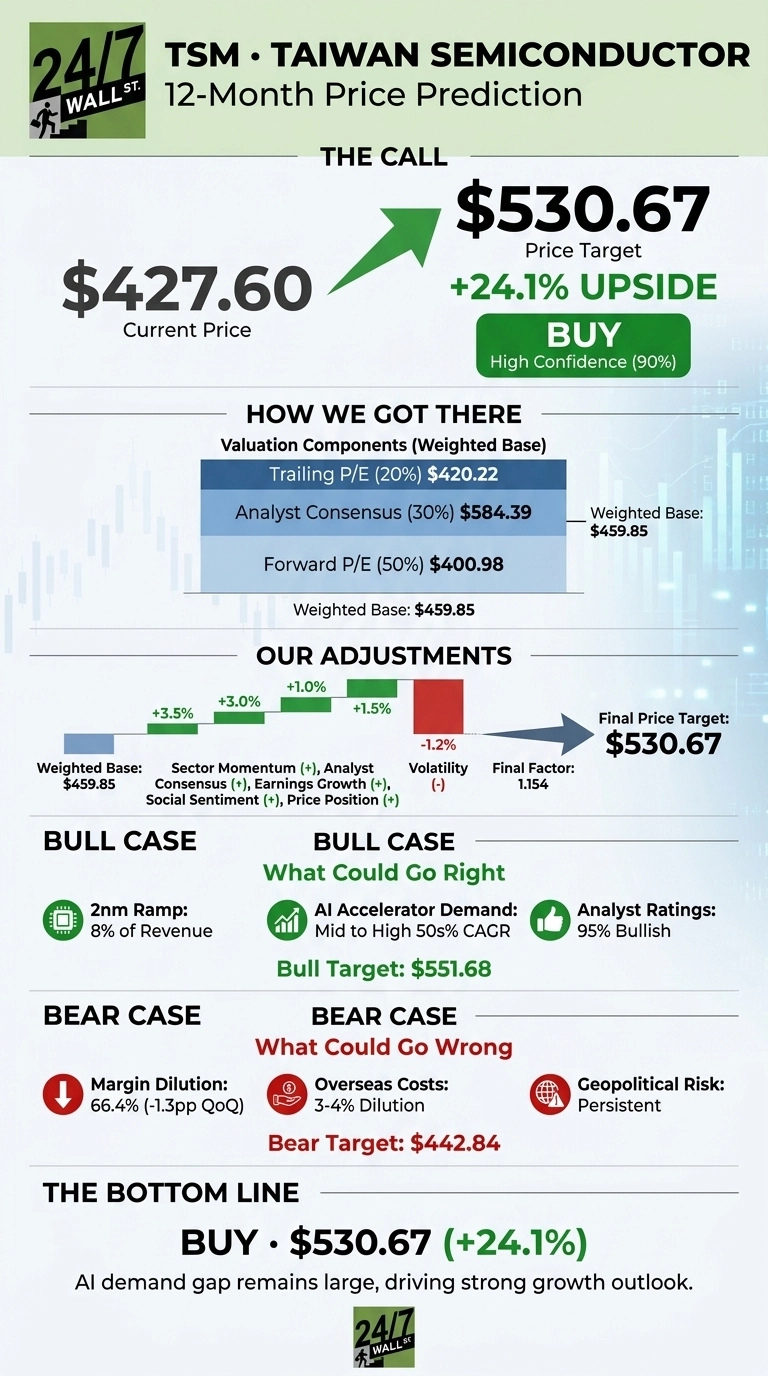
The 24/7 Wall St. price target for Taiwan Semiconductor Manufacturing (NYSE:TSM | TSM Price Prediction) is $530.67 over the next 12 months. Our model rates the stock a buy.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $427.60 |
| Price Target from 24/7 Wall St. | $530.67 |
| Upside | 24.1% |
| Recommendation | BUY |
| Confidence Level | 90% |

A 90% confidence reading is the top of our model’s “high” range.
TSMC makes the leading-edge silicon behind nearly every major AI accelerator, and management has now raised its full-year 2026 growth outlook three times, from close to 30% to approximately 44% in U.S. dollar terms. In management’s own words: “All the AI players are working with TSMC.”
Record Quarter Meets a Post-Earnings Pullback
Shares are up 41.79% year to date and 6.57% over the past quarter. They have slipped 3.77% over the past week and 1.63% over the past month. That leaves TSMC 12.3% below its 52-week high of $487.47 and 61.8% above its low of $264.34.
The October 15 earnings report gave the pullback little fundamental support. EPS per ADR came in at $4.60 against a $4.4614 estimate.
Revenue reached $46.72 billion, up 41.2% year over year in dollars and above the high end of guidance. Fourth-quarter guidance of $52.3 billion to $54.3 billion means 58% year-over-year growth at the center.
Why Bulls See $550 and Beyond
The 2nm ramp is the engine. It went from 3% of wafer revenue to 8% in a single quarter. Management expects N2 capacity to more than double in 2027, and A14 volume production is set for 2028.
Management had presented AI accelerator growth as a mid to high 50s CAGR through 2029. Asked about that figure, they said: “It probably will be higher.” Of the analysts following TSMC, 6 rate it strong buy, 14 rate it buy and just 1 rates it hold. Our bull scenario reaches $551.68.

Margin Dilution and Capex Are the Risks to Track
Gross margin fell 1.3 percentage points from the prior quarter to 66.4%. Management expects dilution from overseas fabs to increase to 3-4% over the next few years.
The 2026 capital budget stands at $60 billion to $64 billion, and non-operating income dropped from NT$95.83 billion to NT$34.59 billion. Cross-strait tensions are still a persistent source of risk for the chip supply chain (European Court of Auditors). Our bear scenario comes to at $442.84.
Dilution is normal on a new node, and margins still sit far above the long-term target of 56% and higher. Demand is higher than supply, management notes, which supports pricing power.
TSMC Trades at a Discount to NVIDIA on Forward Earnings
TSMC’s top AI customer is NVIDIA (NASDAQ:NVDA). Its revenue grew 105.85% last quarter, and that growth turns directly into TSMC wafer orders.
Broadcom (NASDAQ:AVGO) relies on outsourced manufacturing for its custom AI accelerators. Its AI semiconductor revenue rose 221% in its latest quarter.
| Company | Forward P/E | Trailing P/E |
|---|---|---|
| TSMC | 21x | 27x |
| NVIDIA | 25x | 27x |
| Broadcom | 19x | 43x |
TSMC gets paid no matter which chip design wins the AI race, yet it trades below NVIDIA on forward earnings. Its forward multiple is close to Broadcom’s. Against this group, the 24/7 Wall St. price target looks reasonable, maybe even conservative.
AI Demand Keeps TSMC a BUY
The 24/7 Wall St. price target of $530.67 comes with a buy rating and 90% confidence. What tips the scale is a demand gap that management calls “still quite big.”
I’d stay positive as long as the 2nm ramp holds and fourth-quarter revenue comes to within guidance. I’d turn cautious if hyperscaler capex slows or overseas dilution runs past the 3-4% range. For now, the growth outweighs those risks.
Here is where our model projects TSMC could trade if current growth trends and market conditions hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $430.37 |
| 2027 | $530.67 |
| 2028 | $624.36 |
| 2029 | $716.18 |
| 2030 | $767.23 |
TSMC’s strategy execution supports these projections. The A14 launch and the U.S. expansion could add upside, while rising geopolitical tension could pull results lower.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.