Vistra Cratered by 25% This Year: One Wall Street Team Says 110% Returns Ahead for Investors
Hyperscalers lined up for Vistra's nuclear power, yet Texas price doubts just knocked the stock to a 52-week low. Is the Street seeing a bargain or ignoring a crack in the thesis, and why does a rival look even cheaper?

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

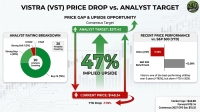
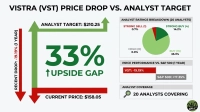
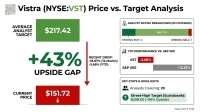
Vistra (NYSE:VST | VST Price Prediction) currently trades at $120.24, while the consensus analyst price target stands at $204.32. That means upside of roughly 69.9%.
Vistra runs a nuclear, gas, solar, and storage fleet alongside a retail power business. Hyperscalers turned it into a Wall Street favorite. Meta Platforms (NASDAQ:META) signed 20-year PPAs for more than 2,600 MW at Vistra’s PJM nuclear sites, and Amazon (NASDAQ:AMZN) unit AWS contracted up to 1,200 MW at Comanche Peak. A gap this wide points to one of two things: deep mispricing or a broken thesis.
Texas Doubts and Soft ERCOT Prices Sink Vistra to a 52-Week Low
Weaker Texas power economics did the most damage. Vistra is down 25.13% this year and 34.88% over 12 months, so the one-year decline is past 30%. The stock fell 13.86% in the latest session alone and reached a 52-week low of $117.28. CEO Jim Burke has said that ERCOT wholesale prices near $30 per MWh are too low to support new plants: “30 is not going to get new stuff built.”
A Texas moratorium on data center approvals pending audits obscured the AI load story. CFO Kris Moldovan then said lower ERCOT forward curves leave the 2027 adjusted EBITDA opportunity of $7.4 billion to $7.8 billion “trending towards the lower end of that range.” Second-quarter revenue of $4.02 billion also missed consensus by 27.24%, partly because of a $472 million unrealized hedge loss.
The pressure is hitting the whole sector, even as the S&P 500 gained 1.65% in the latest session.
Wall Street Still Prices In a Contracted Nuclear Growth Story
Of the 23 analysts covering Vistra, four call it a Strong Buy and 18 give a Buy rating. Only one rates it Strong Sell. BNP Paribas Exane analyst Moses Sutton has the Street-high target of $255.00, which means roughly 112% upside. His case rests on three things: faster hyperscaler PPA signings, high ERCOT and PJM capacity prices, and the nuclear scale Vistra gained from the Energy Harbor deal.
Among the concrete catalysts, management reaffirmed 2026 adjusted EBITDA guidance of $6.80 billion to $7.60 billion. The Meta PPAs start contributing in 2027. The roughly 5,500 MW Cogentrix gas acquisition has FERC approval and is targeted to close in the second half of 2026. Management says those two deals could add roughly $700 million to the 2027 midpoint (we mapped five ways to play the nuclear restart, from utilities to fuel suppliers, in a free report here).
Vistra has hedged about 100% of its 2026 generation and roughly 94% of 2027, and $1.2 billion in buyback authorization remains. Skeptics point out that hedge coverage falls to about 72% in 2028, which leaves more output exposed to soft Texas prices.
NRG Fell Harder, and Analysts See Even More Upside There
The entire peer group declined in together.
Constellation Energy (NASDAQ:CEG) is down 30.13% this year to $245.72. Its $339.25 average target means about 38.1% upside. Analysts give it six Strong Buy ratings, 14 Buy ratings, and five Hold ratings. That upside is smaller than Vistra’s, partly because Constellation still trades at a forward P/E of 19.
NRG Energy (NYSE:NRG) has fared worst, sliding 46.95% this year to $83.19. Its $172.89 target means about 107.8% upside, a larger gap than Vistra’s consensus. Analysts give it three Strong Buy ratings, 12 Buy ratings, and three Hold ratings.
NRG has the biggest consensus upside among its peers. Vistra only matches it using BNP’s Street-high target, so Vistra’s discount is real but less extreme. These targets are all opinions, and each assumes the AI power thesis holds up.
Vistra Trails the S&P 500 by a Wide Margin This Year
Vistra trades at $120.24. The $204.32 consensus target from 23 analysts means about 69.9% upside. Shares are down 25.13% this year, while the S&P 500 is up 12.45%. The past month alone took off 17.01%.
The stock trades at 13 times forward earnings and 24 times trailing earnings. That gap shows the market discounting earnings growth that analysts already build into their models.
Vistra’s Discount Looks Overdone if Contracts Keep Coming
Shares could rally if hyperscalers keep signing contracts, Cogentrix closes on schedule, and the Meta PPAs lift 2027 EBITDA toward the upper half of management’s range. That path, plus regular buybacks, is how the stock could work its way back toward $204.32.
The bear case gains weight if ERCOT prices stay near $30 per MWh, the Texas audit reduces the realistic data center pipeline, and 2027 lands at the low end of the range as hedges roll off.
Near-unanimous Buy ratings suggest analysts see contracted nuclear revenue outweighing the noise in Texas power prices. NRG offers a larger consensus gap, though, and the upcoming third-quarter earnings report is the next real test. Watch for how the stock reacts to any updated 2027 commentary.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.