This Could Be the Most Undervalued AI Stock Heading Into 2027

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Memory chips used to be the most cyclical, generic corner of the semiconductor market. In 2026, Micron Technology (NASDAQ:MU | MU Price Prediction) changed that.
Fiscal 2026 revenue reached $133.19 billion, up 256.3%[1], and fiscal Q4 non-GAAP gross margin hit 87% versus 45.7% a year earlier. The Q4 release is out. In it, CEO Sanjay Mehrotra said: “AI is becoming Super Intelligence (SI), and memory enhances this intelligence and the competitiveness of our customers’ platforms.”[1]
Shares are up 157.38% year to date. They have also fallen 18.89% over the past month, leaving the stock about 41% below its 52-week high of $1,254.61. That pullback raises the question for this article: what would Micron need to do to reach $1,600 in 2027?

Analysts See More Than 100% Upside for Micron
The average analyst price target of $1,561.91 implies about 113% upside from today’s $734. Analysts are heavily bullish: 45 rate the stock a Buy or Strong Buy, and only 1 rates it a Strong Sell.

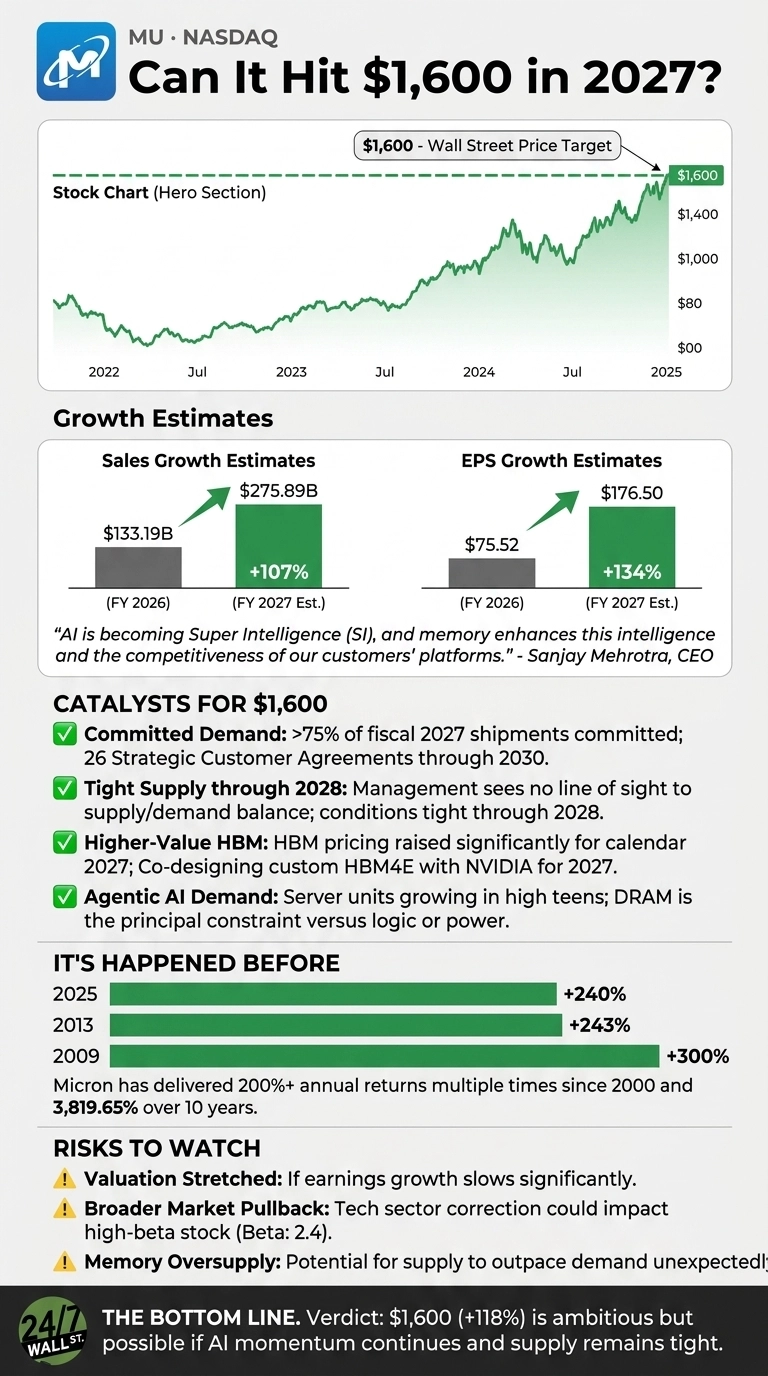
For fiscal 2027 (ending August), the consensus calls for $275.89 billion in revenue, about 107% growth. The EPS estimate of $176.5017 is roughly 134% above fiscal 2026’s $75.52[1].
Ninety days ago, that EPS estimate was $155.7946. Micron has also beaten EPS estimates nine straight quarters, so actual results could land above these forecasts.

Here’s What It Takes for Micron to Reach $1,600
At $734, Micron trades at just 4x fiscal 2027 estimates. At $1,600, that multiple would still be only 9x, far below the S&P 500’s forward multiple of roughly 22x. On fiscal 2028 EPS estimates of $207.7605, $1,600 works out to about 8x.
Memory stocks usually get low multiples because investors are pricing in the next downturn, but the bull case says Micron’s long-term customer contracts take some of that cycle risk away.

What Could Push Micron to $1,600?
- Committed demand: Micron has signed 26[2] Strategic Customer Agreements running through 2030, and more than 75% of fiscal 2027 shipments are already committed.
- Supply is tight. Management said, “We really don’t have line of sight to when supply and demand balance.”[2] CFO Mark Murphy expects conditions to stay tight through 2028.
- Higher-value HBM: Micron raised HBM pricing “significantly”[2] for calendar 2027. It is also co-designing a custom HBM4E product with NVIDIA (NASDAQ:NVDA), with HBM4E volume production targeted for calendar 2027[3].
- Agentic AI: Server units are growing “in the high teens,”[2]. Management called DRAM “the principal constraint versus logic or power to the data center.”[2]
- Near-term guidance: Fiscal Q1 2027 guidance calls for $61.5 billion ± $1.5 billion[1] in revenue and $38.15 ± $1.00 in non-GAAP EPS.
Micron’s History Shows $1,600 Is Possible
Getting to $1,600 requires a gain of about 118%. Based on split-adjusted prices, Micron has topped that in three full calendar years since 2000: 300% in 2009, 243% in 2013, and 240% in 2025. The 157.38% gain so far in 2026 would make a fourth. Over 10 years, shares have returned 3,819.65%.
With a market cap near $798 billion, doubling again is harder. A beta of 2.398 also means losses can be as sharp as gains. We reverse-engineered what the biggest tech successes looked like before their runs and turned it into a free playbook you can grab here.
Is $1,600 Realistic? Here’s My Take
Reaching $1,600 would require Micron to gain about 118%. Analysts already see 113% upside, earnings estimates keep going up, and even $1,600 would value the stock at only 9x forward earnings.
The main risks are a memory oversupply or a slowdown in AI spending, but management sees tight supply through 2028, and three-quarters of next year’s shipments are already committed. Returns at this level are rare, and this is the pattern for how Micron could deliver outsized gains in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.