3 Dividend Aristocrats Yielding More Than the 2027 COLA
Social Security just promised retirees a raise, but three blue-chip payers have been handing out bigger starting checks and annual bumps for decades. One pays monthly, one holds a record no other REIT can touch, and one carries a warning…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Social Security benefits rise 3.6% under the 2027 cost-of-living adjustment, and that figure is the bar for this list. The two numbers measure different things. A COLA is a percentage raise applied to a benefit you already collect. A dividend yield is the annual cash a stock pays, expressed as a share of what you pay for the stock today.
What they share is a yearly raise. Each Dividend Aristocrat below (an S&P 500 company with a quarter century or more of consecutive dividend increases) currently yields more than the COLA percentage, and each has lifted its payout year after year. The government resets the COLA annually and corporate boards vote on dividends, so every future raise depends on conditions at the time it is decided.
Realty Income Pays Every Month and Has Raised the Payout 116 Quarters in a Row
Realty Income (NYSE:O) owns commercial property leased to businesses under long-term net leases, where tenants cover most property costs. The portfolio spans 15,536 properties, 1,842 clients in 96 industries, and all 50 states plus the United Kingdom and eight other European countries, with occupancy at 98.8%.
At $59.31 per share, the stock yields 5.20%, the highest on this list. Investors receive $0.2715 per share each month, an annualized $3.258 (if a quarterly check feels too infrequent, we rounded up seven other monthly payers in a free report here). Realty Income belongs to the S&P 500 Dividend Aristocrats index, has declared 676 consecutive monthly dividends, and its latest raise marked its 116th consecutive quarterly dividend increase.
Dividend safety: Free cash flow yield comes in at 6.88%, above the dividend yield, so the business generates more cash than it pays out. Management raised its 2026 adjusted funds from operations (AFFO) guidance to $4.45 to $4.46 per share, well above the annualized dividend. Debt to equity runs at 0.83, the revolving credit facility was upsized to $5.5 billion, and equity needs are fully prefunded for the remainder of the year.
Why the raises can continue: AFFO per share rose 3.7% to $1.12 last quarter. The company invested $2.6 billion at a 6.8% initial cash yield and re-leased expiring properties at 103.5% of prior rent. New money now flows into industrial properties, data centers and European real estate, expanding the base that funds each small monthly bump. Sumit Roy, the chief executive, pointed to a "well-funded balance sheet" behind the confirmed $10.0 billion investment target.
The risk: Realty Income borrows heavily to grow, which makes interest rates the main threat to future raises. Interest expense climbed to $333.6 million from $294.5 million, net debt to EBITDA stands at 7.81, and interest coverage is a slim 1.42. Higher borrowing costs would reduce the spread on new deals and slow AFFO growth.
Federal Realty Owns the Longest Dividend Growth Record in REITs
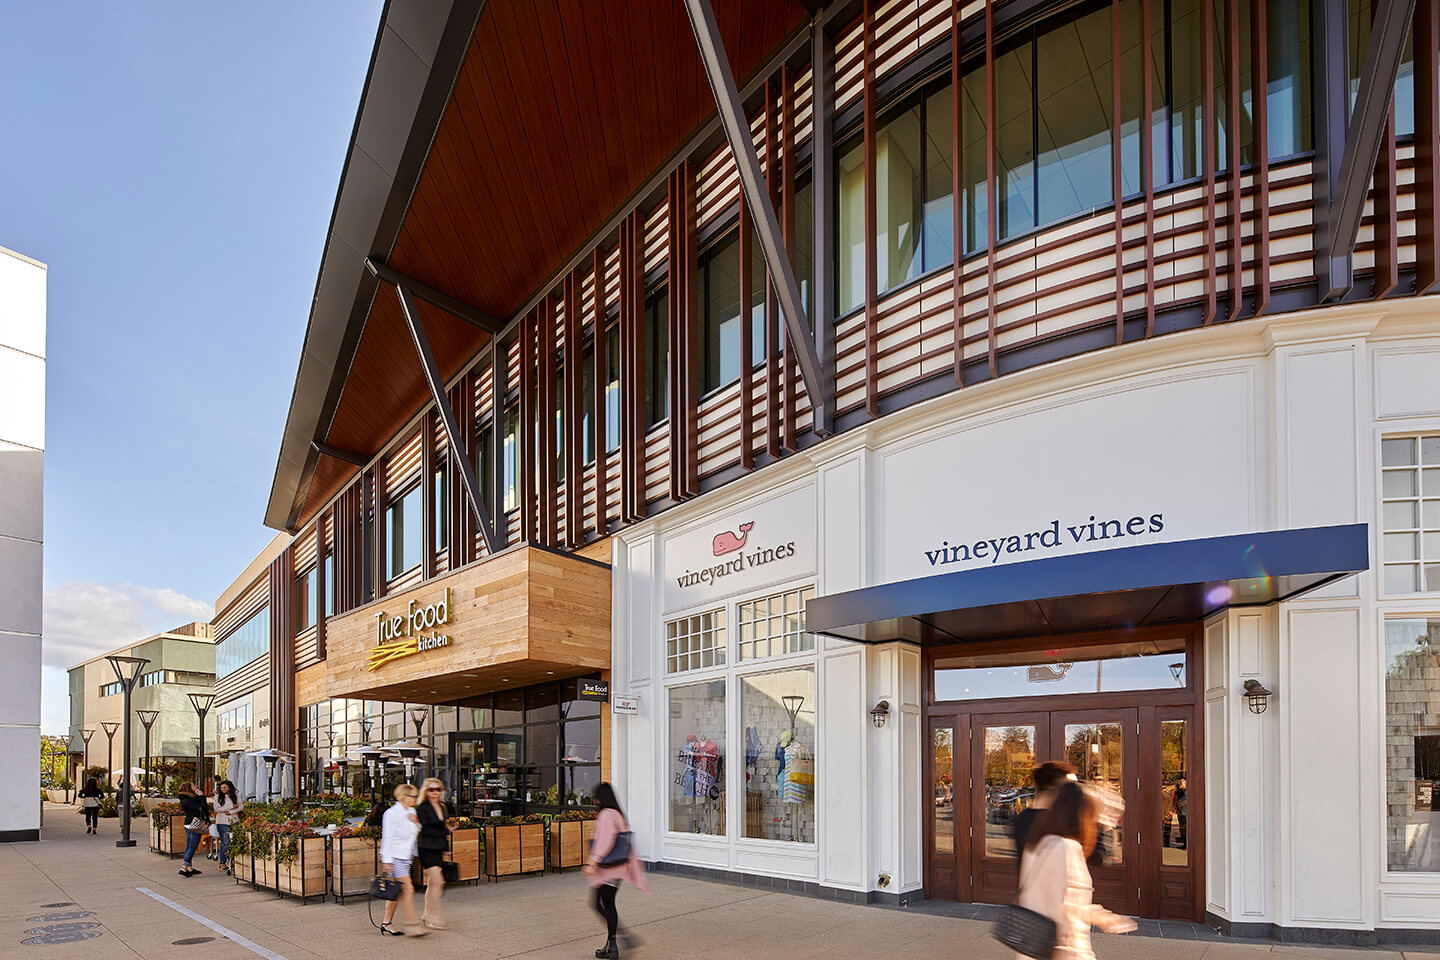
Federal Realty (NYSE:FRT) owns open-air shopping centers and mixed-use destinations, mostly in wealthy coastal markets. Its 102 properties house about 3,700 tenants across 28.8 million commercial square feet, plus roughly 2,700 apartments at places like Santana Row, Pike & Rose and Assembly Row.
The company has raised its dividend for 59 consecutive years, which it calls "the longest record in the REIT sector," and that run passes the 50-year threshold for Dividend King status. The latest increase of 3% lifted the quarterly payout to $1.16, an indicated annual rate of $4.64. The stock yields 4.02% at a recent price of $116.39, after a 20.42% year-to-date gain that has pushed the yield lower.
Dividend safety: For REITs, funds from operations (FFO) is the standard stand-in for free cash flow because depreciation distorts reported earnings. Federal Realty raised its 2026 Core FFO guidance to $7.54 to $7.58 per share, well above the $4.64 annual dividend. Last quarter alone produced $1.87 of Core FFO per share against a $1.16 quarterly payout. Liquidity comes from a revolving credit facility expanded to $1.4 billion with an accordion to $2.0 billion, and management felt confident enough to buy back 869,748 shares for $94.7 million.
Why the raises can continue: Demand for its space keeps rising. The portfolio leased rate reached 96.5%, up 110 basis points from a year earlier, and comparable new leases were signed at 14% higher cash rents. Guidance implies 6.8% to 7.4% Core FFO growth this year, and the $508.0 million purchase of The Summit in Birmingham adds about 120 tenants to the rent roll. Chief executive Donald C. Wood described "strong leasing with materially higher new rents, higher leased occupancy and healthy cash POI growth."
The risk: Retail tenants can fail. The company lists tenant defaults, bankruptcies or inability to re-let space at favorable rents as its first risk, and a wave of store closings would eat into the rent growth that funds each annual increase.
PepsiCo Brings Consumer Staples Steadiness to the Income Mix
PepsiCo (NASDAQ:PEP | PEP Price Prediction) sells snacks and beverages in more than 200 countries and territories, with brands including Pepsi, Lay’s, Doritos and Gatorade. Those are low-cost purchases that hold up when budgets tighten, which gives the dividend a different engine than the two landlords above.
The stock yields 3.97%. The quarterly dividend rose to $1.48 from $1.4225 this year, for an annualized forward payout of $5.92. The dividend record runs from $0.13 per quarter in 1999 to today’s level, with a higher payout in every calendar year from 1999 through 2026, which passes the Aristocrat threshold on its own.
Dividend safety: Free cash flow yield runs at 3.98%, nearly level with the dividend yield. Free cash flow covers the payout, with little room to spare. Management plans $7.9 billion in dividends and $1.0 billion in buybacks this year, targeting free cash flow conversion of at least 80%. Debt is manageable: net debt runs about 2.6 times EBITDA and operating income covers interest expense more than 10 times. The stock trades at about 23 times earnings.
Why the raises can continue: Third-quarter revenue rose 5.6% to $25.27 billion, and adjusted EPS of $2.34 beat the $2.30 consensus estimate. International markets are doing the heavy lifting, with Europe, the Middle East and Africa and Asia Pacific each posting 9% organic revenue growth. Management is also identifying new structural cost cuts to fund growth.
The risk: Earnings growth is slowing while the cash buffer is already thin. PepsiCo lowered its 2026 core EPS growth guidance to 2.5% to 3.5% on rising input costs, and North American snack operating profit fell 12%. Slower profit growth points toward smaller raises ahead.
Three Raise Records That Clear the 2027 COLA
Realty Income delivers the highest yield and a check every month, Federal Realty brings the longest raise record in the REIT sector, and PepsiCo adds consumer staples cash flow that does not depend on rent. Chevron (NYSE:CVX), with its 39th consecutive annual raise on the books, misses this cut at a 3.07% yield. These three suit retirees and near-retirees who want a starting cash yield above the 3.6% COLA plus a payout that has grown every year for decades, and who will hold through rate cycles to collect it.
Contact [email protected] for any questions or corrections.
Lee Jackson has covered Wall Street analysts' equity and debt research and equity strategy daily for 24/7 Wall St. since 2012. His broad, diverse career, including a stint as creative services director at an NBC affiliate in Austin, Texas, gives him unique insight into the financial industry.
Lee Jackson's journey in the financial industry spans more than 30 years, including nearly two decades as an institutional equity salesperson at Bear Stearns, Lehman Brothers, and Morgan Stanley. His career spanned pivotal sell-side Wall Street events, from the dot-com rise and bubble to the Long-Term Capital Management debacle, 9/11, and the Great Recession of 2008. This reflects his resilience and adaptability amid market volatility.
Lee Jackson’s practical financial industry experience, gained through a career at some of the biggest banks and brokerage firms, is complemented by a lifetime of writing across various platforms. This unique combination allows him to shed light on the intricacies of Wall Street in a way only someone with deep insider experience and knowledge can. Moreover, his extensive network across Wall Street continues to provide direct access for him and 24/7 Wall St., a privilege few firms enjoy.
Since 2012, Jackson’s work for 24/7 Wall St. has been featured in Barron’s, Yahoo Finance, MarketWatch, Business Insider, TradingView, Real Money, The Street, Seeking Alpha, Benzinga, and other media outlets. He attended the prestigious Cranbrook Schools in Bloomfield Hills, Michigan, and has a degree in broadcasting from the Specs Howard School of Media Arts.