Nio Is Now Down 36% in 2026: Is NIO a Toxic Stock or Ready to Rally?

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
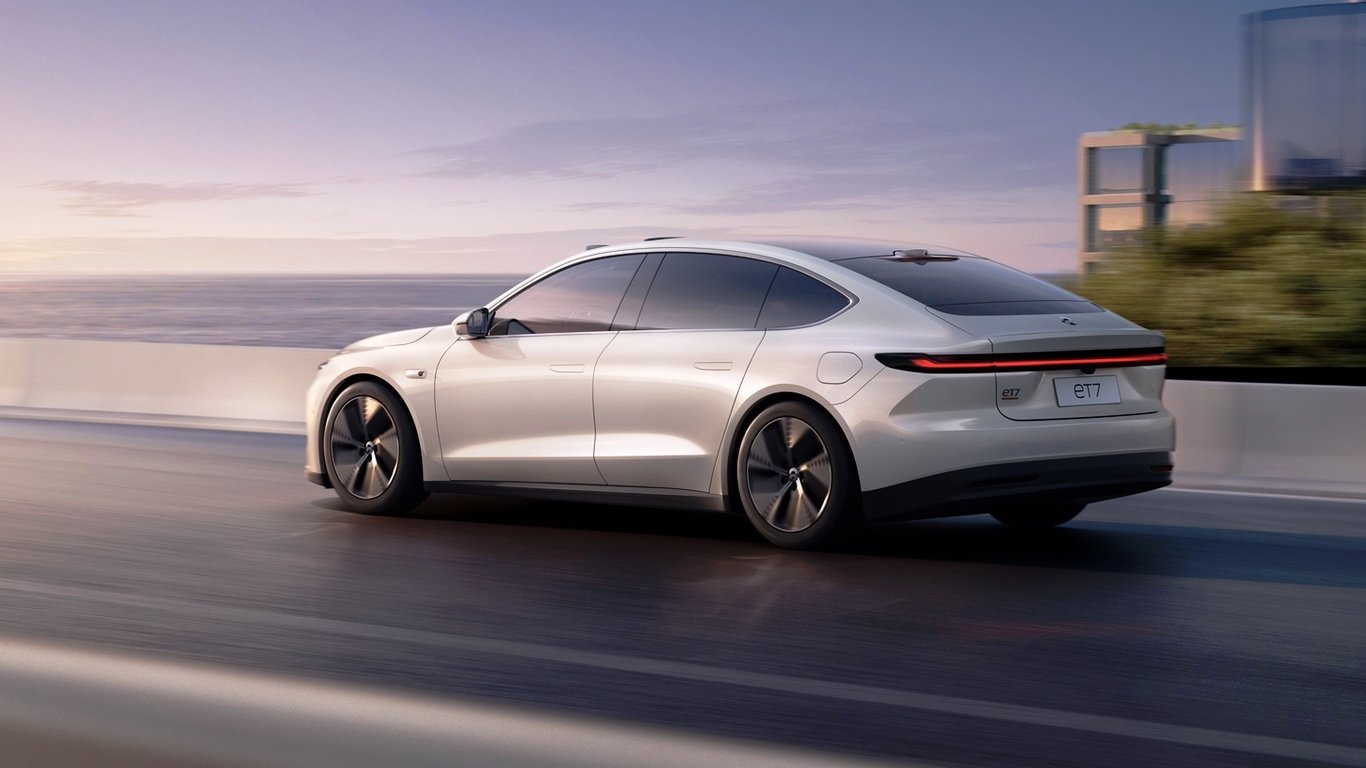
China’s electric vehicle (EV) makers have spent 2026 under heavy pressure, and Nio (NYSE:NIO | NIO Price Prediction) is one of the clearest examples. Nio stock is down 36% year to date (YTD) to $3.25 in the current session. A 5% decline on the day is adding to that drop.
Over the past 52 weeks, Nio has traded between $3.10 and $7. That leaves investors asking whether Nio is a toxic stock or ready to rally, with both sides of that debate backed by real evidence.
Weakness runs across the China EV group this year. XPeng (NYSE:XPEV) stock is at $10.05, down 50% YTD, a deeper drop than Nio’s. Meanwhile, Li Auto (NASDAQ:LI) stock is at $12.48, down 26% YTD; thus, Nio stock has done worse than at least one close rival.
Nio’s Q2 Report Handed the Bulls Real Progress
Nio released its Q2 2026 results on September 1, and the numbers showed a sharp turn. Revenue at Nio reached RMB 32.1 billion, up 69.1% year over year (YoY). Vehicle margin at Nio rose to 18.5% from 10.3% in Q2 2025.
Nio posted an adjusted net profit excluding share-based compensation of RMB 26.1 million, along with positive operating cash flow and free cash flow. Its cash, restricted cash, short-term investments and long-term time deposits stood at RMB 56.7 billion at quarter’s end.
In Q2, Nio delivered 107,658 vehicles, up 49.4% YoY. CEO William Li has set a Q4 2026 target of over 40,000 units a month on average and expects Nio’s annual volume growth in the 40% to 50% range over the mid to long term. “We are confident in achieving our operating targets,” William Li stated.
How Nio’s Business Model Differs From XPeng and Li Auto
Nio sells premium smart EVs through its Nio, ONVO and Firefly brands, and it pairs them with a battery-as-a-service subscription and a network of battery swap stations. That swap network gives Nio a charging approach its two rivals don’t share.
XPeng calls itself a physical artificial intelligence (AI) company. It provides technical research and development (R&D) services for a major car maker alongside robotaxi and humanoid robot projects. Li Auto built its name on extended-range EVs for families and now balances those with battery-electric models.
Is Nio a Toxic Stock or Ready to Rally?
The bulls see a company whose margins and cash flow are finally moving the right way. Nio runs 4,123 power swap stations worldwide, an asset that sets it apart. Most analysts lean bullish: five rate Nio a Strong Buy and 11 rate it a Buy, against six Holds and one Strong Sell. Nio’s average analyst price target is $6.09.


The bears can point to cost pressure at Nio first. CFO Stanley Qu revealed Nio’s material costs rose around RMB 14,000 per car in Q2 versus late Q4 2025, with another RMB 2,000 to RMB 3,000 per car expected in the second half. On top of that, Nio still recorded a GAAP net loss of RMB 0.5 billion in Q2. October brought another soft spot, as Nio’s deliveries for the month, reported on November 1, fell short of the monthly pace William Li targeted for Q4.
Earlier filings from Nio included going-concern language and showed current liabilities exceeding current assets. Price competition in China’s EV market remains intense, and ONVO’s momentum at Nio has been more moderate than the other brands. For a U.S.-listed American depositary receipt, Nio’s variable interest entity structure adds risk tied to U.S.-China tensions, and long-term shareholders have already absorbed heavy losses in Nio stock.
What Nio Has to Prove Heading Into Q3 Results
Nio has Q3 2026 results coming, though the company hasn’t confirmed a report date. Investors will watch whether Q3 deliveries land inside the company’s guidance and whether November and December volumes reach William Li’s monthly target. Vehicle margin under rising material costs and the new models Nio plans for 2027 are other items to watch for.
A clean quarter could ease the concerns weighing on Nio, while another shortfall could keep pressure on the stock. For investors, caution could make sense while waiting to see Nio’s upcoming delivery numbers.
Contact [email protected] for any questions or corrections.
David Moadel is financial writer specializing in stocks, ETFs, options, precious metals, and Bitcoin. David has written well over 1,000 articles for leading online publications, helping investors understand markets, income strategies, and risk. His work has appeared in 24/7 Wall St., The Motley Fool, InvestorPlace, U.S. News & World Report, TipRanks, ValueWalk, Benzinga, Market Realist, MarketScreener, TalkMarkets, Finmasters, and others. With a master’s degree in education, David has taught at the elementary, high school, and college levels. That teaching background shapes his writing style: clear, educational, and practical. David has also built a loyal social-media audience by providing trustworthy financial content on YouTube, X/Twitter, and StockTwits.