XPeng Rallies 5% on Q3 Results and Strong Q4 Delivery Outlook; Nio Falls 4%, Tesla Slides 3%

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
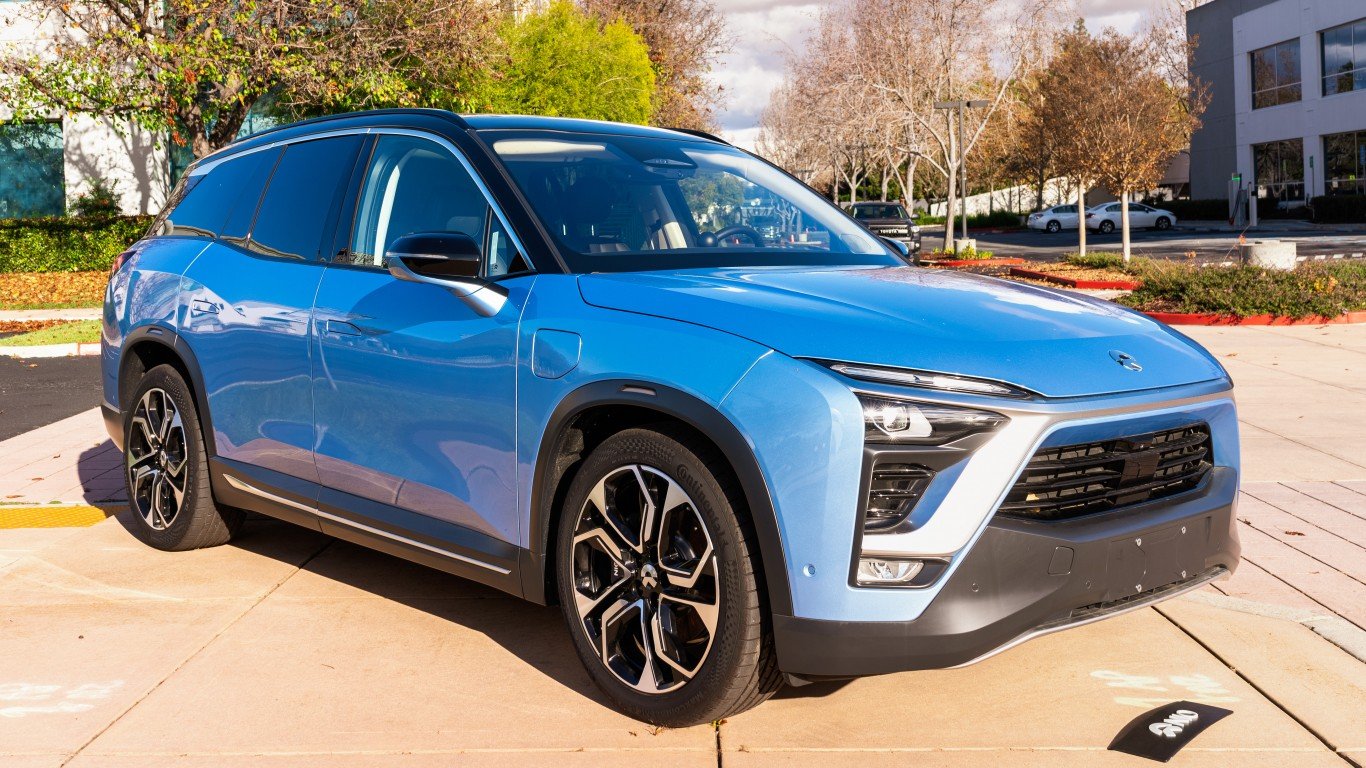
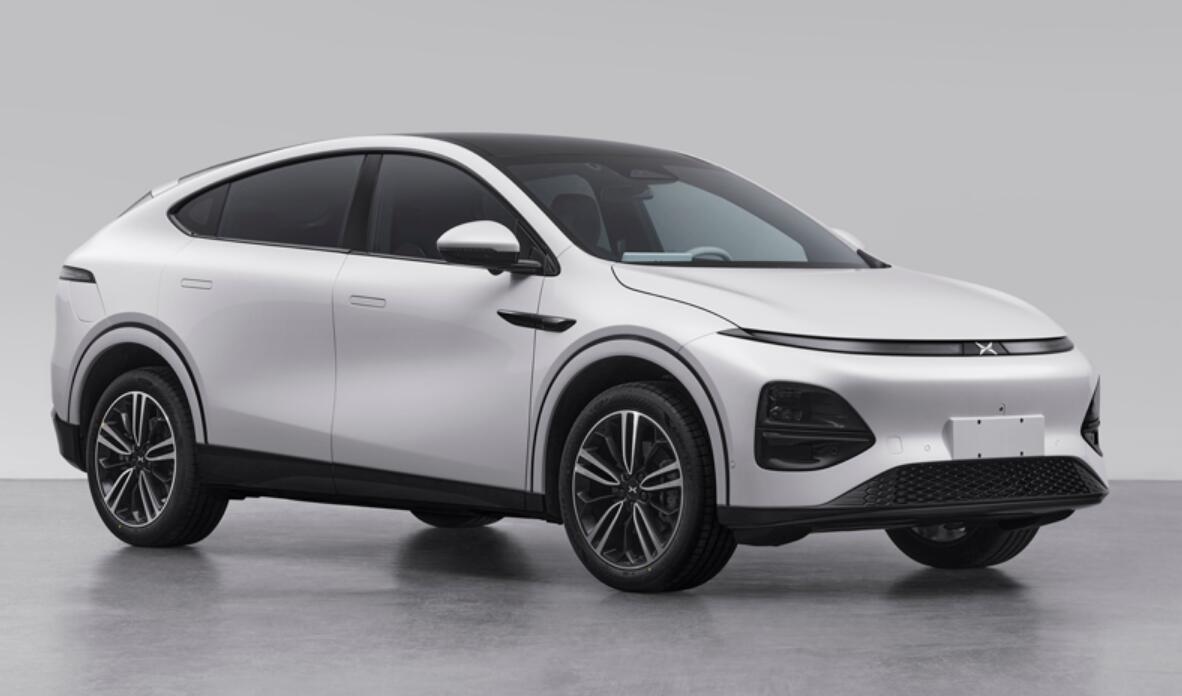
Fresh company news is lifting XPeng (NYSE:XPEV | XPEV Price Prediction) while most electric vehicle (EV) stocks retreat. XPeng stock is at $9.88 in afternoon trading, up 5%. XPeng stock remains down 51% year to date (YTD). Even after that gain, the drop is a sign of how beaten down the shares were heading into the report.
On November 16[1], XPeng reported its Q3 2026 results and guided to record Q4 2026 deliveries. Growth and technology stocks are under pressure, with the NASDAQ 100 down 2%. That context is weighing on Nio (NYSE:NIO), a fellow Chinese EV maker. Shares of U.S. rival Tesla (NASDAQ:TSLA) are falling, too.
XPeng’s Q3 Report Points to Record Deliveries
Fourth-quarter guidance from XPeng calls for 169,000 to 174,000 vehicles, a rise of at least 45% from a year earlier. Third-quarter revenue at XPeng grew 19% to RMB 24.28 billion[1], helped by higher deliveries and a richer product mix. XPeng delivered 118,390 vehicles[1] in Q3, up 15% from Q2 2026.
On the call, CEO He Xiaopeng said, “We expect our monthly sales volume to surpass 60,000 for the first time in November.”[1] Management added that XPeng’s October deliveries topped 50,000 units for the first time, while overseas sales hit a record 13,000 units. Overseas growth is central to the pitch, with the CEO calling the international business “XPeng’s strongest driver of growth and profitability.”[1]
Vehicle margin at XPeng improved to 13.1%[1] from 12.1% in Q2, which management credited to a more favorable mix that includes the XPeng GX. Gross margin at the company slipped to 18.9%[1] from 20.7% over the same stretch. The company’s net loss grew to RMB 0.87 billion[1] from RMB 0.38 billion a year earlier, so the business still isn’t profitable.

Reaction to XPeng’s report splits along familiar lines. Some traders are encouraged by record deliveries, revenue growth and improving vehicle margins. Others remain cautious about ongoing losses and whether higher volume can turn into lasting profitability after the stock’s long decline.
Why Nio and Tesla Are Moving the Other Way
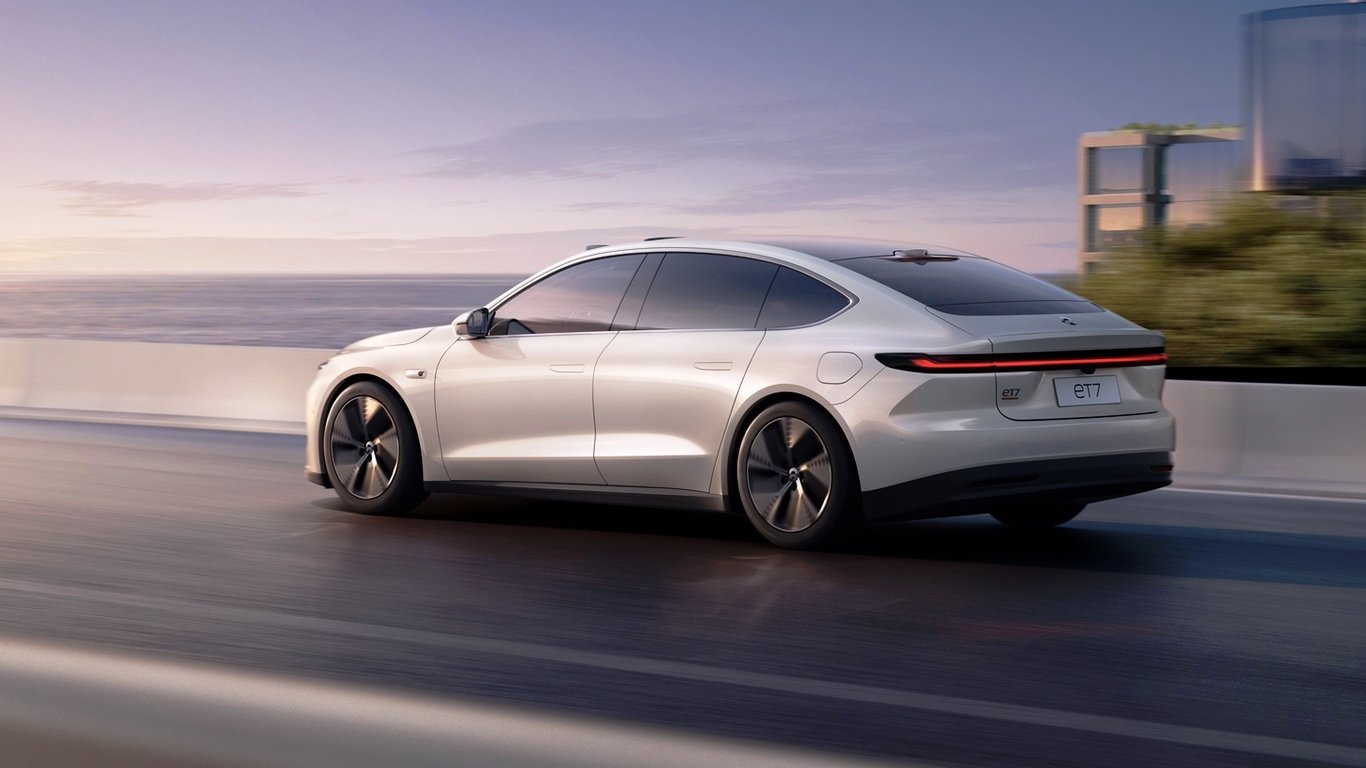
Nio stock is at $2.78, down 4%. A rough stretch has left the shares down 18% over the past five trading sessions. Margin pressure has been a theme for Nio since its September 1[1] call, when management noted rising costs for memory chips, batteries and other bulk materials. The broader risk-off mood in growth stocks is adding to that pressure.
Tesla stock is at $378.83, down 3%. Consumer discretionary stocks are lower as a group, with that sector down 1%, and Tesla is moving with them. XPeng stands apart because it has fresh, company-specific results and guidance to point to.
How XPeng’s Business Differs From Nio and Tesla
XPeng is presenting itself as a Physical AI company, spanning smart EVs, robotaxis and humanoid robots through its Dogotix robotics unit. A technology partnership with Volkswagen brings in high-margin research and development service revenue, and the company’s XPeng AI Engineering arm offers its chips, foundation models and autonomy software to global partners. In Guangzhou, the company’s robotaxi business has approval for Level 4 (L4) demonstration operations.
Nio runs a premium multi-brand strategy, pairing its namesake brand with ONVO and FIREFLY, and backs it with a battery-swap network. Tesla operates as a global platform that combines EVs with energy storage, Full Self-Driving (FSD) software, robotaxis and the Optimus humanoid robot. Compared with both, XPeng leans harder on overseas expansion and technology licensing as its path to scale.
XPeng’s Turnaround Test Comes Down to Margins
One open question for XPeng is whether record volume marks the start of a turnaround or a relief bounce after a deep drawdown. Management said Q4 gross margin may decline sequentially as the lower-priced Mona L05 takes a larger share of volume. The next test for XPeng is whether scale, a richer overseas mix and lower expense ratios can lift operating results in 2027[1], as management expects.
The bulls on XPeng can point to increasing deliveries, a record overseas business and a humanoid robot scheduled for commercial launch in Q2 2027[1]. The bears, by contrast, focus on a wider net loss, a gross margin that slipped in Q3 and a stock still deep in the red this year. CEO He Xiaopeng framed the company’s near-term goal as reaching “positive cash flow and profitability for our automotive business.”[1]
XPeng’s Q4 margin figures could offer the clearest read yet on that debate. A cautious investment approach could make sense until XPeng’s path to automotive profitability resolves.
Contact [email protected] for any questions or corrections.
David Moadel is financial writer specializing in stocks, ETFs, options, precious metals, and Bitcoin. David has written well over 1,000 articles for leading online publications, helping investors understand markets, income strategies, and risk. His work has appeared in 24/7 Wall St., The Motley Fool, InvestorPlace, U.S. News & World Report, TipRanks, ValueWalk, Benzinga, Market Realist, MarketScreener, TalkMarkets, Finmasters, and others. With a master’s degree in education, David has taught at the elementary, high school, and college levels. That teaching background shapes his writing style: clear, educational, and practical. David has also built a loyal social-media audience by providing trustworthy financial content on YouTube, X/Twitter, and StockTwits.