Nio Is Down 45% This Year. What Will It Take to Get NIO Stock Back to $5?

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
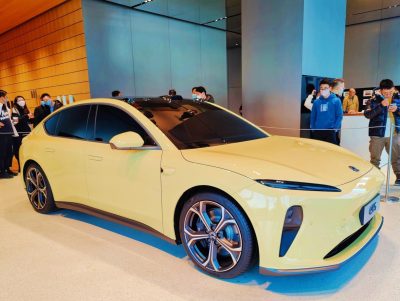
Chinese electric vehicle (EV) maker Nio (NYSE:NIO | NIO Price Prediction) has tightened its operations this year, yet it has received little credit from the market. Nio stock is at $2.82, up 4% in morning trading. That bounce still leaves Nio stock down 45% year to date (YTD), measured from its $5.10 close at the end of 2025.
Getting back to $5 depends on what Nio shows investors in its next quarterly report. The company announced it will report unaudited Q3 2026 results on December 1, with its earnings call set for 7:00 a.m. ET.

Nio Slides Alongside Its Chinese EV Rivals
Nio’s decline is part of a broader selloff in Chinese EV stocks. XPeng (NYSE:XPEV) stock is down 52% YTD to $9.66, a steeper drop than Nio’s. Meanwhile, Li Auto (NASDAQ:LI) stock is down 32% YTD to $11.57 while Tesla (NASDAQ:TSLA) shares have declined 16% in 2026 so far to $381.13.
That spread suggests Nio’s slide reflects pressure on the whole sector as much as worries specific to the company, as selling across Chinese automakers has weighed on the group and Nio sits between its two closest rivals. Even Nio’s operating gains haven’t protected the stock from that pressure.
Three Questions Nio’s Q3 Report Must Answer
Deliveries come first for Nio. On the September 1[1] call, Founder and CEO William Li reported Q2 2026 deliveries of 107,658 vehicles. William Li guided Q3 deliveries of 108,000[1] to 111,000 vehicles and set a Q4 2026 target of averaging over 40,000 vehicles a month. Any sign of softening demand in the December report could put that goal in doubt.
Margins are the second test for Nio. Chief Financial Officer Stanley Qu said Nio’s vehicle margin fell to 18.5%[1] in Q2 from 18.8% in Q1 2026. Memory chips, batteries and other materials grew more expensive. Qu stated, “In Q3 and Q4, we hope to stabilize vehicle gross margin at the same level as in Q2.”[1]
Cash generation is another crucial piece of Nio’s recovery case. According to CEO William Li, the company generated adjusted operating profit plus positive operating cash flow and free cash flow in Q2. That lifted its cash reserves to RMB 56.7 billion[1]. Repeating that performance in Q3 would fell concerns about Nio’s balance sheet.
How Nio’s Model Differs From XPeng and Li Auto
Nio sells premium battery-electric vehicles under three brands: its namesake line, Onvo and Firefly. The company also runs a battery-swapping network that lets drivers exchange a depleted pack for a charged one in minutes. William Li spoke on the same call. He said, “We believe the premium positioning of our brands and competitiveness across all three brands will be a long-term foundation for our competitiveness going forward.”[1]
XPeng competes more in mass-market price bands and leans on driver-assistance software as its selling point, while Li Auto built its following with extended-range family SUVs that pair a battery with a gasoline generator. Swapping gives Nio a distinctive draw for premium buyers, though the stations require heavy capital spending.
Bull and Bear Cases for a Nio Recovery
Bulls can point to Nio’s rising deliveries, steady margins and cash flow that’s now funding the business. Reaching the Q4 target could show that Nio’s three-brand strategy works at scale. Each of Nio’s last three reports also exceeded analysts’ earnings-per-share estimates.
On the other side, the bears have a longer list. Nio’s most recent annual results carried going-concern language and showed current liabilities above current assets at the end of 2025[2]. Heavy losses add pressure, including the company’s full-year 2025 net loss of RMB 14.9 billion[2]. Rising costs pose another threat, since Qu expects material costs to climb by another RMB 2,000 to RMB 3,000[1] per car in the second half.
What Nio Has to Prove Before It Reclaims $5
Nio’s next test is whether Q3 deliveries land inside William Li’s guidance and the monthly pace builds toward his Q4 target. Stable margins and another quarter of positive free cash flow would strengthen the recovery case.

A shortfall on either front could extend the slide in Nio stock. Nio’s December 1 report could show whether the turnaround is on track.
Contact [email protected] for any questions or corrections.
David Moadel is financial writer specializing in stocks, ETFs, options, precious metals, and Bitcoin. David has written well over 1,000 articles for leading online publications, helping investors understand markets, income strategies, and risk. His work has appeared in 24/7 Wall St., The Motley Fool, InvestorPlace, U.S. News & World Report, TipRanks, ValueWalk, Benzinga, Market Realist, MarketScreener, TalkMarkets, Finmasters, and others. With a master’s degree in education, David has taught at the elementary, high school, and college levels. That teaching background shapes his writing style: clear, educational, and practical. David has also built a loyal social-media audience by providing trustworthy financial content on YouTube, X/Twitter, and StockTwits.