Prediction: Nvidia’s Success Could Create a Bigger Opportunity for This Chip Stock

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
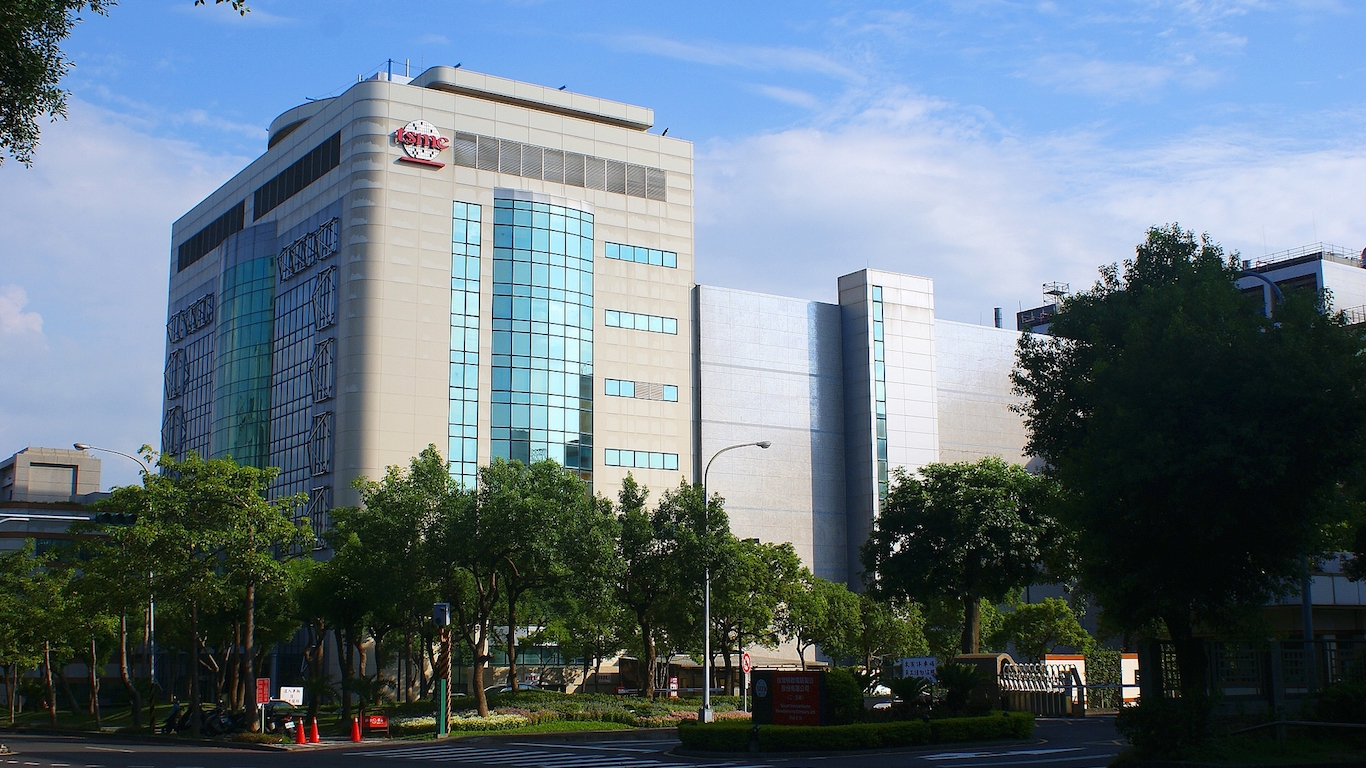
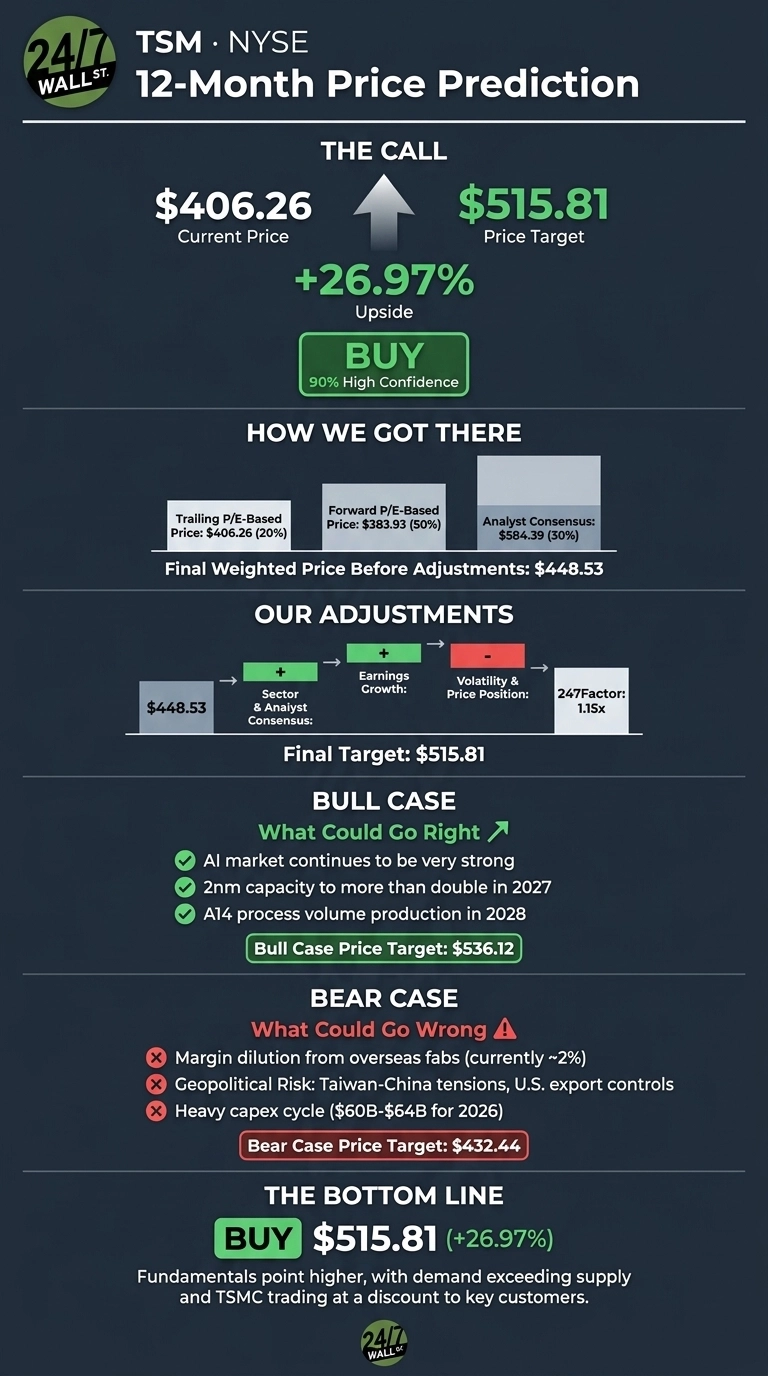
NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) keeps posting record quarters, and a large share of that growth depends on one manufacturer. Based on our proprietary model, the 24/7 Wall St. price target for Taiwan Semiconductor Manufacturing (NYSE:TSM) is $515.81. The stock trades at $406.26, so the target means 26.97% upside. Our model rates TSMC a buy with high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $406.26 |
| 24/7 Wall St. Price Target | $515.81 |
| Upside/Downside | 26.97% |
| Recommendation | BUY |
| Confidence Level | 90% |

The share price has fallen over the past month, but the business has kept growing faster. Management now expects 2026 revenue to grow about 44% in U.S. dollar terms, and demand still exceeds supply.
A Sharp Monthly Pullback Follows Another Earnings Beat
TSMC shares fell 7.19% over the past week and 14.24% over the past month. They are still up 34.45% year to date. The stock sits about 16.7% below its 52-week high of $487.47 and roughly 53.7% above its low of $264.34.
On October 15, TSMC reported Q3 EPS of $4.60 per ADR. Consensus was $4.46, so the company beat estimates for the third quarter in a row. Revenue of $46.7 billion came in above the top of guidance. Gross margin slipped 1.3 percentage points to 66.4% because the new 2nm process costs more while it ramps up.
Why Bulls See $536 and Beyond
Nvidia posted quarterly revenue of $96.22 billion, up 105.85%. It also names TSMC as a manufacturing partner. CFO Colette Kress called Nvidia’s outlook for roughly 70% fiscal 2028 growth “a supply-constrained outlook.” In other words, Nvidia expects to sell everything its suppliers can make.
TSMC Chairman and CEO C.C. Wei said, “Demand is still far above our capability to supply today.” TSMC expects its 2nm capacity to more than double in 2027, and the next-generation A14 process starts volume production in 2028.
Analysts are lopsided in TSMC’s favor: 6 strong buy and 14 buy ratings against 1 hold. Our bull scenario reaches $536.12.

Margin Dilution and Geopolitics Top the Risk List
Overseas fabs currently lower gross margin by about 2%. Management expects that drag to widen to 3%–4% as more U.S. fabs come online. Capex is set at $60 billion to $64 billion for 2026.
Bulls can point out that margins usually dip during a new node’s ramp, with revenue growth expected to outpace capex growth. Taiwan-China tensions and U.S. export controls are still risks no model can fully price. The bear case is $432.44.

TSMC Trades at a Discount to Its Biggest Customers
Nvidia is the obvious comparison because its growth creates TSMC’s demand. Nvidia earns a 75% non-GAAP gross margin and trades at a trailing P/E of about 42.
Advanced Micro Devices (NASDAQ:AMD) competes with Nvidia in AI GPUs and also relies on outside foundries. AMD grew Q3 revenue 44.68% but trades near 182 times trailing earnings.
| Company | P/E | Gross Margin |
|---|---|---|
| TSMC | 18x forward | 66.4% |
| Nvidia | 42x trailing | 75.0% |
| AMD | 182x trailing | ~55% (Q4 guide) |
The P/E figures in the table use different bases (forward for TSMC, trailing for the peers). Even so, TSMC’s multiple sits far below both. Measured against these peers, our 24/7 Wall St. price target looks conservative.
Pullback Leaves Room for a 27% Gain
Our 24/7 Wall St. price target of $515.81 comes with a buy rating and 90% confidence. What tips the balance is that TSMC trades at 18 times forward earnings while its largest customers say demand is exceeding supply.
I would grow more constructive if gross margin holds within the 65% to 67% Q4 guide. I would turn cautious if overseas dilution widens faster than planned or tensions in the Taiwan Strait escalate. For now, the fundamentals point higher than the stock.
Taiwan Semiconductor Price Prediction 2026-2030
Over a longer horizon, here is where our model projects TSMC could trade if current growth and market conditions hold.
| Year | 24/7 Wall St. Price Target |
|---|---|
| 2026 | $408.21 |
| 2027 | $524.85 |
| 2028 | $618.77 |
| 2029 | $699.46 |
| 2030 | $766.85 |
The projections depend on TSMC keeping up its performance on 2nm and A14. A slowdown in AI spending or a geopolitical shock involving Taiwan could move the stock sharply in either direction.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.