A Major Catalyst Could Send Amazon Stock to New Highs

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
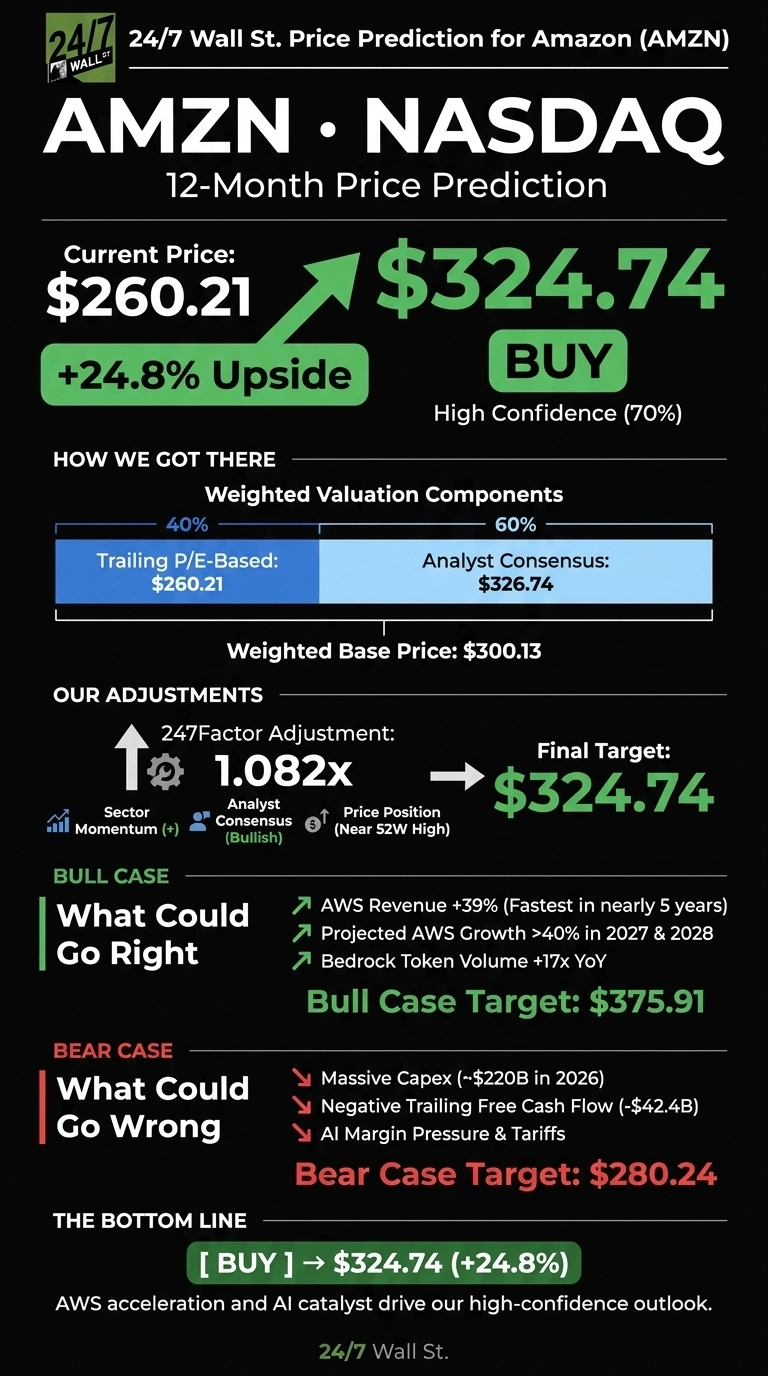
The 24/7 Wall St. price target for Amazon (NASDAQ:AMZN | AMZN Price Prediction) is $324.74. The stock has 24.8% upside from the close of $260.21, and our model rates it a buy with high confidence.
| Metric | Value |
|---|---|
| Current Price | $260.21 |
| Price Target from 24/7 Wall St. | $324.74 |
| Upside/Downside | 24.8% |
| Model Rating | BUY |
| Confidence Level | 70% |

AWS is the main driver. Revenue grew 39% in the third quarter, the fastest rate in nearly five years.
Management expects growth north of 40% in each of 2027 and 2028, and the backlog stands at $578 billion. Our 70% confidence reflects near-unanimous analyst support, weighed against a spending cycle that has pushed free cash flow negative.
AWS Acceleration Sparks an 8% Weekly Rally
Shares traded near $263.66. They are up 8.15% over the past week, 2.88% over the past month and 14.23% year to date. The price sits 8.2% below the 52-week high of $287.20 and 34.5% above the low of $196.
Third-quarter revenue rose 12.1% to $201.94 billion, just missing the $202.20 billion estimate. GAAP EPS of $1.89 also missed the $1.96 estimate, although last year’s quarter included a $9.5 billion pre-tax gain on Amazon’s Anthropic stake. Operating income rose 61.2% to $28.08 billion, and the 13.9% operating margin was the highest in the company’s history.
Why Bulls See $375 Within Reach
The bull case reaches $375.91. Bedrock token volume grew nearly 17x year over year. Revenue commitments for Trainium and Graviton chips rose more than 20x.
Management expects advertising growth to return to the high teens in Q4, and grocery is growing about three times faster than the rest of the store. Amazon CEO Andy Jassy said, “We believe that AWS can grow north of 40% in each of 2027 and 2028 and be a trillion-dollar revenue business in the next five to 10 years.”

Amazon’s $220 Billion Capex Bill Is the Risk to Watch
The bear case sits at $280.24. Third-quarter capex rose 120% to $77.26 billion, and 2026 spending should reach about $220 billion. Trailing free cash flow is about -$42.4 billion. AI services carry lower margins than core AWS, and memory costs and tariffs add pressure.
All that spending flows to the power, cooling, and networking suppliers behind the data centers, the group we profiled in a free report on seven AI infrastructure names that aren’t chipmakers. Meanwhile, operating cash flow rose 19.4% to $42.42 billion, and AWS posted a 38.7% operating margin, which suggests the spending is already paying off.
How Amazon Compares to Microsoft and Alphabet
AWS’s most direct cloud rival is Microsoft (NASDAQ:MSFT). Azure grew 48%, and commercial remaining performance obligations reached $677 billion. Microsoft trades at about 30x trailing earnings, compared with Amazon’s 36x. That premium is easier to accept given that AWS has sped up for six straight quarters.
Alphabet (NASDAQ:GOOGL) carries the same AI capex risk. Google Cloud grew 103%, but Alphabet’s quarterly free cash flow was -$9,065 million. Its 13x P/E is flattered by a $99 billion equity gain in Q2.
| Company | TTM P/E | Latest Cloud Growth |
|---|---|---|
| Amazon | 36 | 39% |
| Microsoft | 30 | 48% |
| Alphabet | 13 | 103% |
All three companies are posting fast cloud growth while spending heavily on capex. Measured against them, our target looks reasonable rather than aggressive.
AWS Momentum Keeps Our $324.74 Target Intact
24/7 Wall St. keeps its price target at $324.74, with a model rating of buy at 70% confidence. AWS acceleration is what tips the scale.
The thesis gets stronger if AWS growth crosses 40% and Q4 operating income lands near the top of the $28.5 billion to $33.5 billion guidance range. It weakens if capex keeps rising while AWS margins contract. The evidence tips toward the bulls.
These targets extend our base-case model and assume current growth trends hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $263.38 |
| 2027 | $324.74 |
| 2028 | $368.15 |
| 2029 | $413.41 |
| 2030 | $472.89 |
The projections rest on Amazon continuing to execute its current strategy. Faster-than-expected Trainium adoption could send results well above these figures, while a decline in AI spending could leave them well below.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.