Prediction: Palantir Shares Could Deliver Outsized Returns Over the Next 5 Years

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

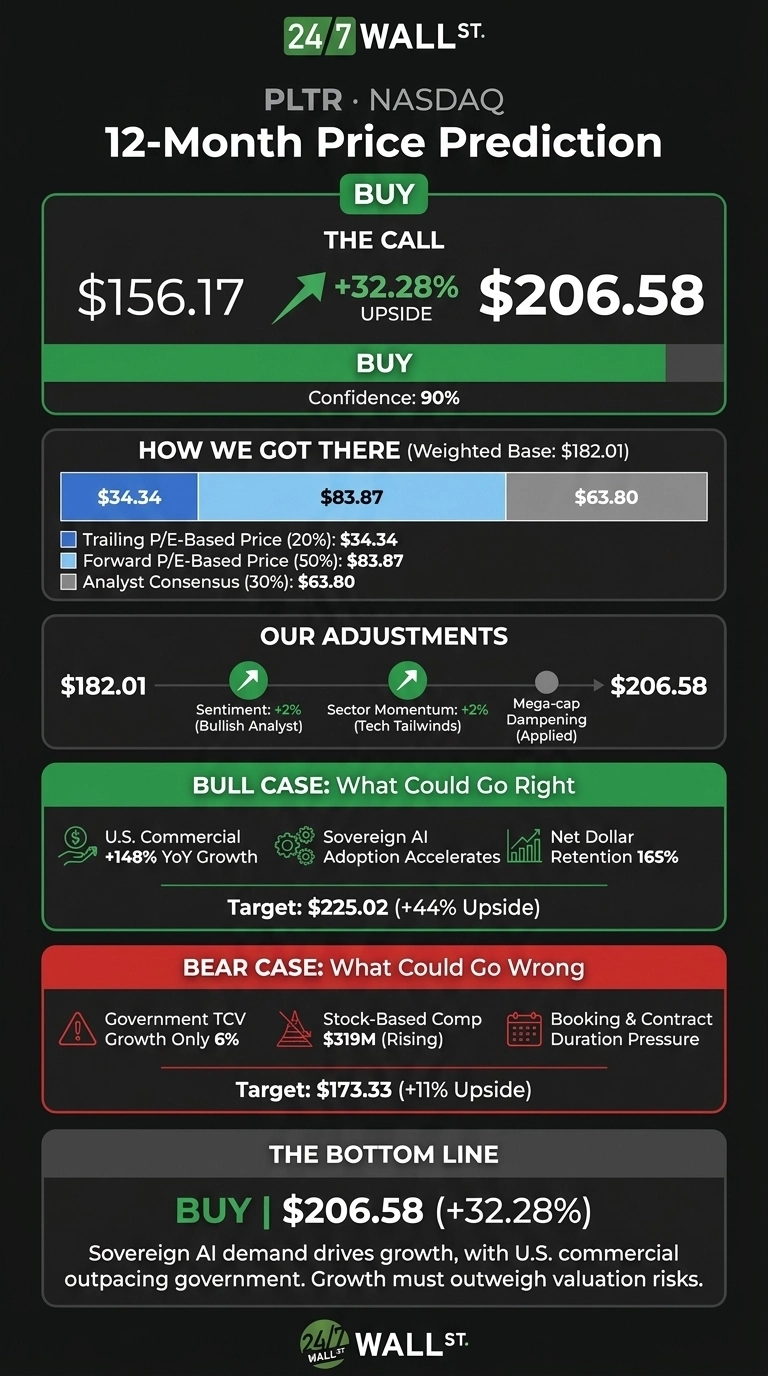
Palantir Technologies (NASDAQ:PLTR | PLTR Price Prediction) just posted the strongest quarter in its history, and the stock fell anyway. Shares traded at $156.17 noon, down 9.04% on the session. The 24/7 Wall St. price target sits at $206.58. Against the prior close of $171.70, that implies a 20.31% gain. From today’s intraday price, the upside extends to 32.28%.
| Metric | Value |
|---|---|
| Current Price | $156.17 |
| Price Target from 24/7 Wall St. | $206.58 |
| Upside | 32.28% |
| Model Rating | BUY |
| Confidence Level | 90% |

A 90% confidence reading is high for our model. Over five years, our base case reaches $302.07, a 75.93% total return (11.96% annualized) from the $171.70 starting point. Measured from today’s price, that return becomes 93.42%.

A Record Quarter Met a Brutal Week
Palantir has fallen 20.65% in a week, 17.54% in a month and 12.14% year to date. It sits 26.66% below its 52-week high of $212.94, yet it is still up 500.65% over five years.
Third-quarter revenue rose 95.87% to $2.313 billion, ahead of the $2.181 billion consensus. Adjusted EPS of $0.44 beat the $0.4072 estimate, making it an 11-quarter beat run.
U.S. commercial revenue of $984 million passed U.S. government revenue for the first time, and full-year guidance rose to $8.530 billion to $8.534 billion. An Axios headline, “Palantir loses its wow factor,” sums up the mood: at this valuation, beats alone no longer lift the stock.
Why Bulls See $225 and Beyond
Sovereign AI is the engine. Net dollar retention reached 165%, and pilot programs are turning into large contracts quickly. One industrial materials customer turned a $3 million pilot into a $29 million ACV deal. CEO Alex Karp told analysts, “At this point in the U.S., the market for us is insatiable.”
Full-year adjusted free cash flow guidance of $4.8 billion to $5.0 billion backs that up with cash. Wall Street’s consensus target is $216, with 22 Buy or Strong Buy ratings against 2 Sells. Our one-year bull case is $225.02, and our five-year bull case is $330.37.

Bookings and Dilution Are the Pressure Points
Palantir’s trailing earnings multiple is 243. Government TCV grew just 6%, stock-based compensation climbed to $318.9 million from $172.3 million, and receivables rose to $1.883 billion.
Management said early Sovereign AI contracts were shorter than usual and expects their size and duration to grow. Total remaining deal value rose 55% to $13.4 billion. Our bear cases are $173.33 over one year and $199.39 over five.
Palantir Commands a Steep Premium Over Snowflake and Salesforce
Snowflake (NYSE:SNOW) competes directly for enterprise data and AI workloads. Revenue grew 35.09%, but its operating margin is still negative. Palantir grows faster and makes real profits, which helps justify its higher multiple.
Salesforce (NYSE:CRM) is the value contrast in agentic AI. Its Agentforce ARR topped $1.5 billion, but revenue grew only 10.83% at a P/E of 25.
| Company | P/FCF | Revenue Growth (YoY) | Operating Margin |
|---|---|---|---|
| Palantir | 188x | 95.87% | 31.59% |
| Snowflake | 92x | 35.09% | -30.64% |
| Salesforce | 13x | 10.83% | 21.47% |
Compared with these peers, our target looks reasonable but leaves little room for the multiple to expand. Revenue growth has to do the heavy lifting.
Growth Has to Keep Outrunning the Multiple
The 24/7 Wall St. price target of $206.58 carries a buy rating at 90% confidence. U.S. commercial growth of 148% is what tips the scale.
The bull case strengthens if U.S. commercial revenue keeps growing faster than 100% and contract durations extend. The bear case gains weight if bookings stall while dilution keeps rising. With the stock down 20% in a week, the gap to the price target has extends.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 (12-month) | $206.58 |
| 2027 | $209.88 |
| 2028 | $239.32 |
| 2029 | $268.20 |
| 2030 | $291.06 |
The 2027 through 2030 figures are base-case November estimates. Palantir needs to keep executing on Sovereign AI for these projections to hold.
Longer contract durations could drive results higher, while a sustained slowdown in bookings might drag them down. For the broader pattern of what early-stage tech compounders look like before their biggest runs, we listed the signals in a free playbook here.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.