SK Hynix Crumbled 25% Over The Last Month: 200% Returns Are a Distinct Possibility According to This Wall Street Firm

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
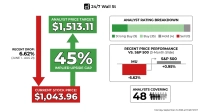
SK hynix (NASDAQ:SKHY) currently trades at $129.66, while the consensus price target sits at $260.64. The spread points to upside of roughly 101%.
SK hynix is the leading supplier of high-bandwidth memory (HBM), the stacked DRAM that feeds AI accelerators in data centers. Its US-listed shares give American investors direct access to the company most tied to the AI memory expansion (we covered seven other companies driving that same expansion, from power to cooling to networking, in a free report here).
One firm sees far more upside than the average. Rosenblatt Securities holds a Street-high target of $400.00, implying about 208% upside. Consensus upside is already substantial.
A Record Quarter Could Not Stop a Brutal Chip Selloff
A Nasdaq selloff that battered Asian chip stocks, including SK hynix and Samsung, did the most damage. The shares have fallen 23.29% over the past month and 14.01% in the past week alone. Commentary also noted competition from China’s CXMT weighing on prices.
Third-quarter revenue and margins expanded sharply. Revenue reached KRW 104.6 trillion, up 328% year-on-year, with an operating margin of 80%. Below the operating line, though, a foreign exchange loss of KRW 11.6 trillion and investment valuation losses of KRW 22.9 trillion pushed pre-tax profit down 58.7% quarter over quarter. Some customers also adjusted HBM specifications, which management framed as proof that “demand is indeed overwhelming supply.”
Rosenblatt Sees a Multiyear Supercycle Priced Like a Blip
Analyst opinion remains overwhelmingly positive:
- Strong Buy: 5
- Buy: 8
- Hold: 1
- Sell: 0
Estimates are rising into the selloff. The fiscal 2027 EPS consensus rose to 42.2991 from 33.6243 90 days ago, with 3 upward revisions and zero downward revisions over 30 days.
Rosenblatt analyst Kevin Cassidy raised his 12-month target from $320.00 after the Q3 report. The case depends on volume lock-in: long-term agreements cover more than 50% of total capacity for 2027 and 2028, and management says DRAM and HBM volumes through 2029 are “effectively sold out.”
The second factor is cycle duration. Rosenblatt argues the market prices SK hynix as a short commodity cycle, and the stock trades at a forward P/E of about 3x. Its target models a re-rating to roughly 9x NTM earnings. Management expects supply tightness to persist “through 2030” and called the shares “undervalued.” Near-term catalysts include HBM4 overtaking HBM3E in Q4 and roughly KRW 100 trillion in 2026 shareholder returns.
Every Memory Stock Got Hit, and SK hynix Fell Least
Every stock in the peer group sold off together, and SK hynix held up better than its US rivals.
Micron Technology (NASDAQ:MU | MU Price Prediction) trades at $725.11 after a 29.52% monthly drop. Its $1561.91 average target implies about 115% upside. Of 49 analysts, 45 rate it Buy or Strong Buy, with 3 Holds and 1 Strong Sell. That is larger consensus upside than SK hynix.
Shares of Western Digital (NASDAQ:WDC) sit at $289.20, down 27.2% in a month. Its $613.38 target implies roughly 112% upside, with 4 Strong Buys, 17 Buys and 5 Holds. Its upside also edges out SK hynix’s.
Micron carries the group’s largest consensus upside. SK hynix ranks last on that measure but trades at the cheapest forward multiple and has the boldest outlier target. Price targets are estimates and can be cut as quickly as they are raised.
SK hynix Has Badly Trailed the S&P 500 This Year
At $129.66, SK hynix sits near its 52-week low of $122.20 and well below its high of $199.87. The $260.64 average target from 14 analysts implies 101% upside.
Over the past month, the stock fell 23.29% while the S&P 500 slid 3.67%. Year to date, the stock is down 22.81%, while the S&P 500 is up 9.99% year to date. A beta of 2.466 explains the violent swings.
Sold-Out Capacity Through 2029 Frames the Next Move
The bull case strengthens if HBM4 pricing holds through next year and long-term agreements keep the shortage intact, supporting a re-rating closer to the 9x multiple Rosenblatt models. The bear case gains weight if AI capex slows, Chinese competitors pressure DRAM pricing, or the heavy 2027 capex plan turns into the glut that ended every prior memory cycle.
Non-operating swings, currency exposure and preliminary unaudited figures add more uncertainty. Still, sold-out capacity through 2029, rising estimates and a forward multiple near 3x support the bull case. The 208% scenario needs everything to go right. Reaching the consensus target needs much less.
Contact [email protected] for any questions or corrections.
Alex Sirois is a financial writer with experience spanning both retail and institutional investing. He has written for InvestorPlace and held roles at BNY Mellon and Bernstein, giving him a perspective that bridges Main Street portfolios and Wall Street analysis.
Alex holds an MBA from George Washington University and has built his career across multiple industries, including e-commerce, education, and translation — a breadth of experience that informs how he breaks down complex financial topics for everyday investors. His writing is conversational, actionable, and grounded in long-term, buy-and-hold investing principles.
At 247 Wall St., Alex focuses on delivering analysis that is both accessible and useful, with a clear emphasis on helping readers make more informed decisions with their money.