Bloom Energy Has Found an Unexpected Customer: AI

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

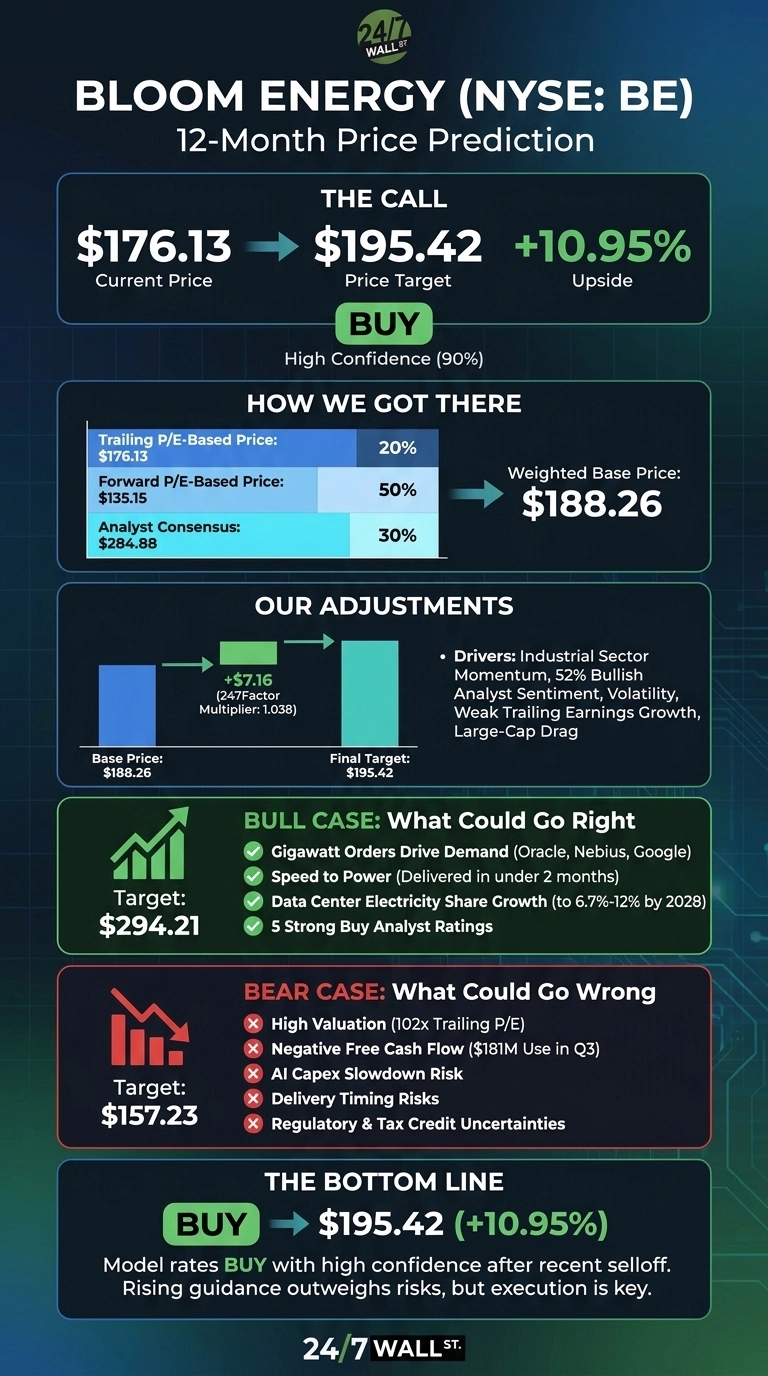
Bloom Energy (NYSE:BE) designed its solid-oxide fuel cells for corporate campuses, hospitals and retailers. AI hyperscalers have since become the core of its business. The 24/7 Wall St. price target for Bloom is $195.42 over the next 12 months, or 10.95% above the current $176.13. The model rates the stock a buy with high confidence.
| Metric | Value |
|---|---|
| Current Price | $176.13 |
| Price Target from 24/7 Wall St. | $195.42 |
| Upside/Downside | 10.95% |
| Model Rating | BUY |
| Confidence Level | 90% |
Our target sits well below the Wall Street consensus of $284.88. The gap reflects volatility: Bloom has a beta of 3.618, which means sharp swings in both directions, so the model discounts heavily for volatility. Even so, it still points higher from here.
A 40% Slide Followed a Record Quarter
Bloom shares have dropped 20.76% in a week and 40.45% in a month. They remain up 102.72% year to date. The stock trades about 49.9% below its 52-week high of $351.28 and roughly 132.7% up from its low of $75.70. The selloff came after a record earnings report, as investors took profits on a stock where beats were already priced in.
Third-quarter revenue reached $1.24 billion against a $1.07 billion consensus, a gain of 138.1% from a year earlier. Non-GAAP EPS of $0.94 exceeded the $0.67 estimate.
Bloom also raised its full-year outlook for the third time, to $4.4 billion to $4.6 billion in revenue and $3.10 to $3.40 in non-GAAP EPS. Chief executive K.R. Sridhar summed up the demand: “Hyperscalers have been the first to embrace on-site power. They need power rapidly and at large scale.”
Gigawatt Orders Could Drive Shares to $294
In the bull case, Bloom reaches $294.21. Speed to power is the selling point. Bloom says it “delivered power to [Oracle’s] Utah site in less than two months”, and it has servers ready for a 300 megawatt Nebius Group project. American Electric Power disclosed plans for 700 megawatts of carbon-capture-enabled Bloom servers to supply Google.
Bloom’s factories can already produce over five gigawatts a year. Demand has room to keep growing, since Lawrence Berkeley National Laboratory projects data centers could use between 6.7% and 12% of U.S. electricity by 2028.
Bloom is one of a handful of power, cooling, and networking names riding that AI expansion, and we covered seven of them in a free report here. Analyst support is solid, with 5 analysts giving a Strong Buy rating, alongside 10 Buy ratings.
Cash Burn and Valuation Could Pull Shares to $157
In the bear case, the stock falls to $157.23. Bloom trades at 102x trailing earnings, so any slowdown in AI spending would hit the shares hard. Free cash flow was a use of $181 million last quarter. Fourth-quarter results also hinge on “the timing of a small number of deliveries around year-end”.
The cash burn reflects spending on new capacity at Fremont and Newark. Year-to-date free cash flow remains positive $42 million, and Bloom has $2.5 billion in cash. Changes to federal tax credits and slow air permits are still open risks.
Bloom Grows Faster Than Vertiv and Plug Power
Vertiv (NYSE:VRT | VRT Price Prediction) is a useful comparison because both companies sell power gear to AI data centers. Vertiv trades at 24x forward earnings, with quarterly revenue growth of 61.2%. Bloom earns its higher multiple by growing more than twice as fast.
Plug Power (NASDAQ:PLUG) is a direct fuel cell rival, but it posted trailing gross profit of -$184.1 million and revenue growth of just 2.5%. Against these two, our target looks reasonable.
| Company | Forward P/E | Price/Sales | Quarterly Revenue Growth |
|---|---|---|---|
| Bloom Energy | 35x | 12.93 | 138.1% |
| Vertiv | 24x | 5.19 | 61.2% |
| Plug Power | N/M (TTM EPS -$1.36) | 2.741 | 2.5% |
Our Model Rates Bloom a Buy After the Selloff
The 24/7 Wall St. price target of $195.42 comes with a buy rating and 90% confidence. The balance tips because guidance keeps rising while the share price falls.
Keep an eye on whether fourth-quarter deliveries land on time and free cash flow becomes positive again. Cuts to hyperscaler capex would weaken the case. After a 40.45% drop in a month, the valuation risk looks smaller than it did in October.
If current growth and market conditions has, here is where the 24/7 Wall St. model projects Bloom could trade.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $174.95 |
| 2027 | $195.42 |
| 2028 | $196.83 |
| 2029 | $211.67 |
| 2030 | $251.40 |
Bloom needs to keep executing on its current strategy for these projections to has. Carbon capture adoption or a pullback in AI capex would move results well above or below these levels.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.