If This Tech Giant Doubles, Here’s What $10,000 Could Become

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
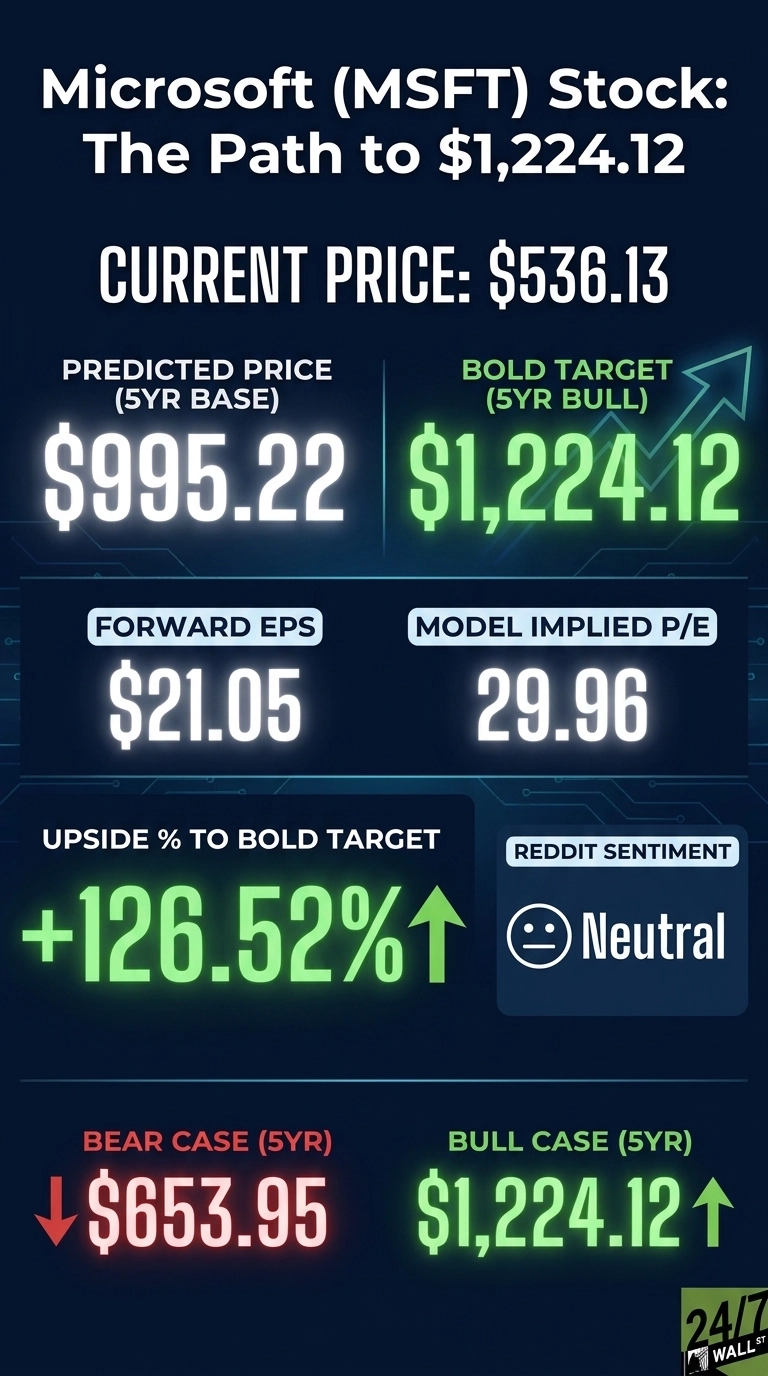
Shares of Microsoft (NASDAQ:MSFT | MSFT Price Prediction) recently traded at $536.13, and the price-prediction model behind this analysis starts from a reference price of $540.40.
The question for a $10,000 stake: what could it become by 2031, the end of the five-year projected horizon, and does the stock actually double along the way? With Azure revenue up 48% YoY and a commercial backlog of $677B, this forecast rests on reported results.

What $10,000 in Microsoft Could Grow Into by 2031
In the base case, a $10,000 investment could be worth about $18,416 by 2031, a total return of 84.16%. That outcome is tied to a projected five-year share price of $995.22, which works out to an annualized return of 12.99%.
A true double requires a share price of roughly $1,080.80. Only the bull case gets there: a target of $1,224.12, returning 126.52% in total, and an ending value of $22,652. On the projected bull path, the stock passes the doubling line by mid-2030, at $1,106.04 on August 5, 2030.
Bull, Base, and Bear Scenarios for a $10,000 Stake
| Scenario (5-Year) | Target Share Price | Total Return | Value of $10,000 |
|---|---|---|---|
| Bull | $1,224.12 | 126.52% | $22,652 |
| Base | $995.22 | 84.16% | $18,416 |
| Bear | $653.95 | 21.01% | $12,101 |
The one-year horizon offers a closer checkpoint. The central scenario calls for $662.60 per share (22.61%), turning $10,000 into $12,261. The bull case reaches $765.94 ($14,174), while the downside scenario sits at $557.93 ($10,324).
Wall Street tends bullish. The analyst consensus target is $633.13, with 12 Strong Buy, 40 Buy, and 5 Hold ratings and zero Sells. The model carries a confidence score of 0.9, rated high.

Three Drivers Behind the Upside Case
Azure Demand Outrunning Supply
Microsoft Cloud revenue reached $63.9B, up 30% and speeding up. Chief Financial Officer Amy Hood guided Azure growth to “49% to 50% in constant currency” next quarter, and management said “customer demand continues to exceed available supply.”
A Massive Contracted Backlog
Commercial remaining performance obligations grew 73% to $677 billion, with roughly 30% expected to convert to revenue in the next 12 months. That backlog supports second-quarter revenue guidance of $96 billion to $97.1 billion.
Copilot Monetization and Steady Earnings Beats
Copilot daily users rose nearly 50% quarter-over-quarter and over 5x year-over-year. Non-GAAP EPS of $4.89 exceeded the $4.72 estimate, the sixth consecutive beat.
Chief Executive Satya Nadella told analysts, “I’ve never been more confident in the long-term returns for our investments.” At a forward P/E of about 26, the central scenario assumes that confidence keeps translating into earnings growth.
Risks That Could Shrink Your $10,000 Outcome
Spending is the biggest swing factor. Capital expenditures jumped 102.99% YoY to $39.37B in addition to property and equipment, and management expects calendar-year CapEx of approximately $170 billion. Free cash flow came in at $18.6 billion for the quarter.
All of that expansion still has to be powered, cooled, and connected by somebody, and we covered seven of those suppliers in a free AI infrastructure report. If AI returns lag the expansion, the multiple could contract toward the downside scenario.
Other pressure points include delayed third-party GPU deliveries pushed to the second half of the fiscal year, a forecast for slightly lower operating margins in the second quarter, and Windows OEM and Devices revenue falling 22%. Gains or losses on the OpenAI investment can also swing GAAP earnings.
The stock’s 52-week range of $348.54 to $559.15 shows how far sentiment can move, and shares have slid since the latest earnings report, according to Morningstar. Under the downside scenario, $10,000 grows only to $12,101 over five years.
Bottom Line for a $10,000 Microsoft Position
Across the five-year scenarios, a $10,000 stake in Microsoft ranges from $12,101 in the downside scenario to $22,652 in the bull case, with a base case of $18,416.
Doubling depends on the bull path, which needs Azure growth, Copilot adoption, and AI returns to hold up together. Keep an eye on Azure growth rates and capital spending in each earnings report. It’s a projection, not investment advice, and none of these figures is guaranteed.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.