Prediction: The Next Phase of Coinbase Could Be Its Most Important Yet

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
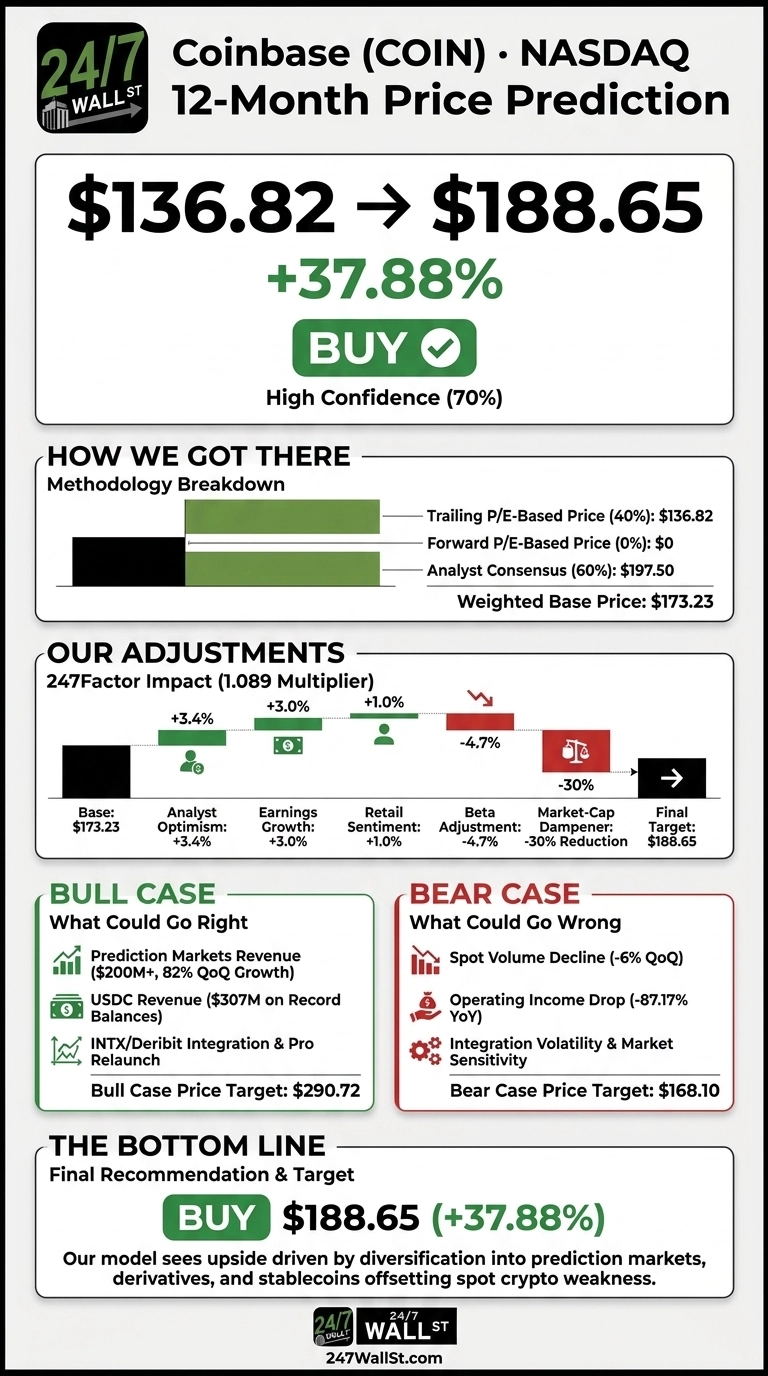
Coinbase (NASDAQ:COIN | COIN Price Prediction) spent 2026 rebuilding itself as an “Everything Exchange,” and the market has yet to reward it. Its shares last closed at $136.82. The 24/7 Wall St. price target is $188.65 over the next 12 months, which means 37.88% upside.
The model rates the stock a buy with 70% confidence, a fairly high reading. The core thesis is that prediction markets, derivatives, and stablecoins can carry results while spot crypto trading stays soft.
| Metric | Value |
|---|---|
| Current Price | $136.82 |
| Price Target from 24/7 Wall St. | $188.65 |
| Upside/Downside | 37.88% |
| Recommendation | BUY |
| Confidence Level | 70% |

A 41% Year-to-Date Slide Leaves Coinbase at Its 52-Week Low
Coinbase is down 16.94% over the past week, 28.18% over the past month, and 41.01% year to date. It traded at $133.39 midday Friday, right at its 52-week low of $133.50 and far below its $324.80 high. Bitcoin (CRYPTO:BTC) lost 8.76% over the past month, and this week Morgan Stanley (NYSE:MS) told investors to steer clear of the stock.
Third-quarter revenue of $1.22B fell 35% YoY, narrowly missing expectations of $1.221B. GAAP EPS of $2.51 beat expectations of $0.07, but $715M of crypto investment gains drove most of it. Q4 transaction revenue of about $165M through October 25 points to a slow start for the quarter.
Why Bulls See a Path to $290
Prediction markets passed $200M in annualized revenue, growing at 82% per quarter. Together, predictions and derivatives now account for about 25% of transaction revenue. Coinbase also gained crypto trading share for a fourth straight quarter, reaching 10.7%, and a record $22B in average USDC (CRYPTO:USDC) balances raised stablecoin revenue to $307M.
On the earnings call, Alesia Haas said “this is all incremental”. Further catalysts include the Deribit integration, the Coinbase Pro relaunch, and $2B left on the buyback authorization. The bull case reaches $290.72.
What Could Keep Coinbase Stuck Near Its Lows
Spot volume fell 6% QoQ, and operating income dropped 87.17% YoY to $61.7M. Management also expects some near-term volume swings as traders move onto the combined INTX/Deribit platform.
As a counterpoint, Adjusted EBITDA rose 60% QoQ to $333M after the May cost cuts, and management lowered full-year expense guidance. Our bear case lands at $168.10. A sustained break below the 52-week low would test that figure.

Coinbase Trades at a Premium to Robinhood and Interactive Brokers
Robinhood Markets (NASDAQ:HOOD) competes for the same retail crypto and prediction-market users. The stock trades at 29x forward earnings, compared with 54x for Coinbase. In Q2, Robinhood’s event-contract revenue reached $156 million while its crypto revenue fell 38%.
Interactive Brokers (NASDAQ:IBKR) is the diversified-broker comparison. The stock trades at 22x forward earnings, and customer accounts grew 35% to 5.58 million.
| Company | Forward P/E | Beta |
|---|---|---|
| Coinbase | 54x | 3.353 |
| Robinhood | 29x | 2.528 |
| Interactive Brokers | 22x | 1.381 |
The higher multiple reflects Coinbase’s low earnings. Our target also sits below the analyst consensus, so the 24/7 Wall St. price target looks reasonable, even slightly conservative, next to this peer group.

Diversification Tips the Scale Toward Upside
The 24/7 Wall St. price target of $188.65 comes with a buy rating and 70% confidence. Management said prediction markets offset weaker spot trading and kept revenue flat QoQ.
My confidence would build if those businesses keep growing. I’d become more cautious if transaction revenue stays near its October pace. At today’s price, both the model’s bull and bear case sit above the current share price.
Our model projects where Coinbase could trade if current trends continue.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $138.55 |
| 2027 | $188.65 |
| 2028 | $219.53 |
| 2029 | $257.38 |
| 2030 | $319.76 |
The projections assume Coinbase keeps executing on its current strategy. Stablecoin adoption or a long crypto downturn could move results sharply in either direction.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.