Not One Analyst Rates Broadcom a Sell. What Are They Missing?

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
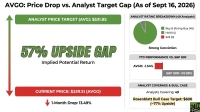
Overwhelming bullish sentiment surrounds Broadcom (NASDAQ:AVGO | AVGO Price Prediction). Not one of 51 analysts rates it a Sell or Strong Sell, and the consensus target of $533.42 is about 49.6% above the $356.54 opening price on November 13, 2026.

Shares are up only 0.6% year to date, even after an 18.5% one-week run as Broadcom led S&P 500 gainers amid turmoil at Nvidia (NASDAQ:NVDA), according to MarketWatch. The question is whether agreement is itself a risk. Our framework mirrors the one we used in our earlier analyses of Microsoft (NASDAQ:MSFT) and Nvidia: Not One Analyst Rates Microsoft a Sell. Is the Consensus View Right? and Only One Analyst Rates Nvidia a Sell. Is the Lone Bear Onto Something?
What Bulls Are Paying For
Broadcom has beaten EPS estimates for nine consecutive quarters. In fiscal Q3, it posted non-GAAP EPS of $3.32 against a $3.24 consensus, and revenue of $29.59 billion exceeded the $29.44 billion estimate. AI semiconductor revenue rose 221% to $16.70 billion, and Q4 guidance calls for $21.7 billion.

The valuation helps the bulls. The stock trades at 18x forward earnings compared with 44x trailing. The fiscal 2027 EPS consensus of $19.4651 from 48 analysts is up from $19.3807 some 30 days ago, with two upward revisions and none downward.
On CNBC’s Halftime Report on October 27, Stephanie Link said Broadcom guided 2027 revenue to $115 billion, rising to $230 billion by 2028. Link said the Anthropic deal secured about $60 billion in 2027 revenues. Jim Cramer said on CNBC on September 15 that “Broadcom’s view, there will be no slowdown, is the one that is going to take hold of the narrative.” On October 28, Cramer added: “I wouldn’t shoot Broadcom.”
Bear Case No Analyst Is Making
The strongest objections come from outside the analyst ranks. On the Halftime Report on October 27, Jenny Harrington said, “I think there’s a problem when the CEO of Broadcom needs to intervene in the funding of another company.” The same day, Cramer asked on CNBC, “What happens when the next deal comes with companies that aren’t as good as Broadcom or Anthropic?” On November 2, Joe Terranova on the Halftime Report described the all-stock purchase of Lumentum (NASDAQ:LITE) by Marvell Technology (NASDAQ:MRVL) this way: “They’re chasing Broadcom, in my opinion.”
Management has highlighted its own constraints, including land, power, substrates, and HBM memory, and the AI outlook depends on six XPU customers. Beating estimates has also failed to protect the stock. Shares fell 12.59% on the day following the fiscal Q2 report and 11.43% after fiscal Q4 2025, even though both quarters beat.
Unanimous Ratings, Divided Money
Institutions own 79.7% of shares. In the latest 13F filings from tracked filers, for the quarter ended September 30, 2026, the only filer, Renaissance Technologies, cut its stake to 734 shares. Note that this is a quarter-end snapshot and does not show what anyone holds today.
Near-term estimates have also flattened. The fiscal Q4 EPS consensus of $3.8377 is below the $3.8609 of 90 days ago. The price holds above the 50-day moving average of $346.13 but below the 200-day average of $367.12, and a beta of 1.51 points to above-market swings.

Verdict for Retail Investors
The consensus seems to be right on fundamentals. Results keep beating estimates, AI revenue is still accelerating, and the forward multiple is modest for this growth rate. The roughly 50% gap to the target reflects the market pricing in financing and supply risk while demand signals remain strong. Investors researching the stock today can weigh the analysts’ thesis against the volatility that comes with it. (For readers hunting the next monster AI chip winner, we listed the early traits in a free playbook here.)
The test comes with the next report, expected around December 10, 2026. Key checks: whether revenue reaches the guided $34.8 billion, whether gross margin holds near the guided 73%, and whether management adds detail on how it supports financing for its AI customers.

Contact [email protected] for any questions or corrections.
Trey has been an editor and author at 24/7 Wall St. for more than a decade, where he has published thousands of articles analyzing corporate earnings, dividend stocks, short interest, insider buying, private equity, and market trends. His comprehensive coverage spans the full spectrum of financial markets, from blue-chip stalwarts to emerging growth companies.
Beyond 24/7 Wall St., Trey has created and edited financial content for Benzinga and AOL's BloggingStocks, contributing additional hundreds of articles to the investment community.
Trey's editorial expertise extends across multiple publishing environments. He served as production editor at Dearborn Financial Publishing and development editor at Kaplan, where he helped shape financial education materials. Earlier in his career, he worked as a writer-producer at SVE. His freelance editing portfolio includes work for prestigious clients such as Sage Publications, Rand McNally, the Institute for Supply Management, the American Library Association, Eggplant Literary Productions, and Spiegel.
Outside of financial journalism, Trey writes fiction and has been an active member of the writing community for years, moderating workshop sessions at regional conventions.