Jim Cramer Says Lam Research Has Come Down Enough. It’s ‘Absolutely My Favorite’

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Jim Cramer thinks the selloff in Lam Research (NASDAQ:LRCX | LRCX Price Prediction) has run its course. On the November 12, 2026 episode of Mad Money, he said, “I think it’s come down enough.” He added, “It is absolutely my favorite.” Then he gave his reason: “Remember, all the intellectual property when it comes to semiconductors really is from the semiconductor capital equipment, and Lam’s got the best.”
Lam Shares Have Dropped 21% in a Month
The price data backs up the “come down” part. Lam closed at $225.92 on November 13, down 21.26% from $286.92 a month earlier. It trades below its 50-day moving average of $277.66 and its 200-day average of $283.87. The pullback comes off a big run: shares remain up 32.38% year to date, and they bounced 12.71% last week. With a beta of 2.01, expect big swings in both directions.
Why Cramer Favors the Toolmakers Over the Chipmakers
Lam sells wafer fabrication equipment, mainly deposition and etch tools. Deposition puts down thin films of material onto a silicon wafer. Etch carves material away to form transistors and wiring. Taiwan Semiconductor Manufacturing (NYSE:TSM), Samsung and SK Hynix all need these machines, so Lam gets paid regardless of which chip designer wins the AI race.
Chips are also getting harder to make. Stacked NAND, high-bandwidth memory and advanced packaging all add steps. Management said on the October call, “As all device architectures go 3D, etch and deposition intensity rises.”[1] Cramer made a similar point back in April: “Lam Research makes the equipment that makes the memory. So the demand for that is off the charts.” Memory systems revenue rose 120%[1] year over year in the September quarter.
Record Results and Higher Guidance

In fiscal Q1 2027, revenue reached $8.22 billion[2], up 54.38% year over year and ahead of the $8.13 billion estimate. Non-GAAP EPS of $2.20[2] exceeded the $2.1771 consensus, Lam’s sixth consecutive beat. Operating margin hit 40.2%[1], and free cash flow came in at $3.24 billion[2], according to the company’s earnings release filed with the SEC.
For the December quarter, Lam guided to revenue of $8.60 billion +/- $400 million[2] and EPS of $2.33 +/- $0.15. Management expects 2026 industry equipment spending in the “mid $150 billion range”[1] and “more than $200 billion” in 2027, with customer visibility “through 2028.”
Valuation and the Dividend


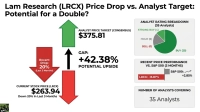
Lam trades at a trailing P/E of 34 and a forward multiple of 23. Its PEG ratio of 0.983 suggests the price roughly matches expected growth. Analysts are mostly bullish: 5 strong buys, 25 buys, 4 holds, and 0 sells, with an average target of $362.10.
The quarterly dividend of $0.33 goes ex-dividend December 2, a yield of about 0.47%. Buybacks matter more: Lam bought back roughly $1.025 billion[2] of stock in the September quarter.
China Exposure and Spending Cycles Pose Real Risks
China supplied 35%[1] of revenue last quarter, up from 26% in the June quarter. Lam flags export controls, entity listings and tariffs as threats to that business. Management already expects China to account for a “significantly lower percentage”[1] of December-quarter revenue as domestic Chinese customers spend less.
Equipment spending is also cyclical. Chipmakers buy heavily when demand runs hot and cut hard when it cools. Supply chain constraints already held down December guidance, according to management.
Does Cramer’s Case Hold Up?
Mostly, yes. Since the October report, the stock has fallen, even as guidance points to another record quarter and management expects a bigger 2027. Cramer’s toolmaker logic also checks out: Lam benefits from every chipmaker’s capacity expansion, and rising chip complexity steadily adds to how much equipment each fab needs (we profiled seven companies riding this same AI infrastructure buildout, from power to equipment suppliers, in a free report you can grab here).
The weak spot is timing. Cramer’s call depends on 2027 spending clearing $200 billion[1] and on China sales falling no faster than management expects. Watch the stock’s next earnings report, especially China’s revenue share and any update to the 2027 spending outlook.
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.