Something Is Changing at Amazon, and Investors Should Pay Attention

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Something has changed inside Amazon (NASDAQ:AMZN | AMZN Price Prediction). The retailer has become one of the world’s largest AI infrastructure businesses. AWS revenue rose 39%[1] in Q3, its fastest in nearly five years. CEO Andy Jassy told investors, “There has never been a trillion dollar revenue business, and we may have two of them in the next 5-10 years.”[1]
Shares are up 15.87% year to date at $264.94, which puts the stock on pace for a fourth straight annual gain after rising 80.9% in 2023, 44.4% in 2024 and 5.2% in 2025. Reaching $350 per share in 2027 depends on several drivers.
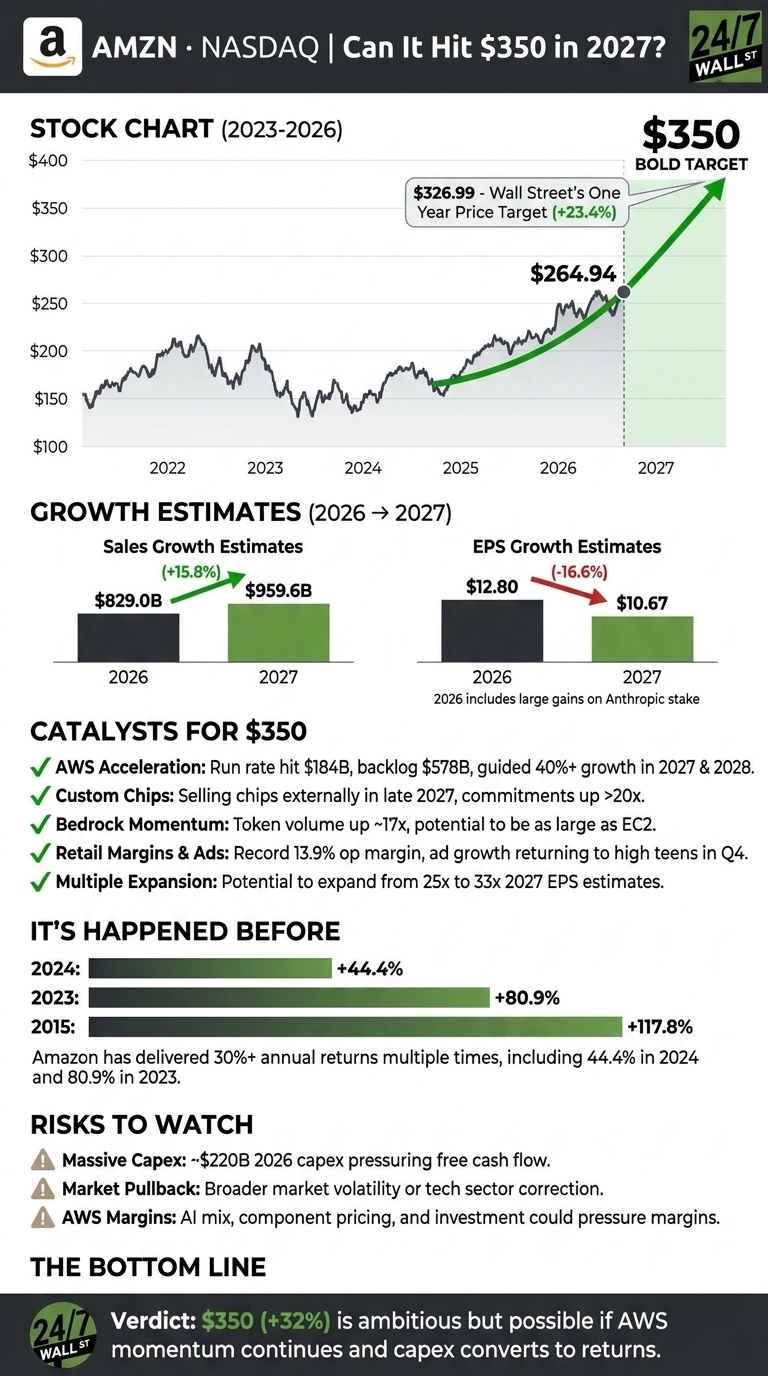
Wall Street Already Sees 23% Upside for Amazon
Analysts’ average one-year target is $326.99, meaning 23.4% upside. Coverage leans heavily bullish, led by 16 strong buy and 42 buy ratings against 2 holds and zero sells.

Analysts expect revenue of $959.6 billion in 2027, up 15.8% from 2026’s projected $829 billion. The 2027 EPS consensus of $10.6712 sits below 2026’s $12.8011 because this year includes large gains on Amazon’s Anthropic stake. Estimates are moving higher: 90 days ago the 2027 figure was $10.4993, and it drew 16 upward revisions in the past week with none down.

Here’s What It Takes for Amazon to Reach $350
At today’s price, Amazon trades at 25x 2027 earnings estimates. At $350, that multiple would expand to roughly 33x, a premium to the S&P 500’s forward multiple of about 21x to 23x. That premium looks justified for a company whose cloud unit is guided to grow more than 40%[1] in both 2027 and 2028.

What Could Push Amazon to $350?
- AWS acceleration: Growth sped up for the sixth straight quarter[2], the run rate hit $184 billion, and backlog reached $578 billion.
- Custom chips: Graviton and Trainium commitments each rose more than 20x[2]. Jassy said, “We believe we are going to have a very significant business selling chips externally, and we are going to start in late 2027.”[2]
- Bedrock: Token volume is up nearly 17x[2], and Jassy believes it “could be a service as large as EC2.”
- Retail margins and ads: Operating margin hit a record 13.9%[1], North America operating income rose to $8.72 billion from $4.79 billion, and management expects ad growth to return to the high teens[2] in Q4.
- Earnings track record: Amazon beat EPS estimates in every quarter from Q3 2023 through Q2 2025 and again in Q1 and Q2 2026, though Q3 EPS came in 3.47%[1] below estimates, missing expectations.

The main hurdle is spending. Capex of roughly $220 billion[1] this year has pushed trailing free cash flow to an outflow of $42.4 billion, and management plans to spend more in 2027. That expansion has to be powered, cooled, and networked by somebody, and we analyzed seven of those suppliers in a free AI infrastructure report.
Amazon’s History Says $350 Is Within Reach
Reaching $350 requires a 32.1% gain. Since 2001, Amazon has topped that in multiple calendar years.
Shares jumped 178.6% in 2003, 162.3% in 2009 and 117.8% in 2015. At a $2.87 trillion market cap, triple-digit years are unlikely, but the 44.4% gain in 2024 shows a 30%-plus year remains possible.
Is $350 Realistic? Here’s My Take
Hitting $350 would require a 32.1% gain in 2027. Analysts already project 23.4% upside, 2027 estimates are rising, and AWS is accelerating on a massive base.
If capex starts converting into visible returns, chip sales open a new revenue line, and the broader market holds up, $350 looks achievable. Such returns shouldn’t be expected every year, but we’ve outlined the case for how Amazon could see outsized returns in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.