3 Cell Tower REITs Positioned to Profit as Wireless Data Demand Quadruples

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
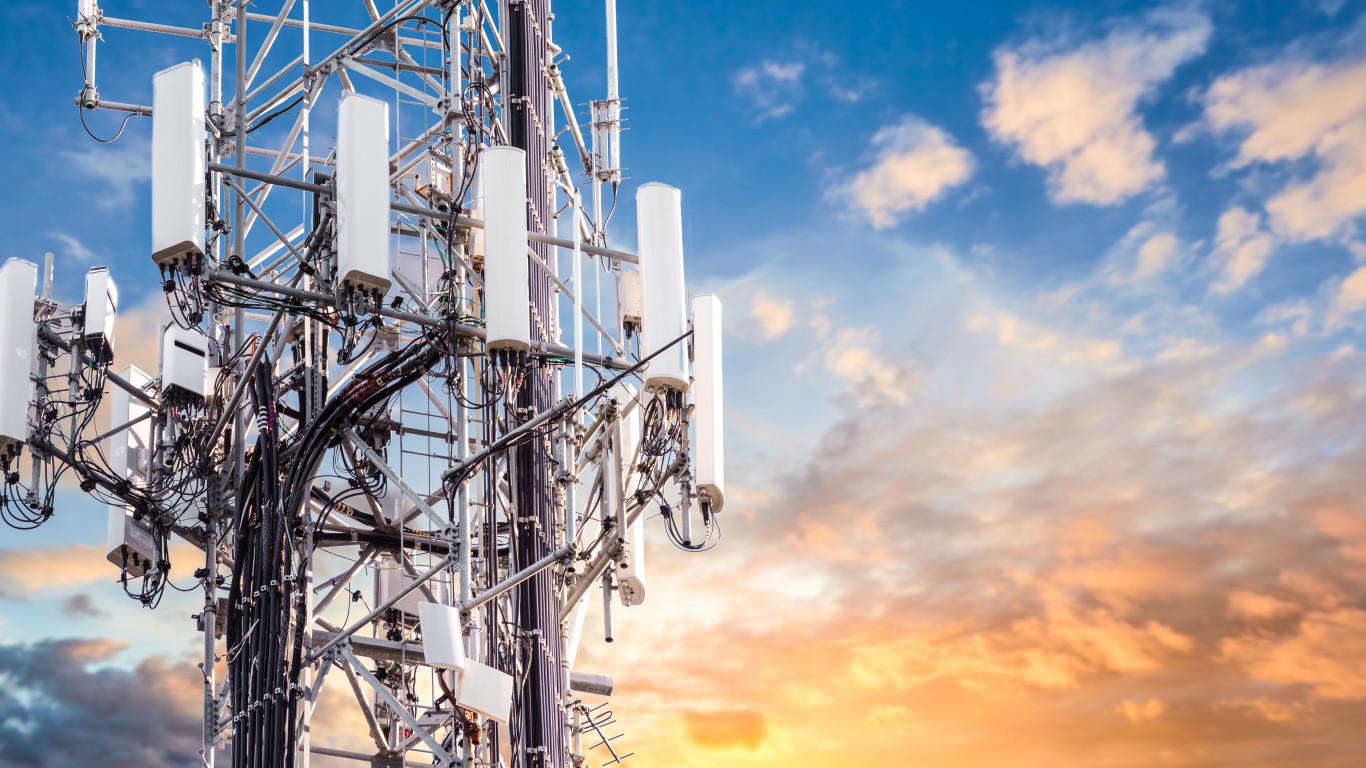
Americans used a record 159 trillion megabytes[1] of wireless data in 2025, and the industry group CTIA expects total wireless demand to grow fourfold by 2032. All of that traffic has to pass through radios bolted to steel towers, and three U.S.-listed REITs own most of those towers. The business is simple. Tower REITs rent space on their towers to wireless carriers under long-term contracts with rent increases built in, and each new tenant on an existing tower adds revenue at very little extra cost.
That steady, contract-backed cash pays for the dividends below. Each of the three also reports that 2026 was a weak year for organic growth, while a new round of spectrum auctions is coming. Here is how their dividends hold up, starting with safety.
American Tower: A Growing Payout With Plenty of Cushion
American Tower (NYSE:AMT) pays a quarterly dividend of $1.79, or $7.16 annualized. With shares trading at $190.74, that works out to a yield of about 3.75%.
Dividend safety: REITs measure their payout against AFFO, a better gauge of cash than GAAP earnings. American Tower expects 2026 AFFO of $11.04 to $11.16[2] per share, so the annualized dividend uses roughly 64.5% of the midpoint. Third-quarter free cash flow came in at $986 million[2], compared with dividend spending of about $831 million. Net leverage was 4.9 times[1], within the company’s 3 to 5 times target range. The dividend history includes one confirmed cut: the quarterly payout dropped from $1.70 to $1.62 in early 2024. It has grown since then. The 2026 payments are up 5.3% per share from a year earlier.
Bull case: American Tower also owns data centers through CoreSite, and that business is growing fastest. Data center revenue rose 17.4% to $313 million[2] in the third quarter. The company raised its full-year guidance for the third time this year[2] and added a new $2.0 billion buyback authorization. CFO Rodney Smith said, “Heading into 2027, we are confident that we can deliver a meaningful inflection in growth and return to our long-term expectation of AFFO per share growth in the mid- to high-single-digit range.”[1] American Tower is also selling its Canadian business, with closing expected in Q4 2026.
Risk: Organic growth in the U.S. and Canada was flat[1] in the third quarter because of DISH tenant cancellations, which cost $63M. Management also expects reserves linked to AT&T Mexico revenue to reach about $70 million[1] by the end of 2026.
Crown Castle: Highest Yield, Lowest Margin for Error
Crown Castle (NYSE:CCI) pays $1.0625 per quarter, or $4.25 annualized. At $89.01 per share, the yield is about 4.77%, the highest of the three. Shareholders can expect the next payout on December 31, 2026.
Dividend safety: Income investors should know this history first. Crown Castle cut its quarterly dividend from $1.565 to $1.0625 starting in June 2025, as it prepared to sell its fiber business. The lower amount has stayed the same since. The reset dividend uses about 92.4% of the $4.60 AFFO-per-share guidance midpoint, which leaves little room (the seven warning signs that a high yield is about to be cut are all in our free Dividend Traps report). Third-quarter results were better: AFFO of $530M[3] comfortably covered the roughly $452M dividend. Leverage was 6.5x[3]. Crown Castle repaid more than $7 billion of debt after the sale, and interest expense fell to $177M from $247M[3] a year earlier.
Bull case: Since closing the $8.4B[4] sale of its fiber and small cell business, Crown Castle owns only U.S. towers, which makes it a simpler and cheaper business to run. It has identified $65 million[5] in annualized cost savings, expects to buy more than 400 ground leases under its towers in 2026, and is testing edge computing at more than 100 sites. The CFO, Sunit Patel, said: “We continue to expect 2026 to mark the low point for organic growth.”[5] The stock rose 8.21% over the past month.
Risk: Crown Castle depends heavily on three customers. T-Mobile, AT&T, and Verizon account for 93% of site rental revenue. AT&T leases worth $774M in annualized revenue come up for renewal in 2028, and $2,197M of debt matures in 2027.
SBA Communications: Fastest Dividend Growth in the Group
SBA Communications (NASDAQ:SBAC) has the lowest yield of the three. It pays $1.25 per quarter, or $5 annualized, about 2.69% for $185.74. The next payment is due December 10, 2026[6].
Dividend safety: SBA’s payout is the best covered among the three. Management said the dividend equals about 41% of the midpoint[7] of its full-year AFFO-per-share outlook, and third-quarter AFFO was $3.19 per share against the $1.25 dividend. The quarterly payout has risen every year in the records shown, from $0.37 in 2019 to $1.25 now, with no confirmed cuts. SBA earned an investment-grade credit rating this year (S&P BBB) and sold its first unsecured bonds: $3.5B at an average rate of 5.113%. Leverage stands at 6.4x[6], within its 6.0x to 7.0x target range.
Bull case: A dividend that’s about 13%[7] higher than a year ago drew this comment from chief executive Brendan Cavanagh: “We expect to continue growing our dividend at the highest growth rate in the industry.” International site leasing revenue rose 13.3% to $211M[6]. Management also raised the AFFO-per-share guidance midpoint by $0.08[6]. The upper C-band spectrum auction is scheduled to begin in April 2027[7], and management said each major auction over the past two decades was followed by a large wave of new equipment on its towers.
Risk: U.S. churn (canceled leases) is weighing on domestic results. Sprint-related churn should total $55 million to $56 million[7] in 2026, EchoStar-related churn $56 million, and domestic site leasing revenue fell 3.4%[6]. Management also lowered its revenue guidance midpoint by $18M[6]. The stock is down 1.42% this year.
Contract-Backed Income Before the Next Spectrum Wave
All three companies say 2026 is the low point for growth, and all three are buying back shares while carriers prepare for the next round of spectrum. SBA Communications offers the safest coverage and the fastest dividend growth. American Tower adds a balance of solid coverage and a fast-growing data center business. Crown Castle pays the highest yield but has the smallest cushion, so watch its AFFO coverage and 2027 debt refinancing in each earnings report.
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.