Americans Are Taking Out $57,235 Car Loans. This Hidden Debt Trap Explains Why

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
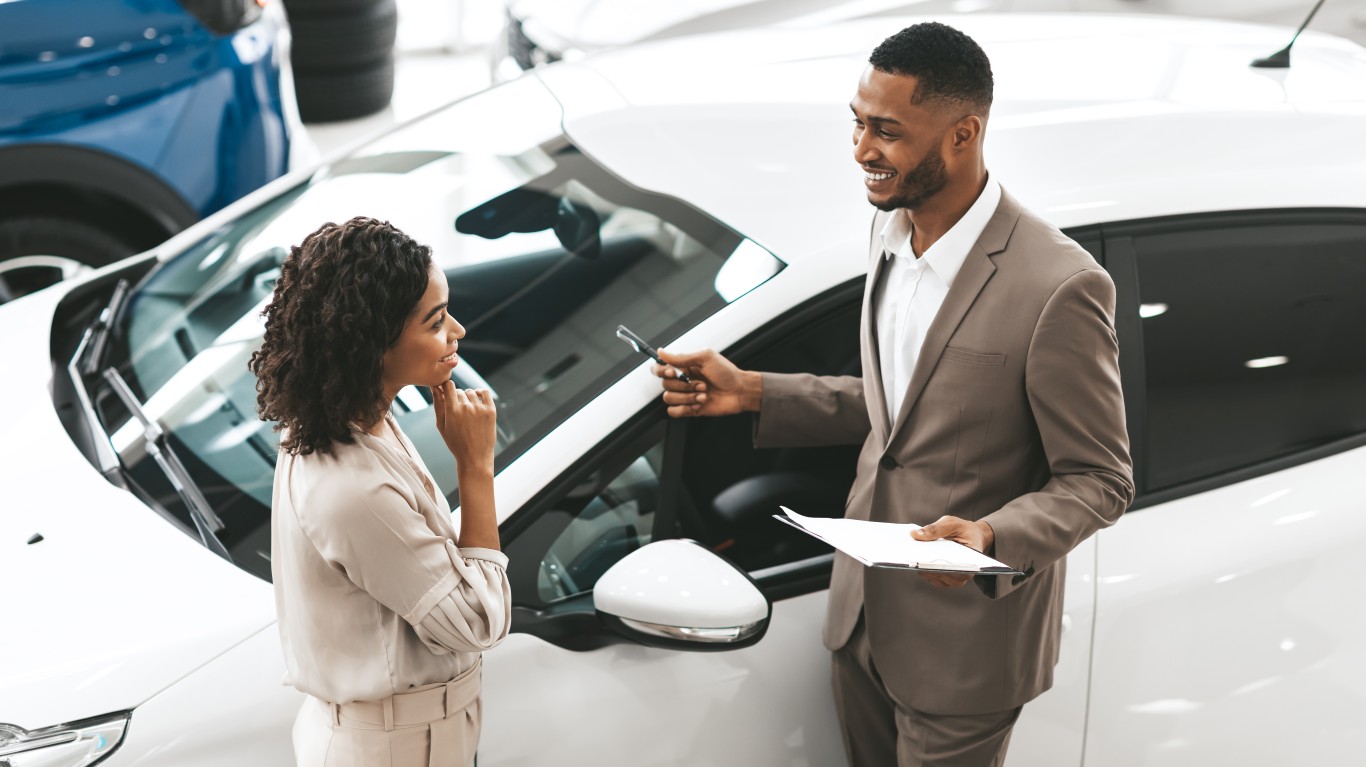
The average buyer who rolled an underwater car loan into a new one last quarter walked out owing $57,235. That figure comes from Edmunds’ negative equity report released October 21, 2026. The loan has a monthly payment of $952 and an estimated $16,610 in lifetime interest. In the third quarter of 2019, the same type of borrower financed $39,732 and paid $646 a month.
These buyers are a part of the market. Edmunds counts 29.1% of financed trade-ins toward new vehicles as underwater, up from 28.1% a year earlier. The average shortfall was $7,107. This group is also the clearest early warning of where household balance sheets are breaking.
Pandemic Prices Are Coming Due Now
The timing has a simple cause. Many of the cars being traded in were bought at pandemic-era peak prices, and used-vehicle values have fallen since then, according to Edmunds. A loan written against an inflated price runs into a deflated trade-in value, and the gap gets folded into the next loan.
“It’s just a snowball effect that keeps this debt rolling from generation to generation of vehicle,” Sam Fiorani, vice president of global vehicle forecasting at AutoForecast Solutions, told Marketplace.
Loan terms make the snowball bigger. 91.2% of these borrowers financed for 72 months or longer at an average rate of 8.1%. Compared with the average new-vehicle buyer, they financed roughly $12,600 more and paid about $165 more each month. A six-year loan on a depreciating asset nearly ensures the owner is underwater again at the next trade-in.
Household Cushions Are Thinning Underneath
The broader numbers show why rolling debt forward is getting riskier. The personal savings rate fell to 4.1% in the third quarter of 2026, down from 6.9% in early 2024. That is the lowest reading over that period. The Bureau of Labor Statistics’ inflation-adjusted hourly earnings measure slipped to 11.26 in October from 11.38 in January.
The Federal Reserve’s Survey of Consumer Finances found that 19.6% of families with debt were late on payments in 2025, up from 12.2% in 2022. The Fed’s distributional accounts show the bottom half of households by wealth now holds 51.6%[1] of all consumer credit, compared with 43.8% in 1989. The families least able to handle a $952 car payment are the ones has the most of this debt.
Consumers feel it. In September, the Michigan sentiment index came in at 48.1[2], well below the 60 level associated with recessions.
What Breaks If Spending Keeps Running on Credit
Retail sales reached $745.0 billion[3] in September, the highest in the past year. Spending is holding up, but a shrinking savings buffer is paying for more of it. Underwater car buyers are the stress test. Each trade-in locks in a bigger balance, a longer term and a payment that crowds out other spending. In time, some of these households won’t be able to trade in at all, which cuts into the future new-vehicle demand automakers are counting on.
Two signals matter over the next two quarters. The first is Edmunds’ fourth-quarter report. If the underwater share climbs back toward the 30.9% recorded at the start of 2026, the hangover from pandemic prices is getting worse. The second is automaker incentives.
Tyson Jominy, senior vice president at J.D. Power, told Marketplace that “customer cash” offers can wipe out part of a buyer’s negative equity. If automakers cut that cash to protect margins, more of the shortfall lands on the borrower’s next loan, and the one after that.
Contact [email protected] for any questions or corrections.
After two decades of patrolling the dark corners of suburbia as a police officer, Rich Duprey hung up his badge and gun to begin writing full time about stocks and investing. For the past 20 years, he’s been cruising the markets looking for companies to lock up as long-term holdings in a portfolio while writing extensively on the broad sectors of consumer goods, technology, and industrials. Because his experience isn’t from the typical financial analyst track, Rich is able to break down complex topics into understandable and useful action points for the average investor. His writings have appeared on The Motley Fool, InvestorPlace, Yahoo! Finance, Money Morning, and, of course, 24/7 Wall St. He has been featured in both U.S. and international publications, including MarketWatch, Financial Times, Forbes, Fast Company, and USA Today.