Salesforce Is More Than 30% Below Its December 2024 High, but $1,000 From a Decade Ago Is Still Worth More Than $2,500

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Salesforce (NYSE:CRM | CRM Price Prediction) has a split personality right now: the business keeps posting AI-driven growth while the stock trades at $217.84, down 35.70% from where it opened in December 2024 and 20.27% lower this year. Even so, $1,000 put in a decade ago is still worth $2,977. All Salesforce figures below use adjusted prices, which account for dividends.

From Cloud CRM King to Agentic Enterprise Contender
For most of the decade, Salesforce grew as the dominant cloud CRM platform, adding MuleSoft, Tableau and Slack along the way. Then came Agentforce in late 2024, and investors rushed in. Shares closed at $367.87 on December 4, 2024, the month’s high.
How the Displacement Trade Caught Up With Salesforce
In 2026, investors started to worry that AI agents would replace seat-based software. In August, Jim Cramer described enterprise software as “hammered by the displacement trade”. Salesforce responded with a $25 billion accelerated buyback funded with debt, raising noncurrent debt to $39.3 billion from $10.4 billion. Agentforce ARR passed $1.5 billion[1] in Q2 FY27, up 240%+. Even with that growth, the stock fell 12.87% over the past month.
Your $1,000 Grew to $2,749, but the Index Did Better
1-Year Return
- Initial Investment: $1,000
- Current Value: $868
- Total Return: -13.18%
- S&P 500 (same period): $1,101 (10.1%)
5-Year Return
- Initial Investment: $1,000
- Current Value: $694
- Total Return: -30.59%
- Annualized Return: -7.04%
- S&P 500 (same period): $1,580 (58.03%)
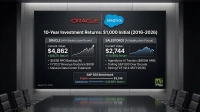
10-Year Return
- Initial Investment: $1,000
- Current Value: $2,977
- Total Return: 197.7%
- Annualized Return: 11.52%
- S&P 500 (same period): $3,386 (238.57%)
Timing decided almost everything here. Nearly all of the decade’s gain came before late 2021, when shares traded at $302.15. Buyers from that point remain underwater. The S&P 500 figures track index price only and leave out dividends, so the market’s real lead over Salesforce is even larger than these numbers show.

What Could Drive Upside If AI Revenue Keeps Compounding
Salesforce’s upside becomes more compelling if Agentforce and Data 360, already at about $3.9 billion[1] in ARR, turn into durable organic growth. At roughly 13 times management’s projected fiscal 2027 adjusted earnings, Salesforce trades at a relatively low multiple, although its higher debt load adds risk. Management has guided to FY27 non-GAAP EPS of $16.67-$16.71[1] and is targeting $63B in revenue by FY30.
Things look worse for the bears if growth slips once acquisitions stop padding the numbers. Informatica alone adds slightly above 3pts to this year’s growth. The larger debt load also leaves less room for error.

On balance, the setup looks positive. The cash flow is real, the share count is falling, and the valuation already assumes disruption. The key requirement: organic growth needs to reaccelerate in the second half, as management said.
Contact [email protected] for any questions or corrections.
David Beren has been a Flywheel Publishing contributor since 2022. Writing for 24/7 Wall St. since 2023, David loves to write about topics of all shapes and sizes. As a technology expert, David focuses heavily on consumer electronics brands, automobiles, and general technology. He has previously written for LifeWire, formerly About.com. As a part-time freelance writer, David’s “day job” has been working on and leading social media for multiple Fortune 100 brands. David loves the flexibility of this field and its ability to reach customers exactly where they like to spend their time. Additionally, David previously published his own blog, TmoNews.com, which reached 3 million readers in its first year. In addition to freelance and social media work, David loves to spend time with his family and children and relive the glory days of video game consoles by playing any retro game console he can get his hands on.