Wall Street Is Watching Nvidia. This AI Stock Deserves Attention Too

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

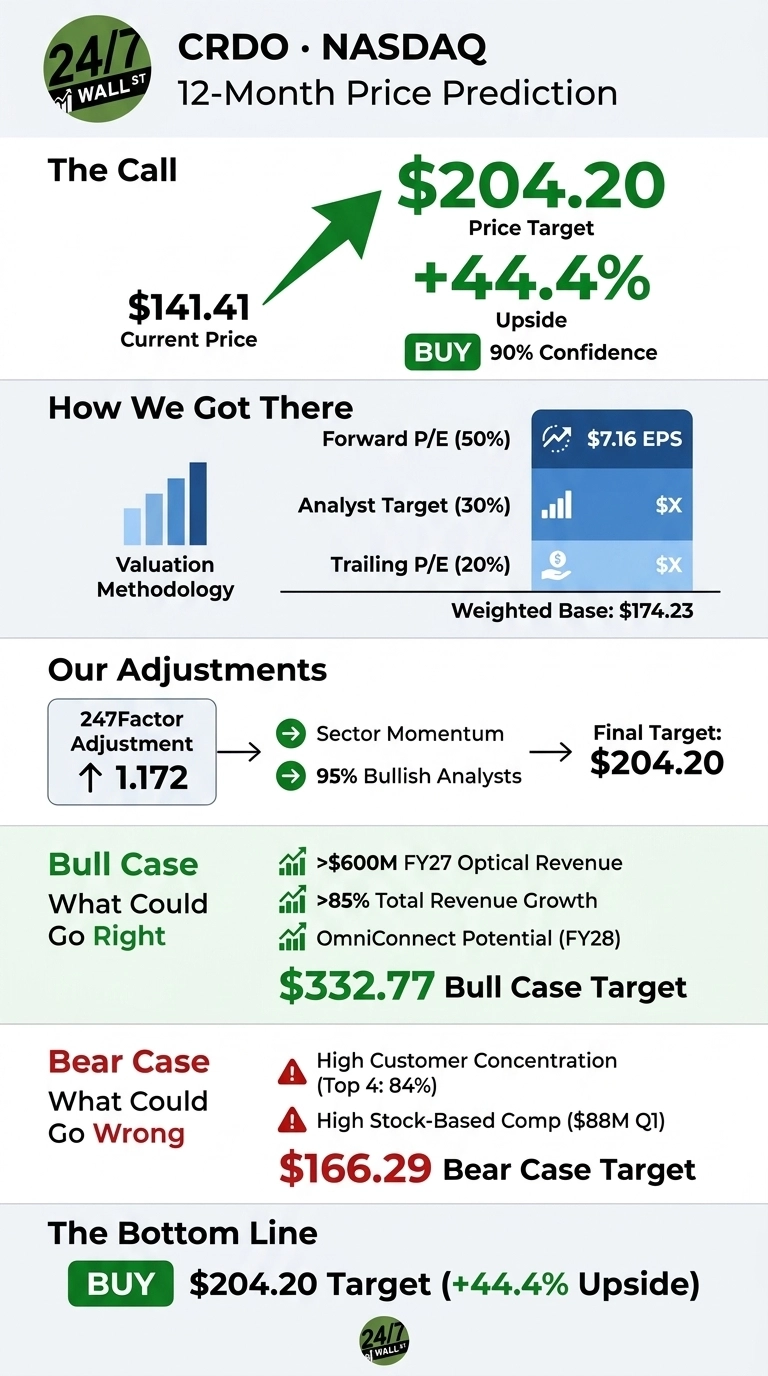
Most AI attention goes to NVIDIA (NASDAQ:NVDA | NVDA Price Prediction), but every GPU cluster also depends on the cables, optics and retimers that connect it. Credo Technology (NASDAQ:CRDO) sells that connectivity layer. The 24/7 Wall St. price target for Credo is $204.20, implying 44.4% upside from the $141.41 close.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $141.41 |
| Price Target from 24/7 Wall St. | $204.20 |
| Upside/Downside | 44.4% |
| Recommendation | BUY |
| Confidence Level | 90% |
Our model gives 90% confidence to this call. Credo has beaten EPS estimates for 8 consecutive quarters, yet the stock has fallen sharply, and that gap between results and price drives the buy rating.

Strong Earnings, Weak Stock: Credo’s Steep Fall
Shares are down 32.3% over the past month, 0.39% over the past week and 5.5% year to date. The stock is 54% below its 52-week high of $308.67 and 64% off its low of $86.48.
Q1 fiscal 2027 revenue reached $479 million, up 114.7% year over year, and non-GAAP EPS of $1.20 exceeded the $1.17 consensus.
Even so, the stock fell after that report on concerns about customer concentration and valuation. Then it lost more ground in a broad AI infrastructure selloff in November. Management guided Q2 revenue to $525M-$535M, with results due in early December.

Why Bulls See $332 Ahead
Management expects more than $600 million of optical revenue in fiscal 2027, total growth above 85% and a non-GAAP net margin “in the vicinity of 50%”. OmniConnect could add thousands of dollars of Credo content per GPU starting in fiscal 2028.
Of 20 covering analysts, 19 rate the stock a buy or strong buy. Their consensus target of $284.05 is about 101% above where the stock trades now. The bull case reaches $332.77.

Customer Concentration Is the Risk Worth Watching
In Q1, the four largest customers made up for 33%, 28%, 13% and 10% of revenue. Stock-based compensation reached $87.98 million.
GAAP gross margin guidance of 62.9%-64.9% trails the non-GAAP range of 67%-69%, mostly because of acquisition amortization, which is a non-cash charge tied to the photonics deal that brought in Credo’s first PIC revenue. Today’s price remains below the bear case of $166.29.

How Credo Stacks Up Against Astera Labs, Broadcom and Marvell
| Company | Market Cap | Latest Quarter Revenue Growth |
|---|---|---|
| Credo | $26.58B | 114.7% |
| Astera Labs (NASDAQ:ALAB) | $40.36B | 153.67% |
| Broadcom (NASDAQ:AVGO) | $1.65T | 85.5% |
| Marvell Technology (NASDAQ:MRVL) | $148.2B | 36.55% |
Astera Labs is the closest pure-play comparison because it also sells retimers and cable modules to hyperscalers. It trades at a high trailing P/E of 184.
Broadcom competes in AI networking, and its AI semiconductor revenue rose 221%.
Marvell overlaps with Credo in optical interconnect, and its non-GAAP gross margin of 58.9% trails Credo’s 68%.
Credo’s Valuation Case Rests on 20x Forward Earnings
The 24/7 Wall St. price target of $204.20 comes with a buy rating at 90% confidence.
The main reason is valuation: about 20x forward earnings for a company more than doubling its revenue. The case gets stronger if December results confirm the optical growth and new customers. It gets weaker if one of the largest customers cuts orders.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $137.57 |
| 2027 | $213.51 |
| 2028 | $248.86 |
| 2029 | $318.63 |
| 2030 | $353.81 |
The estimates rest on Credo continuing to execute its current strategy. Hyperscaler spending changes or a successful OmniConnect launch could move results well above or below this path.
The larger point is that the AI expansion runs on more than GPUs, and the power, cooling, and connectivity suppliers behind it are the subject of a free report on seven AI infrastructure names that aren’t chipmakers.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.