3 REIT Giants Paying Big Dividends, Led by VICI’s 7.6% Yield

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Real estate investment trusts have to pay out most of their taxable income, so the biggest ones work as income machines by design. VICI Properties (NYSE:VICI), W. P. Carey (NYSE:WPC), and Simon Property Group (NYSE:SPG) have one thing in common: each raised its payout within the past year and pays it from recurring cash flow. VICI leads the group with a forward yield of about 7.6%. Earnings per share can mislead with REITs because of depreciation and other non-cash charges, so safety below is measured with funds from operations (FFO) and adjusted funds from operations (AFFO). REITs report these cash flow measures in place of earnings.
VICI Properties: Ultra-High-Yield Casino Rent on 39-Year Leases
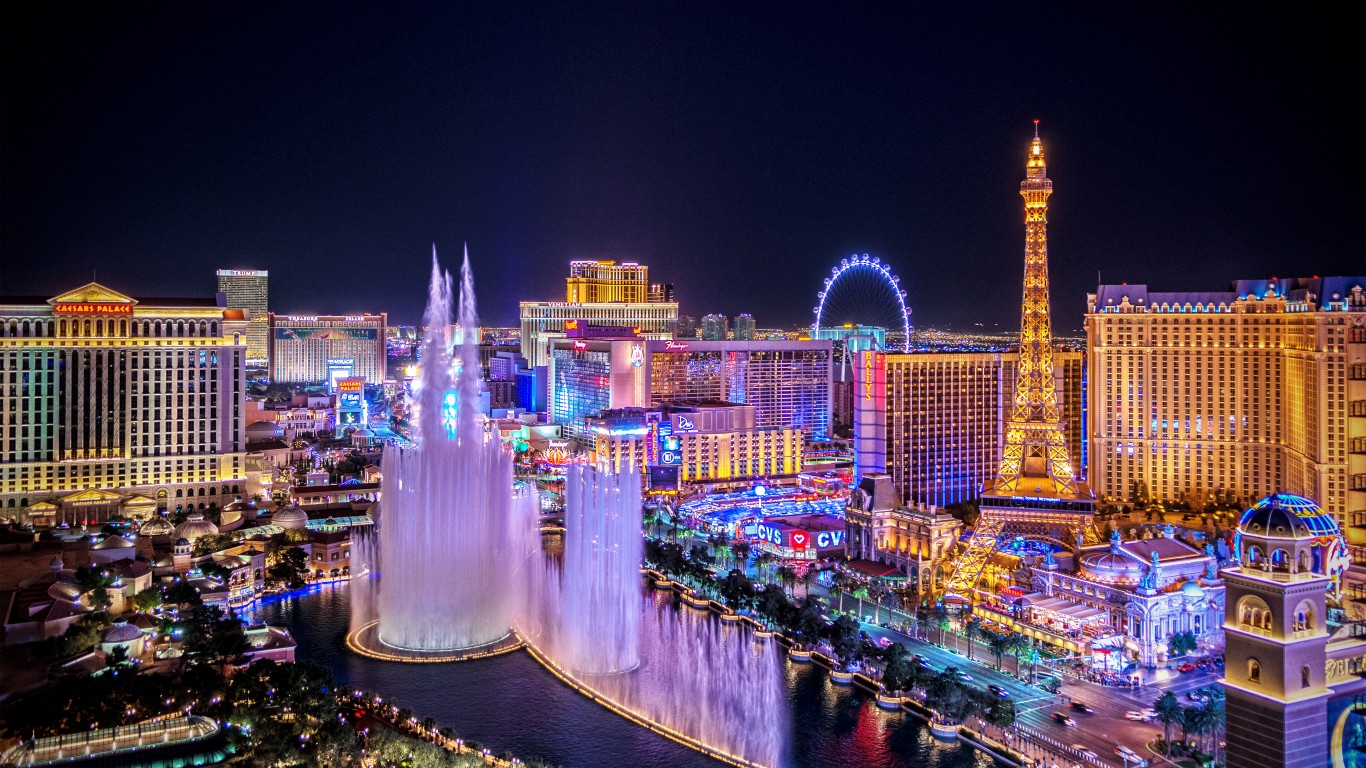
VICI owns casino and experiential properties leased to operators under long triple-net master leases, so tenants cover taxes, insurance, and maintenance. The portfolio is 100% occupied with a 39.6-year weighted average lease term. At a recent price of $24.35 and an annualized forward dividend of $1.84, the yield is about 7.6%, which puts it in ultra-high-yield territory.
Dividend safety (AFFO): Management raised full-year AFFO guidance to $2.47 to $2.48 per diluted share[1], so the annualized dividend uses roughly 74% of the low end. In the third quarter, AFFO rose 7.5%[1] to $685.20 million, well above the roughly $506.3 million in dividends declared. GAAP diluted EPS fell to $0.31[1]. The drop came from a $458.03 million[1] non-cash credit loss allowance charge, a good example of why AFFO tells the cash story better. On the balance sheet, total assets of $48.06 billion[1] sit against total liabilities of $18.62 billion. The company refinanced its upcoming maturities with a $1.75 billion[1] investment-grade notes offering at a 5.42% weighted average rate.
Track record: The quarterly dividend most recently rose from $0.45 to $0.46, a 2.2%[1] increase. The dividend history shows a raise every year from 2020 through 2026. Edward Pitoniak was VICI’s chief executive. At the time of the filing, he called it the “9th consecutive annual dividend increase since our IPO almost nine years ago.”[1]
Bull case: Most leases carry 2.0% annual escalators, and some are tied to CPI, so rent rises on a schedule whatever the economy does. New tenants and a deal pipeline (Club Med St. Croix, Canyon Ranch and Caesars right-of-first-refusal assets) add growth on top. The board also approved a $2.0 billion[1] buyback. Shares are down 11.9% over the past year, which is why the yield now looks so rich next to guidance that keeps moving up.
Risk: Tenant concentration. Caesars Entertainment (NASDAQ:CZR | CZR Price Prediction) accounts for about 38% of annualized rent and MGM Resorts (NYSE:MGM) for about 32%. If either one runs into trouble during a slowdown in consumer gaming spending, a large share of VICI’s rent would be exposed.
W. P. Carey: A Reset Dividend That Has Climbed Every Quarter
W. P. Carey owns net lease properties in the U.S. and Europe. Under a net lease, the tenant pays most property costs, which leaves the landlord with steady rent. Occupancy is 98.5%[2], and more than 99% of base rent comes from leases with contractual increases. With an annualized dividend of $3.80 and a price of $66, the yield is about 5.8%. It is a high-yield stock that sits just below the ultra-high threshold.
Dividend safety (AFFO): Full-year AFFO guidance was raised to $5.23 to $5.29 per diluted share[3], so the dividend uses roughly 73% of the low end. Third-quarter AFFO came in at $1.33[3] per share against a $0.950 quarterly payout. Leverage is moderate, with net debt at 5.5x adjusted EBITDA (5.1x counting unsettled forward equity). 95% of debt is fixed-rate at an average rate of 3.2%, and about $691 million of forward equity is available.
Track record: W. P. Carey cut its dividend lower at the end of 2023. The payout went from $1.071 in late 2023 to $0.86 after the company sold office properties. It has been raised every quarter since and now stands at $0.95, up 4.4%[3] year over year. Because of that cut, its run of rising payouts dates to the cut, and that post-reset record is clean.
Bull case: Growth is speeding up. The chief executive at the time of the filing, Jason Fox, said: “AFFO per share growth will approach 6% this year.”[3] Year-to-date investments total $1.6 billion at a 7.5% going-in cap rate, with an average lease term of 19 years. Same-store rent grew 2.6%[3] on a contractual basis, and roughly 47.8% of base rent is tied to CPI, which gives income investors some inflation protection.
Risk: Interest rates. Rising rates make the deal market less predictable and increase borrowing costs. W. P. Carey replaced maturing 4.250%[3] notes with $350 million of 5.200% notes due 2036, which shows how refinancing slowly narrows the spread between what it pays to borrow and what its properties earn.
Simon Property Group: Biggest Per-Share Check From Trophy Malls
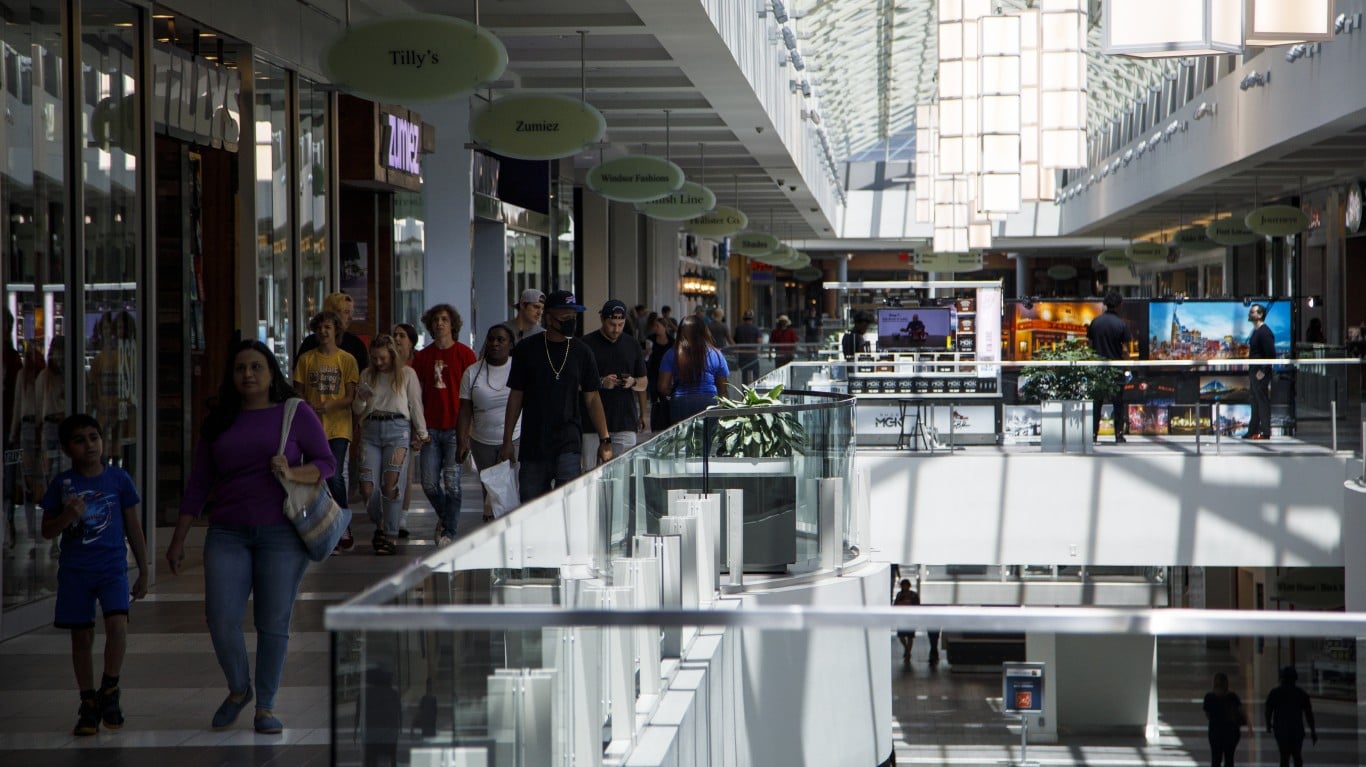
Simon owns malls, Premium Outlets, and Mills centers, and its U.S. malls and outlets are 96.0%[4] occupied. The board just raised the quarterly dividend to $2.30, payable December 31, for an annualized $9.20. At $231.38, that works out to about a 4.0% yield. That is the lowest percentage yield of the three, mainly because shares are up 29.18% this year. In dollars per share, it is the biggest payout in the group by a wide margin.
Dividend safety (FFO): In the second quarter, Simon reported FFO of $3.29[4] per diluted share against a $2.25 dividend, a payout of roughly 68%. Real Estate FFO per share grew 7.9%[4] year over year. Liquidity is strong: Simon extended its $5.0 billion revolver to June 2030 at SOFR plus 65 basis points and sold $800 million[5] of five-year notes at 4.30%. It still had enough cash to buy back $211.4 million[4] of stock and units in the second quarter.
Track record: Simon cut its dividend in 2020, from $2.10 to $1.30, and has raised it repeatedly since. The new $2.30 payout is above the pre-cut level and about 4.5% higher than a year ago.
Bull case: The malls are performing well. Base minimum rent rose 6.3%[4] to $62.42 per square foot. Trailing retailer sales climbed 13.9%[4] to $838 per square foot, and domestic property NOI grew 8.5%. The Taubman acquisition and a $1.06 billion[5] redevelopment pipeline (first-quarter figures) aim to support dividend growth with a 9% stabilized return.
Risk: Retail traffic. Simon’s rent ultimately depends on shoppers walking into stores. A decline in consumer discretionary spending, combined with ongoing e-commerce competition, could lead to tenant bankruptcies and lower occupancy.
How These Three REIT Dividends Fit Together
VICI offers the highest yield, backed by decades-long leases. W. P. Carey has a cut dividend. It has risen every quarter, and Simon pays the largest per-share dividend from a portfolio of top-tier malls. All three cover their payouts with cash flow to spare, at roughly 74%, 73% and 68% of their respective AFFO or FFO. These REIT dividends tend to draw income investors. They focus on rising quarterly cash, though share prices can swing with interest rates, and the mostly ordinary-income distributions face less tax drag inside tax-advantaged accounts.
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.