NVIDIA Doubled Its Revenue in Its First Quarter Without Huang. Here’s Our Price Target.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
The 24/7 Wall St. price target for NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) is $201.11. This points to 29.36% upside from the $155.46 close, with a model rating of buy and high confidence.
24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $155.46 |
| Price Target from 24/7 Wall St. | $201.11 |
| Upside/Downside | 29.36% |
| Recommendation | BUY |
| Confidence Level | 90% |

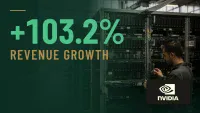
NVIDIA just posted third-quarter fiscal 2027 revenue of $115.84 billion[1], up 103.21% year over year.
It was the first earnings report since Jensen Huang resigned. The stock is priced for leadership risk, while our model is priced on earnings, and the upside comes from the space between those two views.
A Record Quarter Collides With a Leadership Shock
On the call, Chairman Harvey Jones said Huang resigned after disclosure of “personal behavior inconsistent with the company’s code of conduct, standards, and cultural norms.”[2]
Longtime CFO Colette Kress is serving as interim CEO while the board searches for a permanent chief executive. Shares fell 7.95% over the past week and 27.4% over the past month, and they are down 16.45% year to date. The stock now trades near its 52-week low of $148.80, well below the $243.37 high.
The operating results beat expectations. Revenue exceeded the $108.73 billion[1] consensus, and non-GAAP EPS came in at $2.68 against an expected $2.4712. Data Center revenue reached $107.60 billion[1].
Vera Rubin brought in nearly $20 billion[2] in its first production quarter. Management guided fourth-quarter revenue to $130 billion, plus or minus 3%[1] and raised its fiscal 2028 growth outlook to approximately 75%[2]. Kress summed it up: “From a business perspective, it’s business as usual.”[2]
Why Bulls See $264 or Higher
In our bull case, the stock reaches $264.48. Cloud industry backlog climbed to $2.5 trillion[2] from $2 trillion three months earlier, and management says demand still exceeds supply. AI Clouds, Industrial and Enterprise revenue rose 195%[1].
The company also has $227.3 billion[1] left in buyback authorization, which it plans to use through fiscal 2028. Wall Street remains supportive, with 10 Strong Buy ratings, 49 Buy ratings and a consensus target of $267.65.

Risks That Could Cap the Rebound
The bear case comes to at $180.95. Without a permanent CEO and with the board investigation still open, headline risk remains. Guarantees amounted $118 billion[1], and three customers accounted for 14%, 11%, and 11% of revenue.
Investor Steve Eisman also warned that AI neocloud stocks face “big trouble” from the NVIDIA fallout. Fourth-quarter gross margin is guided down to 71%-72%[1]. Management, however, calls that level the bottom and expects 72% to 73%[2] in fiscal 2028 as the Rubin ramp matures.

How NVIDIA Stacks Up Against AMD and Broadcom
AMD (NASDAQ:AMD) competes head-on with NVIDIA in GPUs through its Instinct MI450 chips. At roughly 190x trailing earnings, AMD is cheaper than NVIDIA at about 31x, even though AMD’s revenue grew more slowly.
Broadcom (NASDAQ:AVGO) goes after the same hyperscaler budgets with custom accelerators. Its AI semiconductor revenue jumped 221%, though from a much smaller base. Next to these two peers, our target looks conservative.
| Company | Latest Quarter Revenue | YoY Growth | Next-Quarter Guide |
|---|---|---|---|
| NVIDIA | $115.84B[1] | 103.21%[1] | $130.0B[1] |
| AMD | $13.377B | 44.68% | $17B |
| Broadcom | $29.591B | 85.5% | $34.8B |
Earnings Power Outweighs the Boardroom Noise
The 24/7 Wall St. price target of $201.11 carries a model rating of buy and high confidence. A business that more than doubled revenue during a leadership crisis is what drives this call.
The bull thesis gets stronger if the board names a credible permanent CEO and Rubin keeps ramping. It weakens if the investigation widens or customers lose access to financing.
Our model projects NVIDIA trading at these levels in the coming years if current trends hold.
| Year | Price Target from 24/7 Wall St. |
|---|---|
| 2026 | $201.11 |
| 2027 | $208.33 |
| 2028 | $246.55 |
| 2029 | $279.87 |
| 2030 | $302.96 |
These projections assume NVIDIA keeps executing on its roadmap. Major upside or downside could come from who becomes CEO and from export-control policy.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.