Jim Cramer Says Cardinal Health Is “the Stock That Is Made for This Moment”

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
Jim Cramer used his “Stop Trading” segment on CNBC on November 17, 2026, to spotlight a company most investors rarely think about. “I want to present a stock that is literally the stock that is made for this moment. It’s called Cardinal Health,” he said, calling it “a company that distributes pharmaceuticals and they do some health care manufacturing, pharmaceutical packaging.”
The market has already rewarded Cardinal Health (NYSE:CAH | CAH Price Prediction). Shares finished at $272.34 on November 19, up 33.76% year to date. They slipped 2.09% over the past week and sit about 4.9% below the 52-week high of $286.29.

How a Drug Middleman Earns Steady Profits
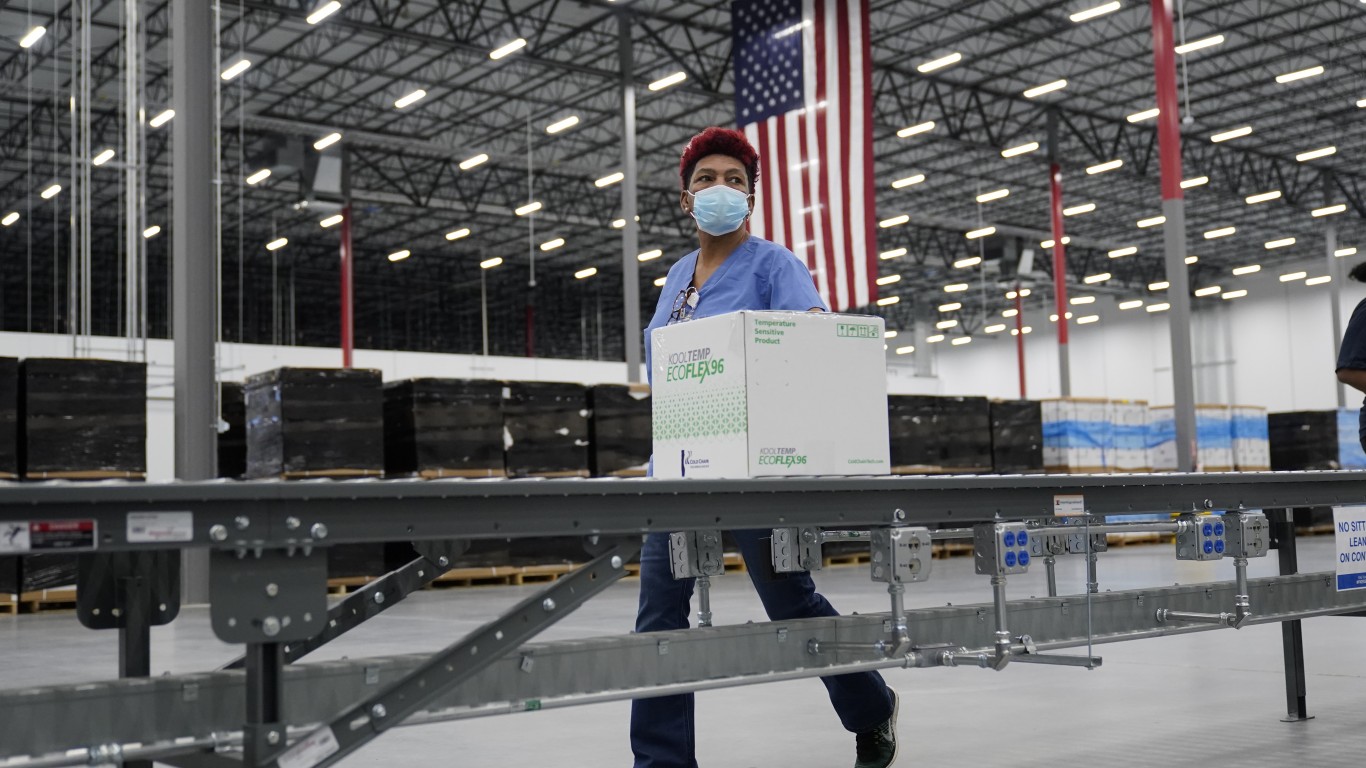
Cardinal buys branded, specialty, and generic drugs from manufacturers and delivers them to pharmacies, hospitals, and physician practices. It earns a thin spread on huge volume, collects fees from drugmakers, and pressures generics’ margins through Red Oak Sourcing, a venture it runs with CVS Health (NYSE:CVS). It also makes medical products, runs nuclear pharmacies and sells home-health supplies. With McKesson (NYSE:MCK) and Cencora (NYSE:COR), it serves drugmaker AbbVie (NYSE:ABBV), accounting for substantially all of AbbVie’s U.S. pharmaceutical sales in 2025.
People fill prescriptions in any economy, and that’s the heart of the defensive case. The stock’s beta of 0.521 shows it has historically moved about half as much as the broader market.
Blowout Quarter Backs Up the Pitch
Fiscal Q1 2027 results on November 5 beat on both lines. Non-GAAP EPS of $3.26 exceeded the $2.94 consensus and grew 28%. Revenue of $67.51 billion beat the $66.51 billion estimate. Pharma segment profit rose 17% to $783 million[1], specialty grew 18%, and GLP-1 drugs added roughly 500 basis points of revenue growth.

Management raised fiscal 2027 non-GAAP EPS guidance to $12.80-$13.00 from $12.40-$12.60 and renewed CVS through June 2032[1]. CEO Jason Hollar said Cardinal renewed contracts representing “nearly two-thirds of our enterprise revenue”[1] over the prior year. The EPS beat streak now stands at five straight quarters.
What Investors Pay Now for Cardinal’s Steady Growth
The stock trades at about 22x forward earnings. The trailing P/E of 36 looks high because GAAP results carry acquisition charges; Q1 GAAP diluted EPS was $2.38. The $0.5158 quarterly dividend yields roughly 0.76%, so buybacks carry most of the capital return. Cardinal completed a $500 million accelerated repurchase in Q1, and its August 8-K showed total authorization of $6.4 billion[2]. Analysts lean bullish, with 3 Strong Buy, 11 Buy and 3 Hold ratings and a $300.80 average target.

Risks That Could Crack the Defensive Label
- Thin margins: Trailing operating margin is just 1.33%, leaving little room for pricing errors.
- Customer concentration: CVS supplied 28% of fiscal 2026 revenue. OptumRx, once 17% of revenue, walked in June 2024.
- Drug pricing policy: IRA list-price cuts created a 400 basis point[1] revenue drag. Hollar said, “Any policy changes will take time, and we would expect to be manageable.”[1]
- Litigation: Filings flag DOJ investigations under the Anti-Kickback Statute and False Claims Act, plus tariff uncertainty and generic deflation.
Management also expects earnings growth to moderate in the second and third quarters[1], which could make upcoming comparisons look softer.
Does Cramer’s Case Hold Up for Long-Term Investors?
On fundamentals, largely yes. Locked-in renewals, double-digit specialty growth, and aggressive buybacks give Cardinal unusual earnings visibility for a business that runs on pennies per dollar. Price is the sticking point: shares started the year at $203.60, so much of the “moment” is already reflected in a 22x multiple for a distributor. Long-term holders get a durable compounder with slower, easy gains ahead. Keep an eye on the stock around the Q2 slowdown, the Diabetes Health acquisition expected to close in Q3 FY27, and any Washington moves on drug pricing. Cardinal’s investor relations site posts each update.
Contact [email protected] for any questions or corrections.
Chris Lange is a financial and geopolitical writer with more than a decade of experience covering a myriad of topics. He has published thousands of articles for 24/7 Wall St., with past coverage focused heavily on stocks, IPOs, healthcare, defense, global affairs, and technology.
His work has been quoted, or referenced by a number of outlets including Business Insider, USA Today, Yahoo Finance, MSN, The Motley Fool, and many other publications. A graduate of Southwestern University, he studied business with a focus on investments and has previous experience in banking and startups.
When not reading or writing the news, he is following his passion for Lacrosse, playing chess, or building solar projects with his dad.