The Smart Money AI Trade Could Look Very Different in 2027

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
AI accelerators depend on memory from Micron Technology (NASDAQ:MU | MU Price Prediction), and that role has changed the business. Revenue for fiscal 2026 reached $133.19 billion, up 256.33%, and the non-GAAP gross margin hit 87% in the fourth quarter. According to Sanjay Mehrotra, “we expect an even stronger fiscal 2027.”
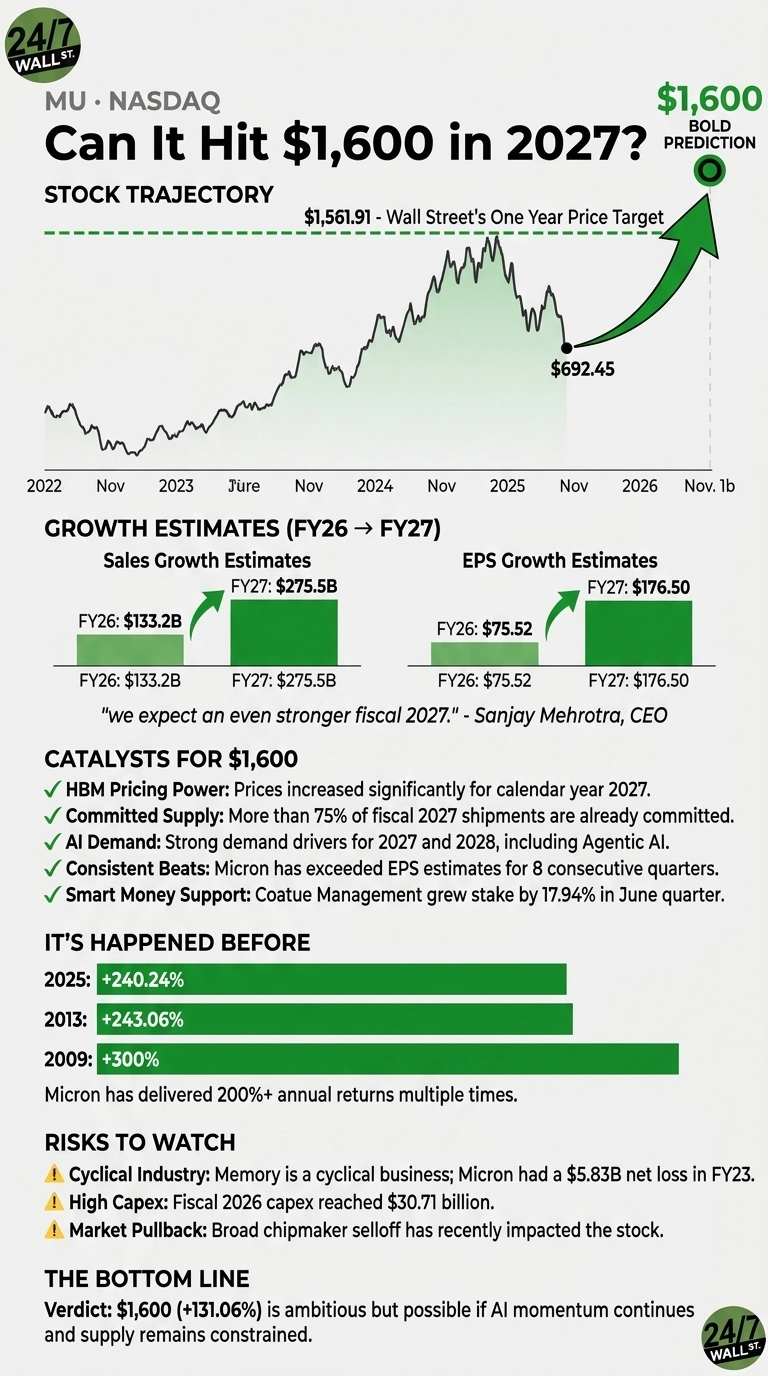
Shares are still up 142.81% year-to-date. A broad chipmaker selloff, however, has knocked the stock down 25.88% in a week to $692.45. Micron needs to do the following to reach $1,600 in 2027.

Wall Street Already Expects Micron to More Than Double
Analysts’ consensus price target is $1,561.91, which implies 125.56% upside. The stock carries 9 Strong Buy ratings and 36 Buy ratings. Fiscal 2027 EPS estimates have risen to $176.5017 from $153.8669 90 days ago, with 28 upward revisions in the past 30 days. Analysts expect fiscal 2027 revenue of $275.5 billion.

Micron Only Needs a 9x Multiple to Reach $1,600
Micron currently trades at about 4x fiscal 2027 estimates. At $1,600, that multiple would rise to about 9x, still far below the S&P 500’s forward multiple of roughly 21x to 23x. Investors are pricing Micron as if this cycle is about to top out. A modest rerating would be enough to get the stock to $1,600.

How Micron could get to $1,600.
- Consistent beats: Micron has exceeded EPS estimates for 8 consecutive quarters. For the first quarter of fiscal 2027, management guided to $38.15 in non-GAAP EPS on $61.5 billion in revenue.
- Committed supply: More than 75% of fiscal 2027 shipments are already committed. The company has 26 strategic customer agreements running through 2030, and management said it has “no line of sight to when supply and demand balance.”
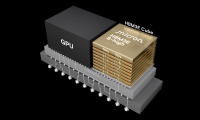
- HBM pricing power: Micron has co-designed a custom HBM4E product with NVIDIA (NASDAQ:NVDA). HBM pricing was increased significantly for calendar year 2027.
- Smart money support: Coatue Management grew its stake by 17.94% in the June quarter. Situational Awareness held a $5.57 billion position.

Micron Has Posted Gains This Big Several Times Before
Reaching $1,600 would take a gain of 131.06%. Micron has exceeded that level in several years. Shares returned 300% in 2009, 243.06% in 2013 and 240.24% in 2025. Memory is a cyclical business, though.
In fiscal 2023, Micron posted a net loss of $5.83 billion, and fiscal 2026 capex reached $30.71 billion. (We studied what the biggest early-stage tech winners had in common before their runs and put the pattern in a free playbook here.)
Is $1,600 Realistic? Here’s My Take
Micron would need to climb 131.06% to hit $1,600. The setup is strong: Wall Street’s target sits near that level, estimates keep rising, the beat streak is intact and most fiscal 2027 supply is already committed.
A deeper chip selloff or an earlier-than-expected peak in the memory cycle could delay the move. Such gains don’t happen every year, but we’ve outlined the case for how Micron could see outsized returns in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.