Micron’s Next $100 Billion Growth Opportunity Could Surprise Wall Street

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

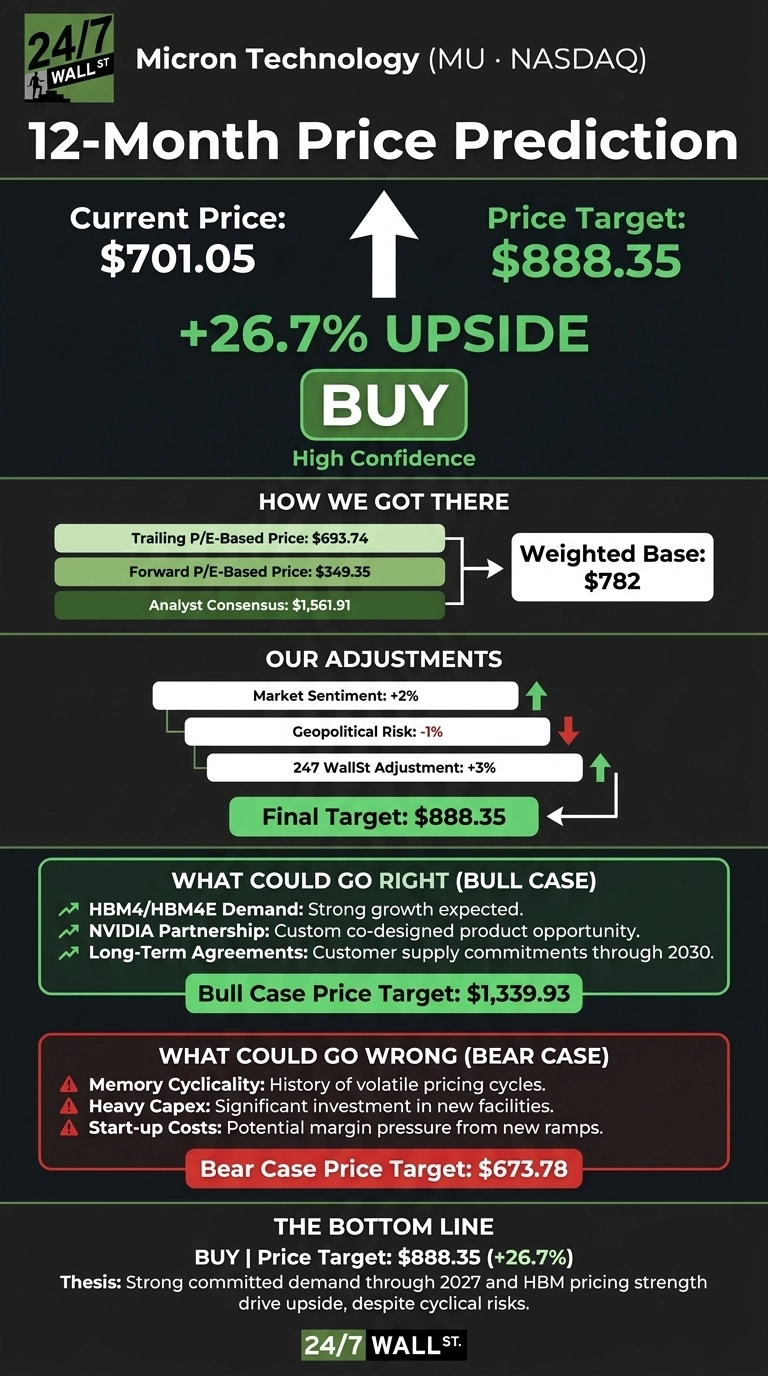
Our 24/7 Wall St. price target for Micron Technology (NASDAQ:MU | MU Price Prediction) is $888.35. From the current price of $701.05, that works out to 26.7% upside. Our model rates the stock a buy with high confidence.

24/7 Wall St. Price Target Summary
| Metric | Value |
|---|---|
| Current Price | $701.05 |
| Price Target by 24/7 Wall St. | $888.35 |
| Upside | 26.7% |
| Recommendation | BUY |
| Confidence Level | 90% |
Micron has already crossed the $100 billion revenue mark, with fiscal 2026 sales of $133.188 billion[1].
The next leg of growth rests on HBM pricing, multi-year customer contracts and a supply shortage that management expects to last through 2028. After the recent pullback, shares trade at about 4x forward earnings.

A 20% Monthly Slide Follows a Record Fiscal Year
MU is down 3.32% over the past week and 20.23% over the past month. It is still up 145.82% year to date. The stock sits 44.1% below its 52-week high of $1,254.61 and far above its low of $192.37. The selling picked up in November, when doubts about data-center spending after the U.S. midterms hit the stock, and Barron’s reported that Micron dropped again on November 17.
The business is still growing quickly. Fiscal Q4 revenue came in at $54.229 billion[1], ahead of the $50.972 billion consensus. Non-GAAP EPS of $33.42[1] beat the $31.3542 estimate, and non-GAAP gross margin reached 87%. For fiscal Q1, management guided to $61.5 billion[1] in revenue and $38.15 in non-GAAP EPS.
Why Bulls See $1,339 Ahead
The bull case is $1,339.93, or 91.1% upside. Micron has more than 75%[2] of its fiscal 2027 shipments committed. It has raised HBM pricing for calendar 2027, is co-designing a custom HBM4E chip with NVIDIA (NASDAQ:NVDA), and holds 26[2] strategic customer agreements that run through 2030.
Chief operating officer Manish Bhatia said, “We really don’t have line of sight to when supply and demand balance.”[2] Analysts agree: 45 rate the stock Buy or Strong Buy, against one Strong Sell.

What Could Break the Memory Supercycle
Our bear case is $673.78, a 3.9% decline. Memory prices move in cycles, and fiscal 2026 capex reached $30.712 billion[1]. Start-up costs at new plants could also eat into margins.
Meanwhile, free cash flow of $62.308 billion[1] more than covered that capex. About three-quarters[2] of revenue under the customer agreements has a defined pricing model, which makes downturns less severe.
How Micron Stacks Up Against SanDisk and Western Digital
SanDisk (NASDAQ:SNDK) is listed as a competitor in Micron’s 10-K. Its P/E of 10 is close to Micron’s trailing 10x. Micron adds HBM exposure, which SanDisk lacks.
Western Digital (NASDAQ:WDC) also benefits from AI storage demand, but its hard-drive margins are much lower. Micron leads both peers on quarterly revenue growth and gross margin.
| Company | Latest Quarter Revenue Growth (YoY) | Gross Margin |
|---|---|---|
| Micron | 379.27%[1] | 87.0%[1] |
| SanDisk | 377.95% | 85.0% |
| Western Digital | 55.46% | 58.1% |
Committed Fiscal 2027 Demand Anchors Micron’s Upside
The 24/7 Wall St. price target of $888.35 carries a buy rating with 90% confidence. Most of fiscal 2027 demand is already committed, which tips the scale.
The key signal to monitor is whether HBM price increases hold through calendar 2027. A pullback in hyperscaler data-center spending would weaken the case.
Here is where the 24/7 Wall St. price target model projects Micron could trade, assuming current trends hold.
| Year | Price Target by 24/7 Wall St. |
|---|---|
| 2026 | $676.47 |
| 2027 | $888.35 |
| 2028 | $1,044.77 |
| 2029 | $1,185.46 |
| 2030 | $1,336.46 |
The projections rest on Micron continuing to execute on its current strategy. A faster HBM4E ramp could drive results above them, and an early end to the memory shortage could pull them below.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.