Broadcom, Nvidia, and Micron Could Be Setting Up for a Massive AI Rally Before Year End

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
The AI trade cooled into the holidays, and that pullback may be the setup for a rally. NVIDIA (NASDAQ:NVDA | NVDA Price Prediction) is down 16.45% year-to-date, even though revenue rose 103.2%[1] in its latest quarter. Broadcom (NASDAQ:AVGO) is 0.76% lower for the year. For its part, Micron Technology (NASDAQ:MU) is still up 149.81% despite an 18.94% slide over the past month.
NVIDIA interim CEO Colette Kress said: “Our momentum is real. Our demand is accelerating. Our supply is growing.”[2] Below, I lay out how NVIDIA could reach $300, Broadcom $600, and Micron $1,600 in 2027.

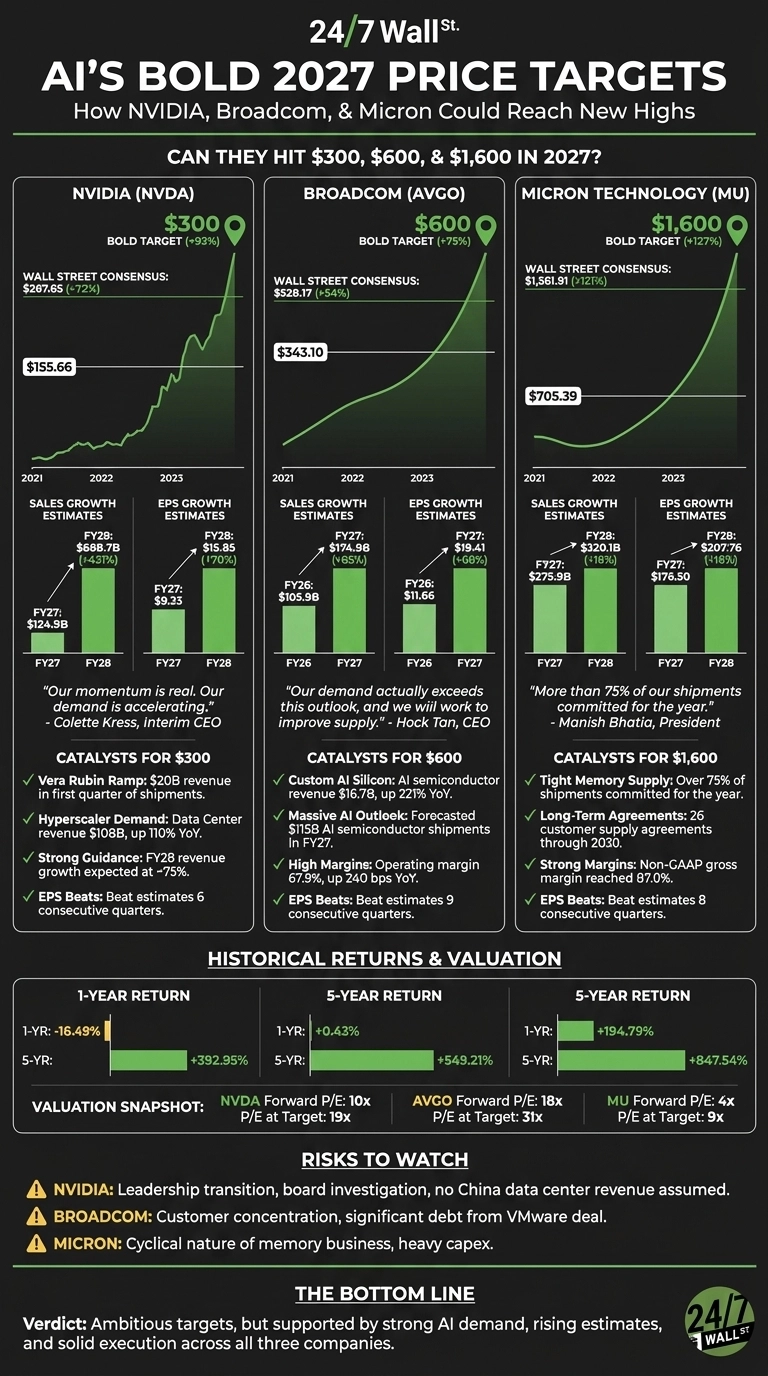
Wall Street Already Sees Big Upside in All Three
Consensus price targets sit at $267.65 for NVIDIA (72% upside), $528.17 for Broadcom (54%), and $1,561.91 for Micron (121%).
Earnings estimates are rising too. Ninety days ago, analysts expected $12.8206 in fiscal 2028 EPS from NVIDIA. Today the estimate is $15.8537. Micron’s fiscal 2027 estimate climbed from $155.7946 to $176.5017.
All three companies keep beating EPS estimates. NVIDIA has done it 6[1] quarters in a row, Micron 8, and Broadcom 9[3], so actual results could land above these forecasts.

Here’s the Valuation Math Behind $300, $600, and $1,600
| Stock | Price | Forward P/E | Bold Target | P/E at Target |
|---|---|---|---|---|
| NVIDIA | $155.66 | 10x | $300 | 19x |
| Broadcom | $343.10 | 18x | $600 | 31x |
| Micron | $705.39 | 4x | $1,600 | 9x |
Even at their targets, NVIDIA and Micron would trade at modest multiples for their growth rates. Broadcom’s 31x is a premium, but Hock Tan expects EPS to top $30 in fiscal 2028[4].
What Could Push These Stocks Higher?
- Vera Rubin: In its first quarter of shipments, NVIDIA’s Rubin platform brought in nearly $20 billion[2]. Management guided for $130 billion[1] in fourth-quarter revenue and expects fiscal 2028 revenue to grow about 75%[2].
- Custom silicon: Broadcom’s AI revenue reached $16.7 billion[3], up 221%, and it guided for $21.7 billion next quarter. Tan expects about $115 billion[4] in fiscal 2027, adding: “Our demand actually exceeds this outlook.”
- Tight memory supply: Micron’s gross margin reached 87%, and more than 75% of its shipments for the year are already committed. It has 26 long-term customer supply agreements running through 2030.
Recent Trading Shows These Moves Are Possible
Reaching these targets would take gains of 93% for NVIDIA, 75% for Broadcom, and 127% for Micron. Micron has gained 194.79% over the past year. NVIDIA hit a 52-week high of $243.37, and Broadcom topped out at $493.32.
$300, $600, and $1,600 Are Stretch Goals Within Reach
The challenges are real. NVIDIA is searching for a new CEO, faces a board investigation, and assumes no China data center compute revenue[1] in its guidance.
Broadcom depends on a handful of customers, and memory remains a cyclical business. Still, rising estimates, long beat streaks, and low forward multiples give all three stocks room to run.
The same data center expansion also lifts the power, cooling, and networking suppliers sitting one layer away from the chips (we covered seven of them in a free report on AI infrastructure). Such returns shouldn’t be expected every year, but we’ve outlined the path for how NVIDIA, Broadcom, and Micron could see outsized returns in 2027.
Contact [email protected] for any questions or corrections.
Vandita Jadeja is a financial publisher with over a decade of experience writing about financial topics, including investment, savings, retirement, insurance and banking. Vandita is a Chartered Accountant who loves to debunk financial concepts for readers.
Her work has appeared on sites that include The Motley Fool, InvestorPlace, and Benzinga. She covers investing and focuses on stock picks and price prediction for 24/7 Wall St.
When not looking for the next stock investment opportunity, she can be found traveling, reading, chasing sunsets and enjoying her iced latte.