A $1 Million VOO Holder Owes Tax on $10,450 in Dividends He Never Saw Because He Reinvested Them
Your broker reinvests every VOO dividend automatically, so you assume no tax event occurred. The IRS disagrees, and the bill it sends in April on money you never actually received may surprise even seasoned investors.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
You never saw the cash. Your broker swept every dividend straight back into more shares. In April, the 1099-DIV still shows up, and the IRS still wants its cut. That is the quiet trap sitting inside every taxable brokerage account holding the Vanguard S&P 500 ETF (NYSEARCA:VOO).
Ghost Income the IRS Still Taxes
Run the math on a $1 million position. At $707.47 a share (as of September 23, 2026), that buys roughly 1,413 shares. VOO paid $7.3456 per share in trailing 12-month distributions, which lands the holder near $10,383 in dividends over the past year. The headline’s $10,450 figure is well within the annualized forward run rate, which implies $7.8488 per share.
Every penny of that was reinvested into more VOO through the broker’s dividend reinvestment plan. None of it hit a checking account. All of it is taxable in the year received. VOO’s payouts are largely qualified dividends. A high-income single filer faces a 20% qualified-dividend rate plus the 3.8% Net Investment Income Tax, for a combined 23.8% federal rate. On $10,450, that is a $2,487 federal tax bill on money the investor never touched. Even a middle-bracket filer at 15% owes $1,567.50.
A Tax Bill on Money You Never Touched
This is the cost the fund factsheet does not print. VOO’s expense ratio is genuinely tiny—0.03%—working out to approximately $2 per $10,000 over six months. On a $1 million book, the fund charges roughly $300 a year. The DRIP tax bill dwarfs the fund fee by roughly 5 to 8 times, depending on your tax bracket.
Compound the drag. If a mid-bracket investor writes a $1,568 check every April on those reinvested dividends, and that same $1,568 could have grown at 8% inside a sheltered account, the 20-year opportunity cost lands near $71,755. That is the “hidden” number, and it reflects what the account placement of VOO costs you.
Where This Cost Hides on the Factsheet
Vanguard’s own June 2026 shareholder report confirms that VOO is nearly a model tax-efficient index vehicle. Portfolio turnover was 1%, meaning almost no internal churn to generate capital-gains distributions. Net assets stood at $1.675 trillion, so spreads are tight and the premium/discount to NAV is negligible. The fund holds 519 stocks with 38.0% in Information Technology. There is no leverage decay, no options overlay, no closet-index premium.
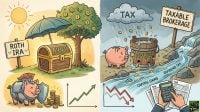
The tax leakage comes from the account type in which you hold the fund. Reinvesting inside a taxable brokerage triggers the 1099-DIV every year. Reinvesting inside a Roth IRA or 401(k) does not, and the low-tax years before RMDs begin are usually the cheapest time to shift assets into that Roth bucket (we sized up that window in a free guide here: The Roth Window).
Same Exposure, No Tax Drag
The cheaper mirror is the same fund, different location. Hold VOO, iShares Core S&P 500 ETF (NYSEARCA:IVV) at 0.03%, or SPDR Portfolio S&P 500 ETF (NYSEARCA:SPYM) at 0.02% inside a Roth IRA, traditional IRA, or 401(k). Qualified dividends compound without an annual federal tax event. SPYM carries a lower headline fee than VOO by 1 basis point, which trims another dollar per $10,000 per year. On S&P 500 exposure, the three funds track the same 500 stocks. The exposure trade-off is close to zero. The tax trade-off is thousands of dollars a year on a large taxable position.
Ask This Before Your Next Reinvestment
VOO is a strong fund. At 0.03%, 1% turnover, and 17.06% trailing one-year return, it is one of the cheapest S&P 500 vehicles in existence. The question is whether every share you own is sitting in the account that keeps the IRS out of your dividends. If your largest VOO block is in a taxable brokerage with reinvestment turned on, you could be quietly writing an extra check to the Treasury every April on income you never spent.
Contact [email protected] for any questions or corrections.
Ryne Mauck is an investment writer covering exchange-traded funds, retirement planning, and portfolio strategy. Through his work at 24/7 Wall St. and other investment platforms, including Seeking Alpha, he aims to provide clear, research-driven insights that help investors make more informed decisions while maintaining a long-term approach to investing.
Ryne holds a B.Sc. in Finance and an M.A. in Political Science. He is a formerly registered Municipal Advisor Representative and has passed the Series 50, Series 63, and Series 65 exams. His articles are not intended to be, nor should they be interpreted as, financial advice.