Hims & Hers Celebrated Its Eli Lilly Deal, Then Lost a Quarter of Its Value in a Week

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
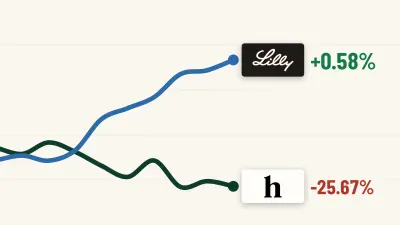
Shares of Hims & Hers (NYSE:HIMS) traded at $18.76 at midday Tuesday. That is 18.22% lower on the session and 25.67% lower over the past week. The drop comes four days after Hims and Eli Lilly (NYSE:LLY | LLY Price Prediction) announced an agreement on November 6 to expand access to Zepbound and Foundayo. Over the same session, Lilly shares rose 0.58% to $1,420.20.
The two companies sit in very different ETFs. The deal links a small telehealth stock owned mainly by small-cap and thematic funds to a pharma giant that large healthcare and broad-market funds depend on.
Lilly Gains While Hims Gives Back the Deal Rally
Over the past month, Hims has fallen 39.33%, and it is down 42.22% year to date. Lilly is up 20.43% over the past month and 32.79% this year. Lilly’s third-quarter revenue rose 38.61% to $24.397 billion, and the company raised its full-year revenue outlook to $91 billion to $92 billion.
Hims Chief Executive Andrew Dudum called Lilly “one of the most innovative pharmaceutical companies in history.” On Monday’s earnings call, he added, “We are thrilled to be working with Lilly in this new capacity and look forward to our continued collaboration to benefit patients.”
Q3 Results Show What the Branded GLP-1 Pivot Costs
Each weak spot in the November 9 report ties back to the move from compounded GLP-1s to branded drugs:
- Margins: Gross margin dropped to 57% from 74% a year earlier.
- Earnings: The GAAP loss of $0.14 per share missed the expected $0.0563 profit. The net loss came to $33.04 million.
- Charges: The quarter included $3.83 million in restructuring tied to the U.S. weight-loss shift and $35.42 million in acquisition and earn-out costs.
- Subscribers: The base shrank by 100,000 from the prior quarter to 2.8 million, though that is still 13% above last year.
- Guidance: Full-year Adjusted EBITDA guidance was cut to $257 million to $277 million.
Revenue held up, rising 48.65% to $890.37 million, just under the $892.77 million consensus. Management described the tradeoff as deliberate. In Dudum’s words, “Each of these choices trades near-term subscriber growth for a stronger position in the years that follow.”

Which ETFs Hold Hims & Hers, and How Much
In their latest N-PORT filings, 89 ETFs report holding Hims. The table below shows the biggest weights next to the biggest dollar positions.
| Fund | HIMS Weight | Position Value |
|---|---|---|
| iShares Russell 2000 ETF (NYSEARCA:IWM) | 0.23% | $192.3M |
| iShares Core S&P Mid-Cap ETF (NYSEARCA:IJH) | 0.20% | $251.4M |
The weights come from filings dated mid-2026, before the latest decline. If you apply this week’s 25.67% drop to those weights, IWM loses roughly 0.06 points and IJH roughly 0.05. Hims has fallen since those filings, so its weights today are likely smaller.
Most Index Investors Hold Far More Lilly Than Hims
The Health Care Select Sector SPDR Fund (NYSEARCA:XLV) held Lilly at 16.51% of net assets, a $6.70 billion position, as of June 30, 2026. Hims does not appear among its holdings. Investors who own both IWM and XLV hold both sides of this partnership, but the exposure is uneven: almost all of it is Lilly. Lilly gained just 0.65% for the week, which suggests the Hims deal matters little to Lilly’s valuation. For Hims, the deal is a major strategic shift.

Three Signals That Matter Before January
Subscriber recovery. Management expects another quarter of subscriber-count headwinds in Q4, with Q4 revenue guided to $875 million to $895 million. If subscriber growth does not pick up in Q1, the explanation that the pullback was deliberate will be harder to defend.
Margin strength. CFO Yemi Okupe said most of the sequential margin decline came from international operations, and management expects international gross margins to improve over time. The next report should tell if 57% marks the low point.
Lilly revenue timing. Okupe said the company expects “to start to realize some of the benefits in Q1,” with retention gains continuing into 2027. Until Zepbound and Foundayo sales appear in reported revenue, the partnership’s costs show up in the numbers ahead of its return.
Contact [email protected] for any questions or corrections.
Ryne Mauck is an investment writer covering exchange-traded funds, retirement planning, and portfolio strategy. Through his work at 24/7 Wall St. and other investment platforms, including Seeking Alpha, he aims to provide clear, research-driven insights that help investors make more informed decisions while maintaining a long-term approach to investing.
Ryne holds a B.Sc. in Finance and an M.A. in Political Science. He is a formerly registered Municipal Advisor Representative and has passed the Series 50, Series 63, and Series 65 exams. His articles are not intended to be, nor should they be interpreted as, financial advice.