Dave Ramsey Says This is How You Get Wealthy
Not everyone agrees with Dave Ramsey, but his track record makes him hard to ignore. His net worth is commonly estimated at around $200 million, though his own statements suggest the number is considerably higher. He claims to own roughly…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Not everyone agrees with Dave Ramsey. His blanket opposition to credit cards and mortgages has drawn steady criticism from financial planners who see nuance where Ramsey sees recklessness. Even so, his track record is difficult to dismiss.
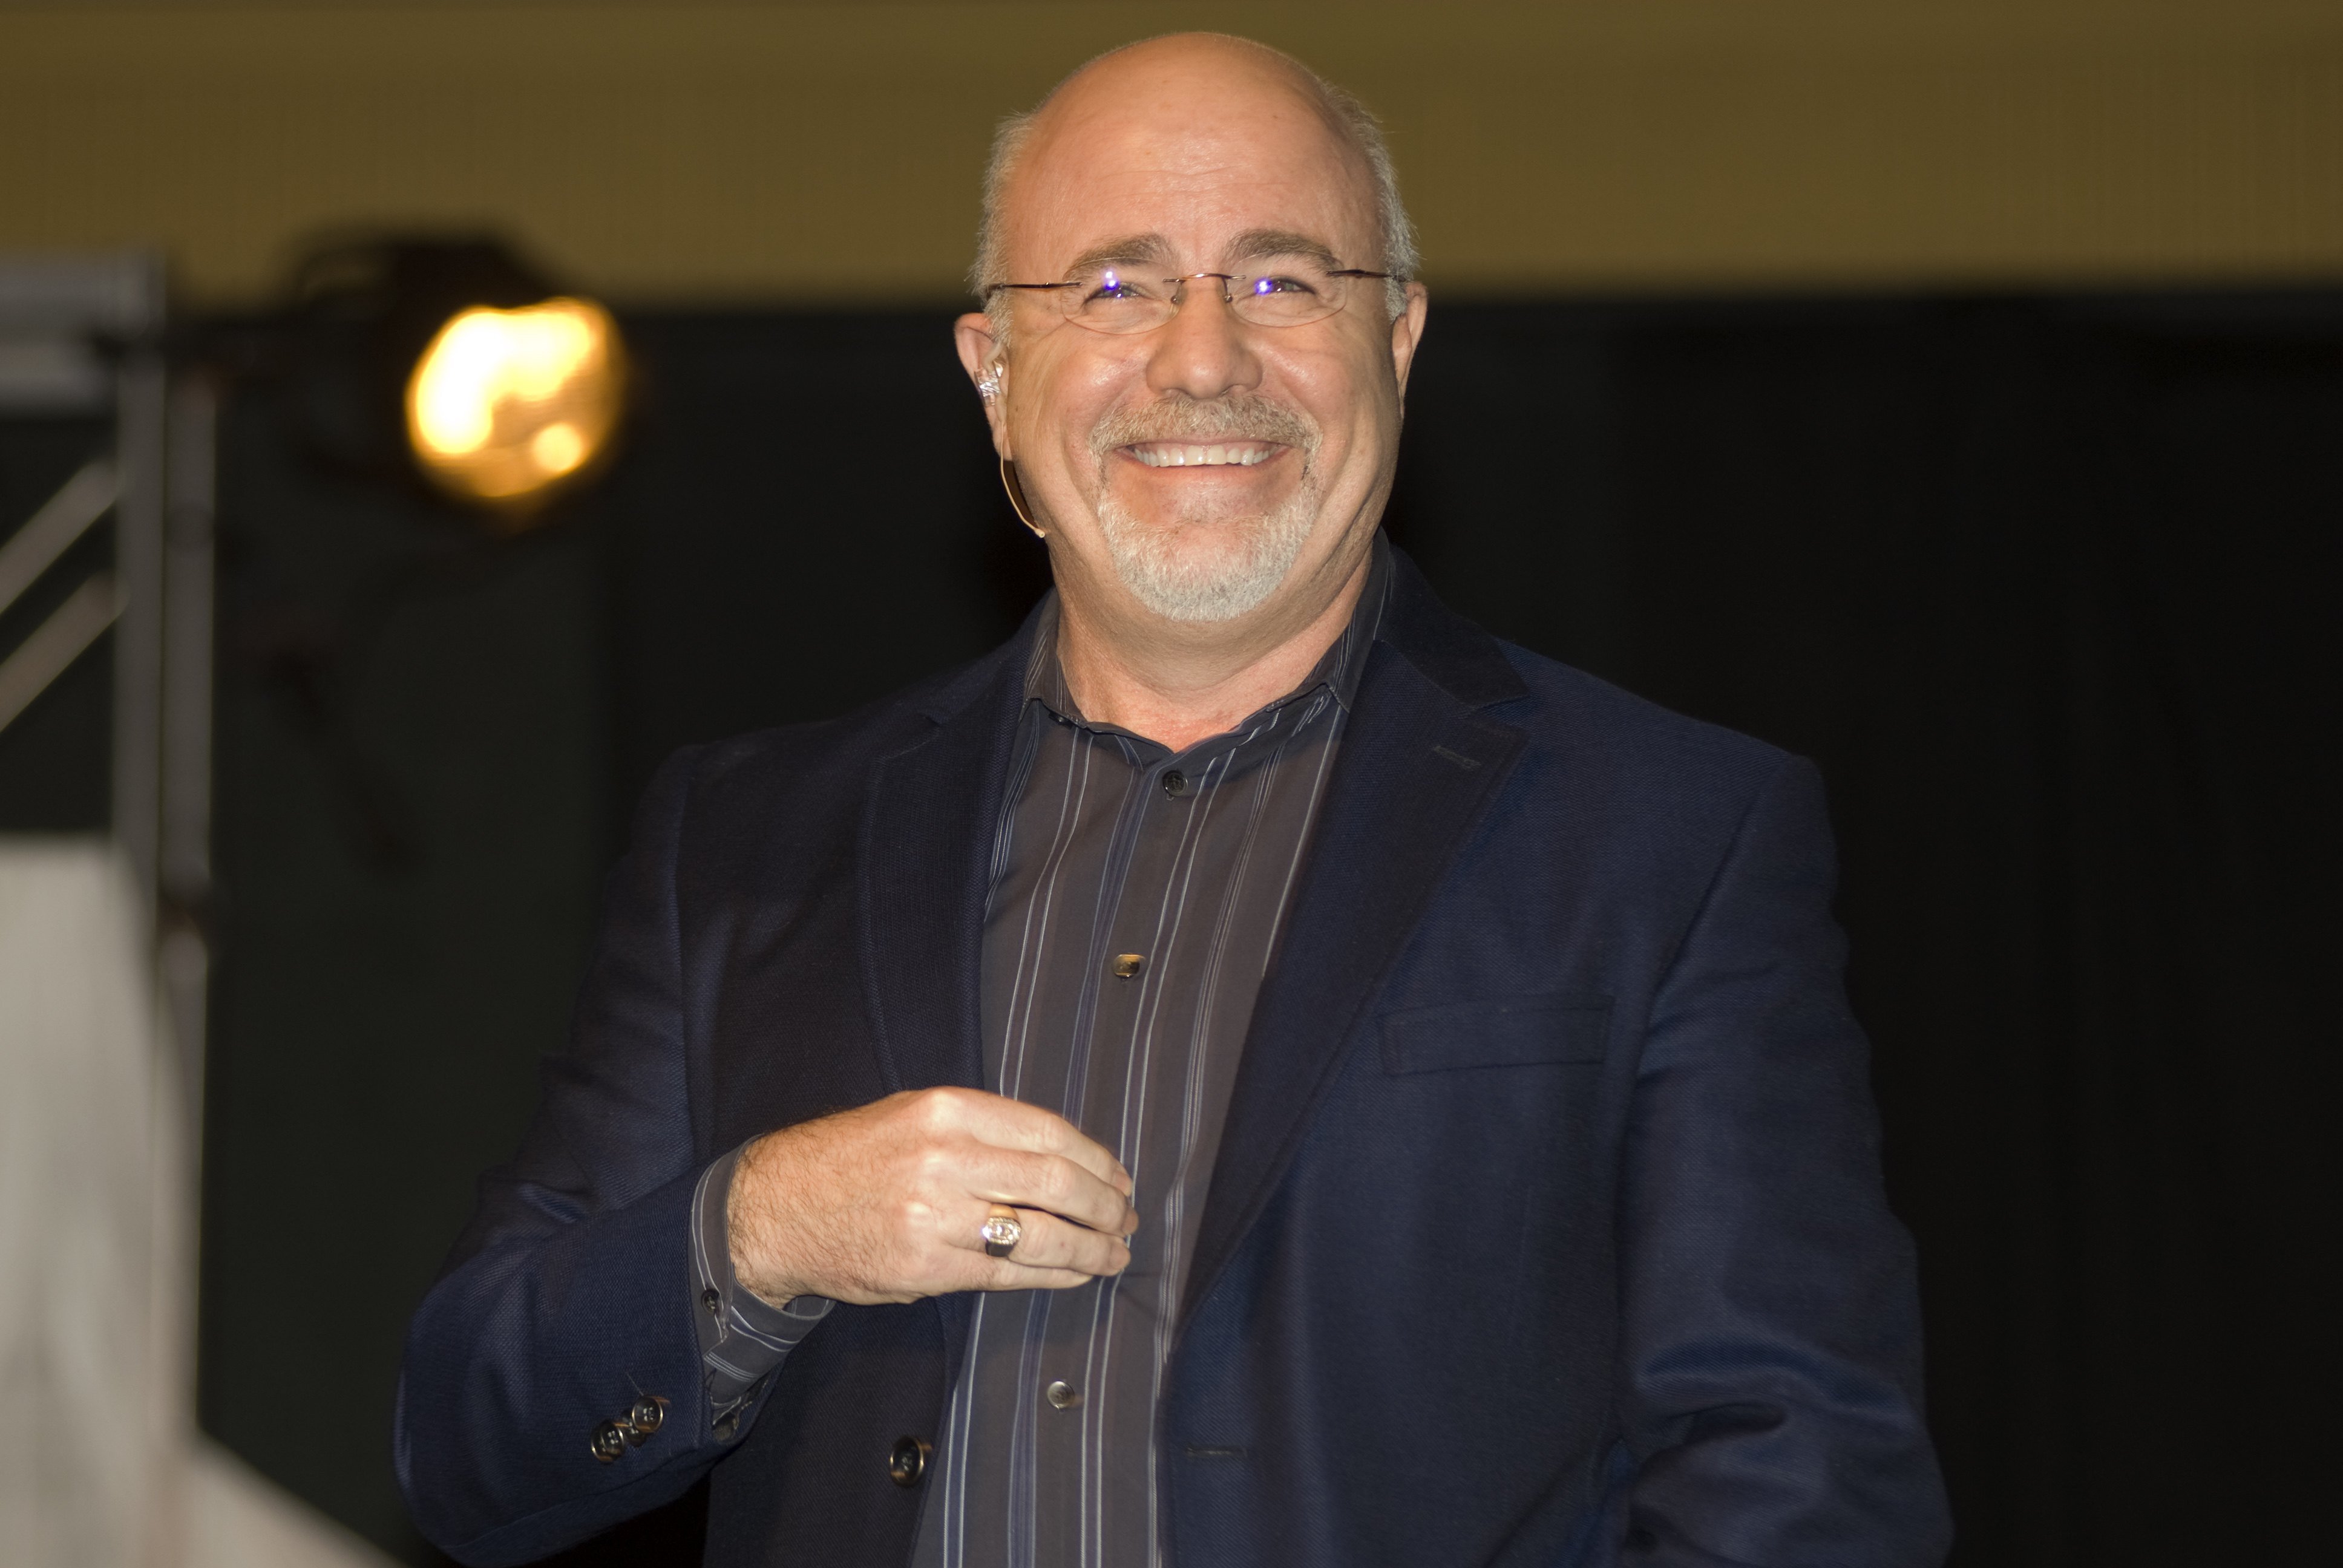
Ramsey’s net worth is most commonly pegged at around $200 million, but his own disclosures suggest the real figure is considerably higher. In a late 2025 interview on “The School of Hard Knocks” YouTube channel, he told host James Dumoulin that Ramsey Solutions generated a record $300 million that year, and that he owns roughly $850 million in real estate accumulated entirely without debt. He went further, telling Dumoulin he is “probably a billionaire.” His Ramsey Solutions headquarters campus in Franklin, Tennessee, built over decades on land he paid cash for, carries an approximate value of $650 million on its own. Anyone who has assembled that kind of enterprise is, at minimum, worth paying attention to.
His core message has stayed consistent for decades: debt is the single biggest obstacle standing between ordinary Americans and genuine wealth. As he put it on his Instagram page, “Your most powerful wealth-building tool is your income. And when you spend your whole life sending loan payments to banks and credit card companies, you’re making everyone else wealthy, and you end up with less money to save and invest for your own future.”
Ramsey lumps credit cards, student loans, car payments, and borrowing in general into a single category he calls “stupid.” The counterargument is obvious: sitting on $850 million in real estate and running a media operation reaching more than 18 million combined weekly listeners makes avoiding debt considerably easier than it is for the average household. Still, the underlying logic holds regardless of net worth. Debt diverts income away from saving and investing, and no amount of personal wealth changes that arithmetic.
The numbers behind that logic are striking. Total U.S. household debt stood at $18.8 trillion as of the second quarter of 2026, according to the Federal Reserve Bank of New York, up $4.6 trillion from the end of 2019. Credit card balances reached $1.26 trillion in that same quarter, with the average commercial bank credit card APR sitting at around 21%, close to its all-time high. For the roughly 60% of cardholders who carry a balance from month to month, the wealth transfer Ramsey describes is playing out in real time.
How to Get Out of Debt Using the Debt Snowball Plan
Millions of Americans are already deep in debt, and simply telling them to avoid it is not particularly actionable. For those households, Ramsey advocates the debt snowball method: pay off debts from smallest to largest balance, regardless of interest rate.
The mechanics are straightforward. List every debt you carry, from student loans and car payments to credit cards and a mortgage. Then, as explained by Ramsey Solutions, “Make minimum payments on all debts except the smallest, throwing as much money as you can at that one. Once that debt is gone, take its payment and apply it to the next smallest debt (while continuing to make minimum payments on your other debts).”
Repeat that cycle until every balance is gone. The psychological appeal of knocking out small debts quickly keeps people engaged in a way that a purely math-driven payoff sequence often does not. Critics point out that a “debt avalanche” approach, which targets the highest-rate debt first, saves more money in interest over time. Ramsey’s answer has always been the same: behavioral momentum matters as much as the math, and a plan you actually stick with beats an optimal one you abandon.
His bottom line is captured in a quote he has repeated for years: “Trying to save and invest while you’re still in debt is like running a marathon with your feet chained together.” With total household debt up $4.6 trillion since the end of 2019 and credit card balances near an all-time high, that analogy has rarely felt more apt.
Editor’s note: The weekly listener count was corrected to “more than 18 million” per Ramsey Solutions’ own figures. Credit card balance data was updated to the Q2 2026 Federal Reserve Bank of New York figure of $1.26 trillion, and the average credit card APR was revised to approximately 21%, reflecting Q2 2026 Federal Reserve data.
Contact [email protected] for any questions or corrections.
Ian Cooper is a veteran market analyst and investment strategist with more than 20 years of experience covering stocks, commodities, and macro trends. Since 1999, he has helped investors identify market opportunities using a blend of technical analysis, fundamental research, and market sentiment.
He is the creator of the ADD News Flow Strategy, which focuses on trading market reactions to major news events and investor psychology. Cooper was also among the analysts who warned about the 2008 financial crisis and major financial institution collapses ahead of the broader market.
Before joining 247 Wall St., Cooper wrote extensively for InvestorPlace and other financial publications, covering market trends, trading strategies, and investment opportunities.