People Say $10 Million Is Enough to Retire Early, but I Strongly Disagree
Is a $10 million net worth the right amount for you to retire? A post in the Fat FIRE subreddit generated significant engagement around exactly that question. The Redditor references a Financial Samurai blog post that argues $10 million is…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.

Is a $10 million net worth the right target for retirement? A post in the Fat FIRE subreddit sparked a lively debate around exactly that question. The Redditor cited a Financial Samurai blog post by Sam Dogen, who argues that $10 million is the ideal net worth to retire on comfortably.
That figure sounds staggering to most Americans, yet the Fat FIRE community revisits it constantly. Whether it is genuinely sufficient depends almost entirely on personal circumstances: where you live, how long your retirement needs to last, and the lifestyle you intend to fund. Talking with a financial advisor before setting any firm target is a sensible first move.
Location and Lifestyle Matter
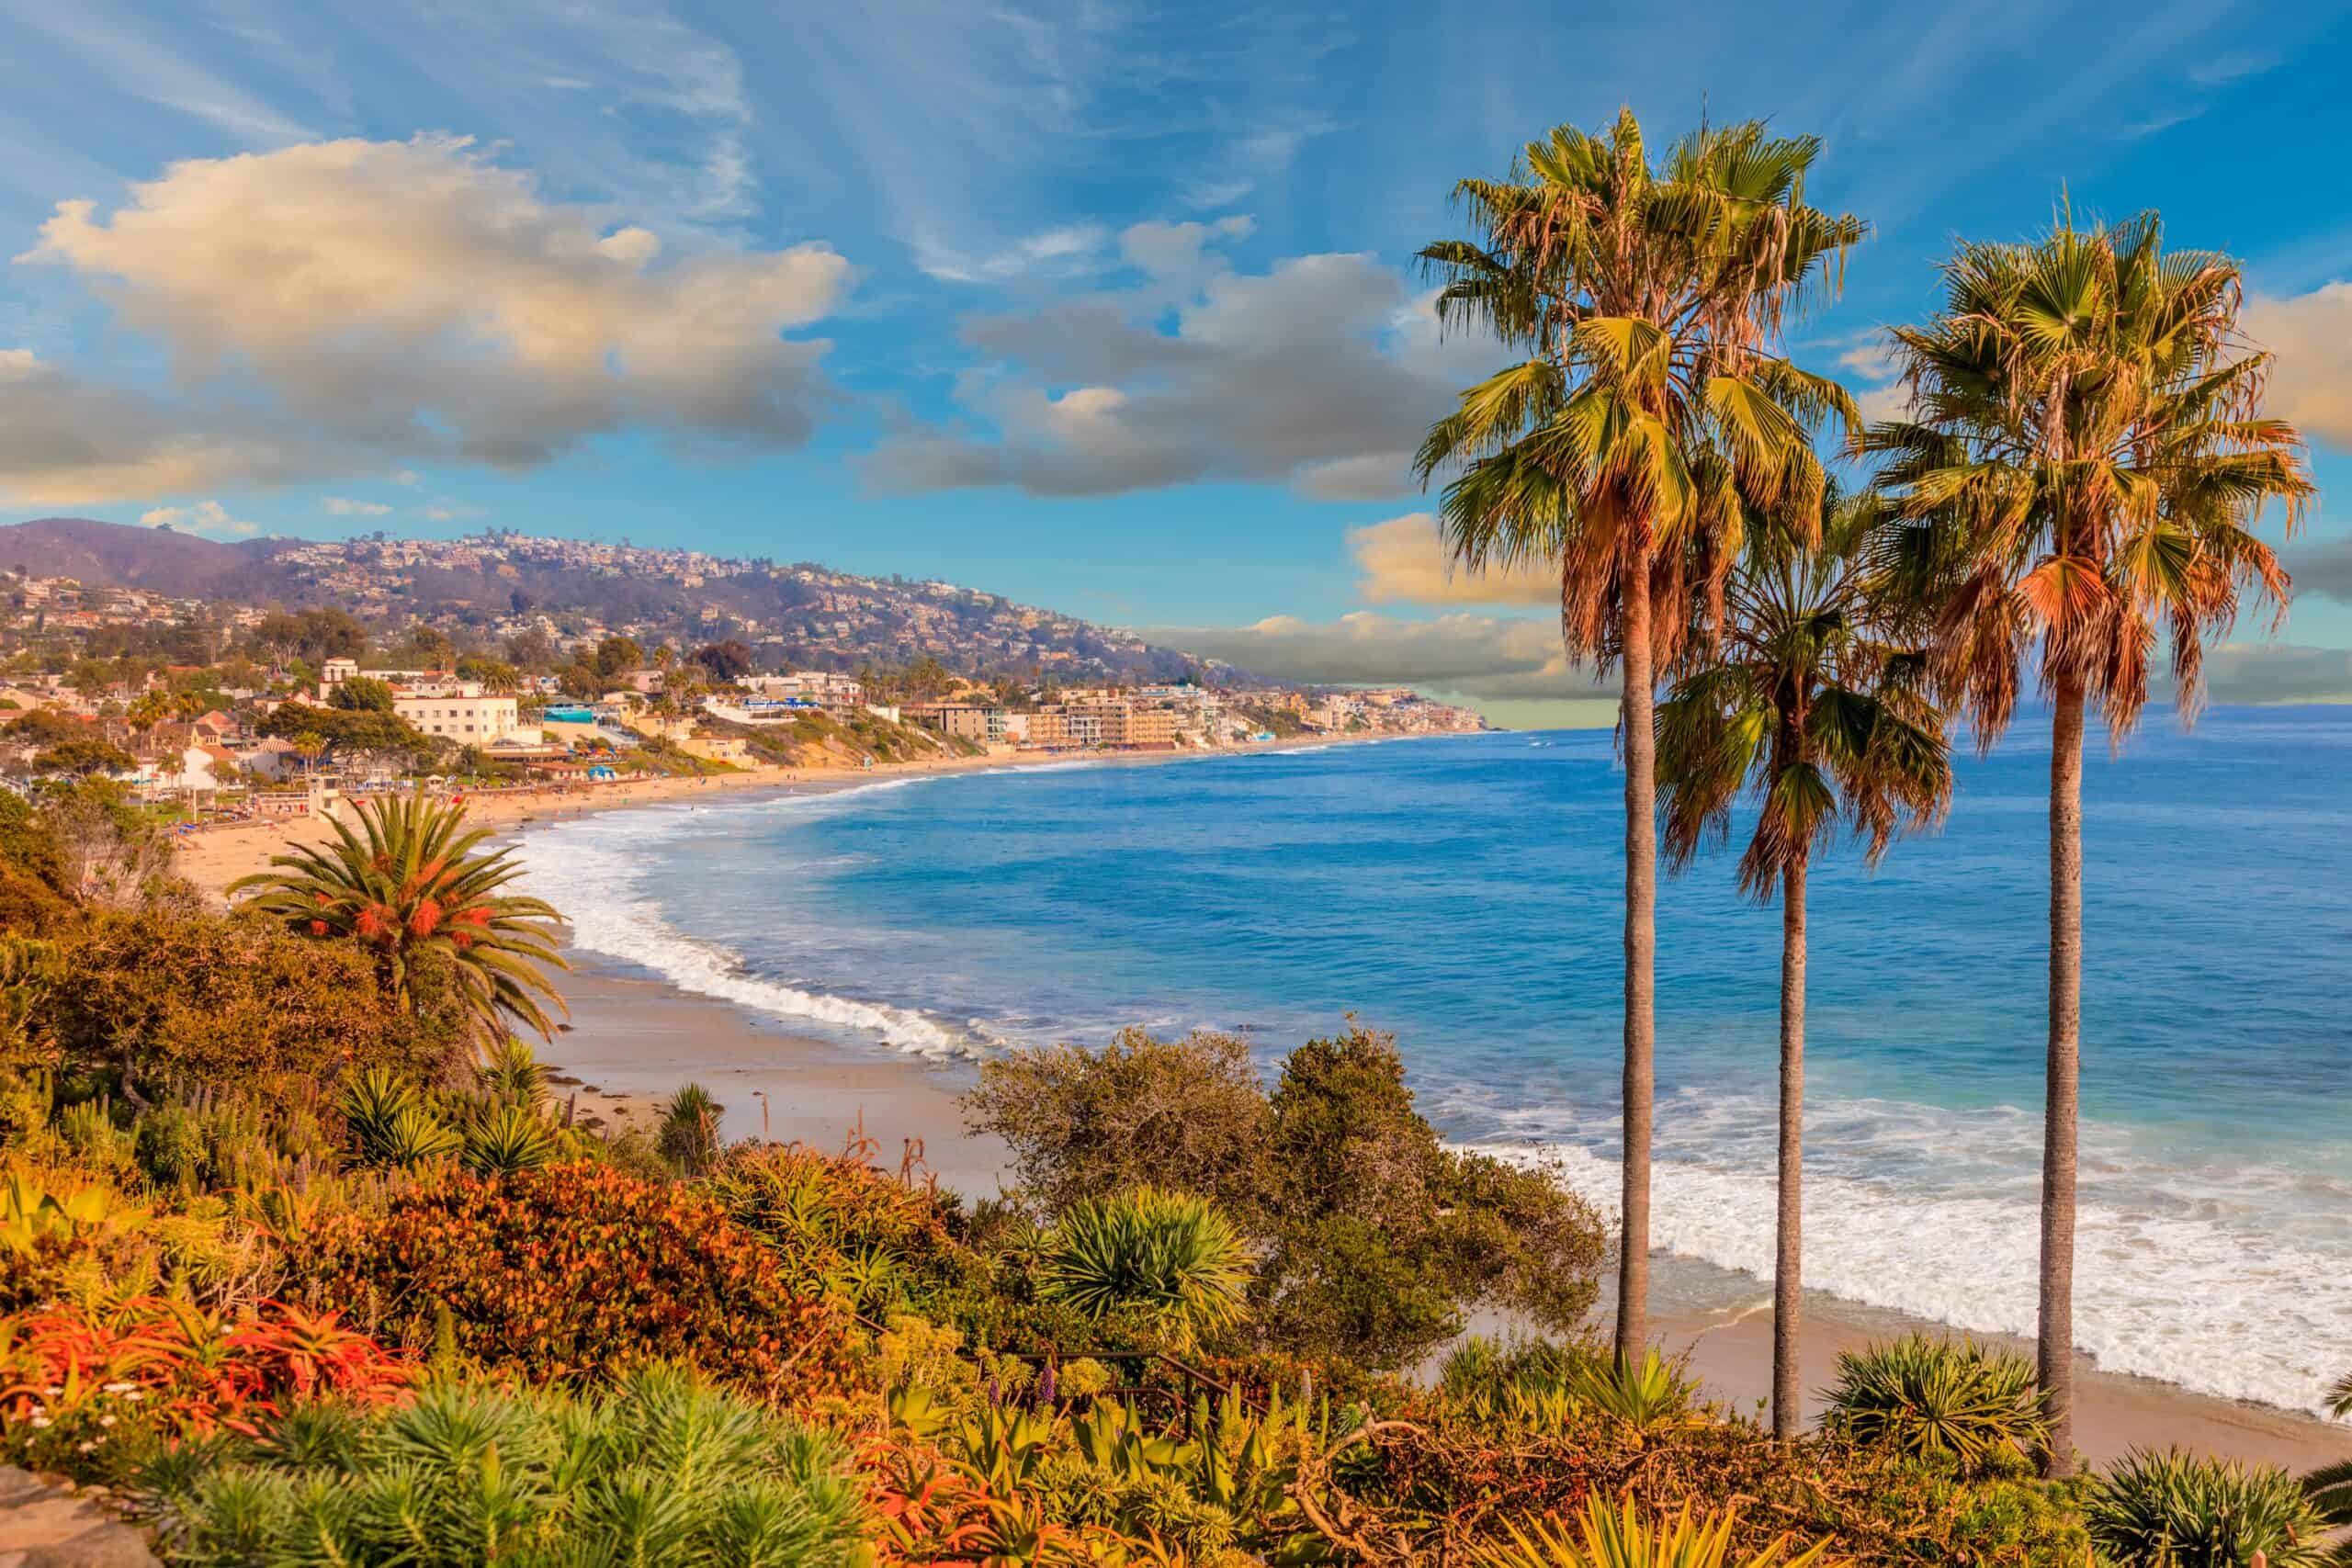
Geography does more to shape retirement math than almost any other single variable. Dogen founded Financial Samurai in 2009 and spent 13 years in investment banking, first at Goldman Sachs from 1999 to 2001 and then at Credit Suisse from 2001 to 2012, where he rose to Executive Director. He left finance at 34 after negotiating a severance package that covered roughly five years of living expenses. Today he lives in San Francisco, one of the most expensive cities in the world, which goes a long way toward explaining why his retirement target sits so much higher than what most households would ever require. He estimates that $10 million in income-producing assets can generate roughly $350,000 to $500,000 per year in low-risk income, a range that makes sense for a high-cost coastal city but far exceeds what the typical retiree needs.
For someone in a low-cost rural area, the math shifts dramatically. Retiring on $1 million or $2 million is achievable in the right location, particularly for someone near traditional retirement age who does not need the portfolio to span four or five decades. For those chasing a high-end lifestyle, however, spending on luxury goods and private healthcare tends to outpace general inflation. That dynamic is part of why some in the Fat FIRE community argue that $10 million is effectively the new $5 million.
Continuing to Work After a $10 Million Net Worth
Crossing a $10 million threshold does not automatically translate into retirement. Many people keep working well past that point, a pattern sometimes called “One More Year Syndrome.” The psychological pull to stay employed is rarely about the numbers. It is usually rooted in a fear of losing a professional identity, or in the comfort of a predictable paycheck, rather than any genuine financial need.
The Redditor who sparked this conversation holds a net worth of $12 million, split between $10 million in stocks and ETFs and $2 million in home equity. Despite sitting well above any conventional retirement threshold, this person has stayed in the workforce because the job is low-stress and provides reliable income. That choice illustrates how personal fulfillment and financial inertia can easily override a purely numerical case for calling it quits.
Dogen himself is a telling example of this tension. Although he left Credit Suisse in 2012, he built Financial Samurai into one of the most widely read independently owned personal finance sites in the country, drawing roughly one million organic visitors a month. His 2022 book “Buy This, Not That” reached the Wall Street Journal bestseller list, and in 2025 he followed it with the USA TODAY national bestseller “Millionaire Milestones: Simple Steps to Seven Figures.” For many high-net-worth individuals, the focus ultimately shifts from accumulating wealth to finding meaningful ways to spend time and energy. Reaching the number, it turns out, is often easier than figuring out what comes next.
How Much Do You Need at Retirement?
The most practical starting point is calculating monthly expenses and then applying a safe withdrawal rate to find the required portfolio size. The longstanding “4% rule,” developed by researcher Bill Bengen in a 1994 paper published in the Journal of Financial Planning, holds that a retiree can withdraw 4% of a portfolio in year one, adjust for inflation each subsequent year, and reasonably expect the money to last 30 years. That benchmark remains the most widely cited baseline in retirement planning, though it has faced scrutiny from two directions in recent years.
Bengen himself updated his thinking in his 2025 book, “A Richer Retirement: Supercharging the 4% Rule to Spend More and Enjoy More,” raising his recommended first-year withdrawal rate to 4.7%. His revised model replaces the original 50/50 stock-and-bond portfolio with a more diversified mix, allocating roughly 55% to equities spread across five capitalization tiers (large-, mid-, small-, micro-cap, and international stocks), 40% to intermediate-term bonds, and 5% to cash. Bengen argues that retirees who cling to 4% are leaving money on the table. Morningstar, working from a forward-looking view of capital markets, arrives at a more cautious number. Its 2025 State of Retirement Income report pegs the safe starting rate at 3.9% for those preferring a fixed spending approach, up from 3.7% in the prior year’s edition. Retirees willing to use flexible “guardrails” strategies, adjusting spending in response to market conditions, may be able to sustain a starting rate as high as 5.7%, according to the same report. No single figure fits every situation.
Using the classic 4% figure as a planning anchor, a household spending $10,000 per month carries $120,000 in annual expenses, implying a required portfolio of $3 million. Those who want added cushion can apply a 3% withdrawal rate, which pushes the required nest egg to $4 million for that same spending level. Neither figure comes close to $10 million for a household with ordinary expenses, and that gap underscores just how location- and lifestyle-specific any retirement number really is. Some high-net-worth individuals pursue a “Yield Shield” approach, building a portfolio concentrated in dividend-growth stocks so that living expenses are covered entirely by income, without ever touching principal.
The SECURE 2.0 Act has also given large tax-deferred portfolios more room to grow before mandatory distributions begin. Required Minimum Distributions (RMDs) now start at age 73 for those born between 1951 and 1959, up from age 72 under the original SECURE Act. Those born in 1960 or later face a higher threshold: their RMDs do not begin until age 75, with the first such distribution falling due in 2035 for the earliest-affected cohort. That extended tax-deferral window lets a large portfolio compound for more years before mandatory withdrawals kick in, which is a meaningful advantage for anyone who stops working in their 40s or 50s.
The age at which someone retires matters enormously. A person stepping back in their 60s needs a smaller cushion because the portfolio has fewer decades to outlast. Someone targeting retirement in their 30s or 40s faces a horizon of 50 years or longer, where compounding inflation and escalating healthcare costs carry far greater weight. For that group, a higher portfolio target is a practical necessity rather than an indulgence.
The bottom line is that $10 million covers retirement comfortably for most people in most scenarios, but it is neither a universal floor nor a universal ceiling. Personal spending, location, retirement age, and risk tolerance all matter far more than any single target number.
Editor’s note: This pass corrects the description of Bengen’s updated portfolio model to reflect a 55% equity allocation spread across five capitalization tiers (plus 40% bonds and 5% cash), consistent with the methodology in his 2025 book, and clarifies the SECURE 2.0 RMD timeline to note that those born in 1960 or later face an age-75 threshold with the first such distribution falling due in 2035.
Contact [email protected] for any questions or corrections.
Marc Guberti is a personal finance writer who has written for US News & World Report, Business Insider, Newsweek and other publications. He also hosts the Breakthrough Success Podcast which teaches listeners how to use content marketing to grow their businesses.