High School Students Are Taking $300,000 in Debt for $30,000 Jobs: Here’s the Math That Should Stop Them
A high schooler told George Kamel she planned to go $300,000 into debt for a sonography degree. When Kamel asked how she'd pay it back on a $30,000 starting salary, she said "if I die, then it doesn't happen." That…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
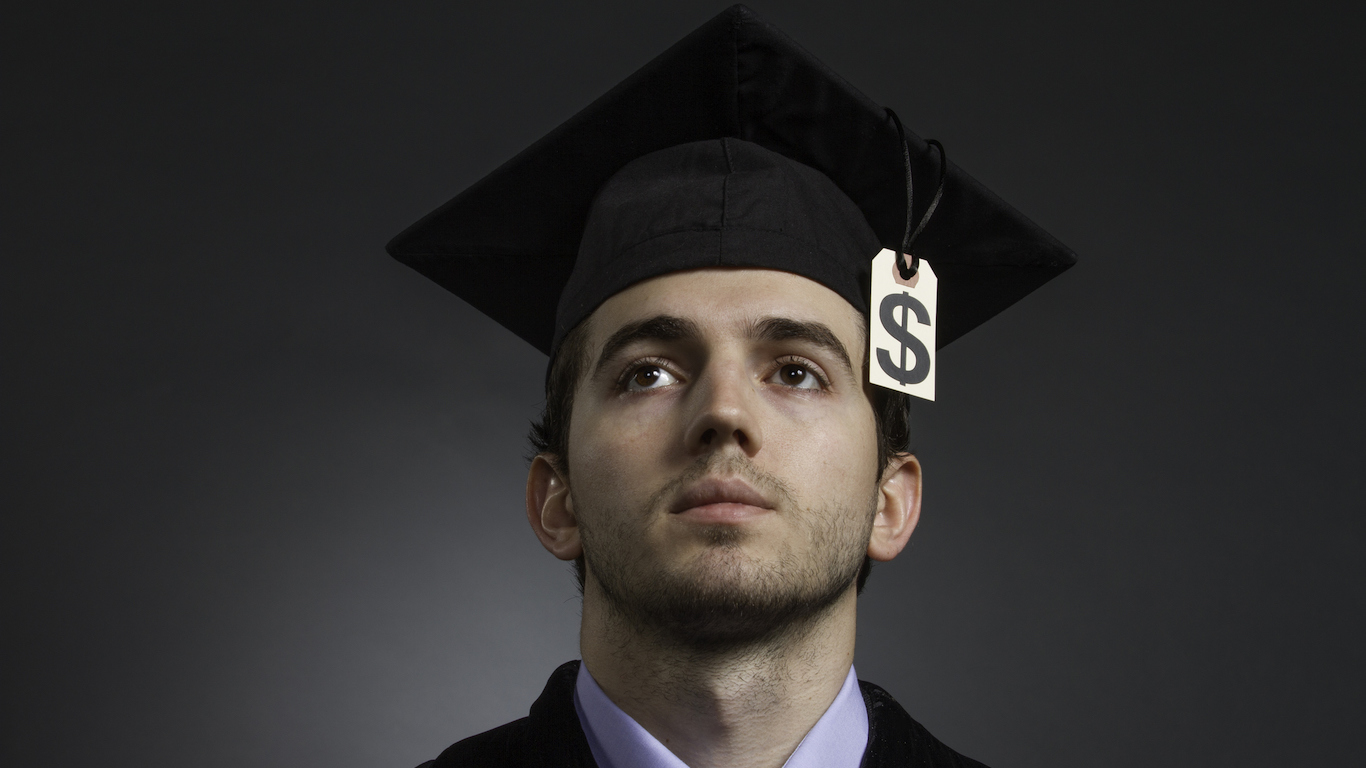
A high schooler told George Kamel she planned to go $300,000 into debt for a sonography degree. When Kamel asked how she would pay it back on a $30,000 starting salary, she said “if I die, then it doesn’t happen.” That answer is not gallows humor. It is a student describing a financial trap she does not yet know how to name, let alone escape.
Kamel’s exchange, from his video I Asked High Schoolers Money Questions They Weren’t Ready For, is worth breaking down carefully, because the student’s core assumption, “if I get my degree, I can pay it off,” is precisely the logic that wrecks middle-class balance sheets for 25 years. Kamel put it bluntly: “Forever. You will never pay it off if you always make $30,000 and you have $300,000 in debt. Because think about it, you got interest on that debt.”
The verdict: Kamel is right, and the math is brutal
Borrowing ten times your expected first-year salary is financial self-immolation, and the numbers leave no room for debate. For the 2026-2027 academic year, undergraduate Direct loans carry a fixed rate of 6.52%, up from 6.39% the prior year. Parent PLUS loans sit at 9.07%, up from 8.94%. Take a blended rate of 7% on a $300,000 balance, and the annual interest charge alone reaches $21,000. A borrower earning $30,000 gross takes home roughly $25,000 after taxes. That interest bill consumes nearly the entire net paycheck before a single dollar reaches rent, groceries, or a bus pass.
A standard 10-year repayment on $300,000 at 7% demands roughly $3,500 a month, or $42,000 a year on a $30,000 salary. That is simply impossible. The situation becomes harder still for borrowers taking out new loans starting July 1, 2026. The One Big Beautiful Bill Act, enacted July 4, 2025, eliminates IBR, PAYE, and SAVE for any loans disbursed on or after that date, leaving new borrowers with just two options. The first is the Repayment Assistance Plan (RAP), an income-driven plan that charges 1% to 10% of adjusted gross income with a maximum 30-year payoff window. The second is a new Tiered Standard Plan whose term depends on total debt: 10 years for balances under $25,000, 15 years for $25,000 to $49,999, 20 years for $50,000 to $99,999, and 25 years for $100,000 or more. Neither option makes a $300,000 debt load manageable on a $30,000 salary. Under RAP, unpaid interest accumulates throughout the repayment period; the borrower stays underwater the entire time, potentially for three full decades. Worth noting: new Parent PLUS loans originated on or after July 1, 2026 are excluded from RAP entirely and are restricted to the Standard Repayment Plan.
The broader economic backdrop only sharpens the problem. Real average hourly earnings fell 0.1% from August 2025 to August 2026, even as nominal wages ticked upward, because consumer prices outpaced pay gains. A $30,000 salary buys less every year, while the $300,000 balance compounds without pause.
The variable that flips everything: the spread between debt and starting salary
Kamel paired the sonography exchange with a second student who had actually done the homework. She wanted to become a registered nurse and had researched a four-year program at the University of North Alabama, priced at roughly $12,000 per year, with starting pay of $62,000 to $69,000 in her area. Total borrowing roughly equal to first-year income. Manageable, with discipline.
The contrast is sharp, and there is an extra layer worth adding: sonography is not a low-wage field. The Bureau of Labor Statistics puts the national median annual wage for diagnostic medical sonographers at $96,590 as of May 2025, with the field projected to grow 14% from 2025 to 2035, much faster than the average for all occupations. The lowest-paid 10% of sonographers nationally earn just under $67,820 per year, while the top 10% exceed $129,370. The career itself pays well. The student’s problem was not her chosen field. It was the $300,000 price tag, which is roughly four times what most accredited sonography programs actually cost.
That distinction is critical. Borrow $48,000 for a $65,000 job and the loan clears in a few disciplined years. Borrow $300,000 for a job that starts at $70,000 and you are still running uphill, because the interest compounds faster than the salary can chase it. The rule that follows from all of this is simple: never borrow more in total student loans than your expected first-year salary in your target city.
What to actually do before signing the loan paperwork
- Look up the real starting wage in your target city. Use the Bureau of Labor Statistics Occupational Employment Statistics page for your exact job title and metro area. National averages can mislead. Average hourly earnings across all private employees reached $37.81 in September 2026, but entry-level pay in your specific field and city may be a fraction of that figure.
- Add up the full sticker price. Tuition, fees, books, housing, and food for all four years. Subtract only guaranteed scholarships and grants confirmed in writing, not the estimated aid on the brochure.
- Apply the one-to-one rule. If total borrowing exceeds expected year-one salary, the deal requires a different school, community college credits to cut costs, in-state tuition, or more scholarship money locked in before enrollment.
- Stress-test the payment. Run the loan through the Federal Student Aid loan simulator at studentaid.gov using the standard 10-year plan. A monthly payment that exceeds 10% of expected take-home pay is a deal-breaker, not a starting point for negotiation.
The student who said “if I die, then it doesn’t happen” was describing a math problem no one had taught her to solve. The unemployment rate ticked up to 4.2% in September 2026, a reminder that a job after graduation is likely but never guaranteed. Even a strong starting salary in a growing field cannot outrun a debt load that is four to ten times its size. Under the new federal loan rules in effect since July 2026, borrowers have fewer safety valves than their predecessors did, and the tiered standard terms and RAP structure offer less flexibility than the old income-driven plans. Parents and students need to run these numbers together, carefully, before anyone signs anything. The math has to work on day one, or it almost certainly never will.
Editor’s note: This article has been updated to reflect the September 2026 unemployment rate of 4.2% (up from 4.1% in August) and average hourly earnings of $37.81 in September 2026, per the Bureau of Labor Statistics October 2 release. The discussion of One Big Beautiful Bill Act repayment rules has been expanded to include the specific debt-based term tiers of the new Standard Repayment Plan and the exclusion of new Parent PLUS loans from RAP eligibility.
Contact [email protected] for any questions or corrections.
I've been writing about stocks and personal finance for 20+ years. I believe all great companies are tech companies in the long run, and I invest accordingly.