The Florida Retirement Secret: Live Inland, Keep the Beach

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
For many retirees, the dream is a condo in Florida. Couples in their late fifties or early sixties often picture the ocean view as part of the package. Then the math arrives: housing costs, insurance premiums, HOA fees, and property taxes stack up fast, and what looked affordable on paper turns out to be anything but.
This article is for those couples. The core idea is straightforward. Enjoying Florida’s beaches does not require living on top of them. Retirees can often cut housing costs dramatically by settling well inland while keeping the Gulf Coast or Atlantic Coast close enough for a day trip. The beach stays part of a weekly routine without becoming the most expensive line item in the retirement budget.
The Coastal Premium Most Buyers Underprice
Start with the house. A coastal listing in a desirable Gulf town like Naples carries a county-wide median near $595,000 to $610,000 as of mid-2026. The statewide median across all residential types was $385,000 in August 2026, according to Redfin, while Florida Realtors puts the single-family median at $425,000 for the same period. Inland markets such as Ocala, Lakeland, Sebring, and The Villages routinely transact well below those figures for comparable square footage on larger lots. On a like-for-like three-bedroom comparison, the coastal premium often reaches $250,000 to $400,000 before the first utility bill arrives.
Insurance is where the math really separates coastal from inland buyers. Florida is the most expensive state in the country for homeowners coverage. Insurance.com’s 2026 data puts Florida’s statewide average at $8,471 a year for a $300,000 dwelling policy, the highest of any state. Within Florida, the spread is severe. Coastal Miami-Dade and Palm Beach properties commonly pay $5,300 to $7,500 a year for comparable base coverage. Inland Ocala-area and Sumter County policies average considerably less, with Sumter County (which includes The Villages) coming in around $2,105 a year on a $300,000 dwelling, among the lowest in the state according to Florida Office of Insurance Regulation data. Add the wind and flood riders that a barrier-island home actually requires, and the gap widens further. Redfin data shows that 98% of Naples properties carry severe flood risk over the next 30 years, which means flood insurance is a practical necessity rather than an optional add-on for most coastal buyers. Over a 25-year retirement, an extra $4,000 a year in premiums alone amounts to $100,000 in pure carrying cost.
There is genuine good news on the insurance front. Following years of sharp increases driven by litigation abuse and hurricane exposure, the 2026 market is stabilizing. Landmark tort reform legislation reduced frivolous lawsuits, capped one-way attorney fees, and curtailed assignment-of-benefits abuse. Before those 2022 and 2023 reforms, Florida accounted for roughly 11% of U.S. homeowner claims but nearly 73% of all U.S. insurance litigation. The result: Citizens Property Insurance cut its statewide multiperil rates by an average of 8.8% for 2026, and Citizens’ policy count fell to 266,231 as of August 2026, down more than 80% from a peak of roughly 1.4 million in September 2023, as private carriers re-entered the market. Several of those private carriers filed their own rate reductions, with State Farm cutting 10%, Florida Peninsula cutting 8.4%, and Patriot Select cutting 11.3%. Florida remains the priciest state for homeowners insurance by a wide margin, but the trend is improving for the first time in years.
Property taxes follow assessed value, so the cheaper inland house pulls the tax bill down with it. Florida ranks 5th overall on the 2026 State Tax Competitiveness Index published by the Tax Foundation, buoyed by its lack of any individual income tax. That means the difference between a $650,000 coastal homestead and a $325,000 inland one shows up cleanly and directly in the millage calculation. Hurricane exposure compounds the same way: wind deductibles on the coast are typically a percentage of dwelling coverage, so a single named storm can mean a five-figure out-of-pocket hit on a coastal house and a far smaller one 90 minutes inland.
How Often Do Retirees Actually Use the Beach?
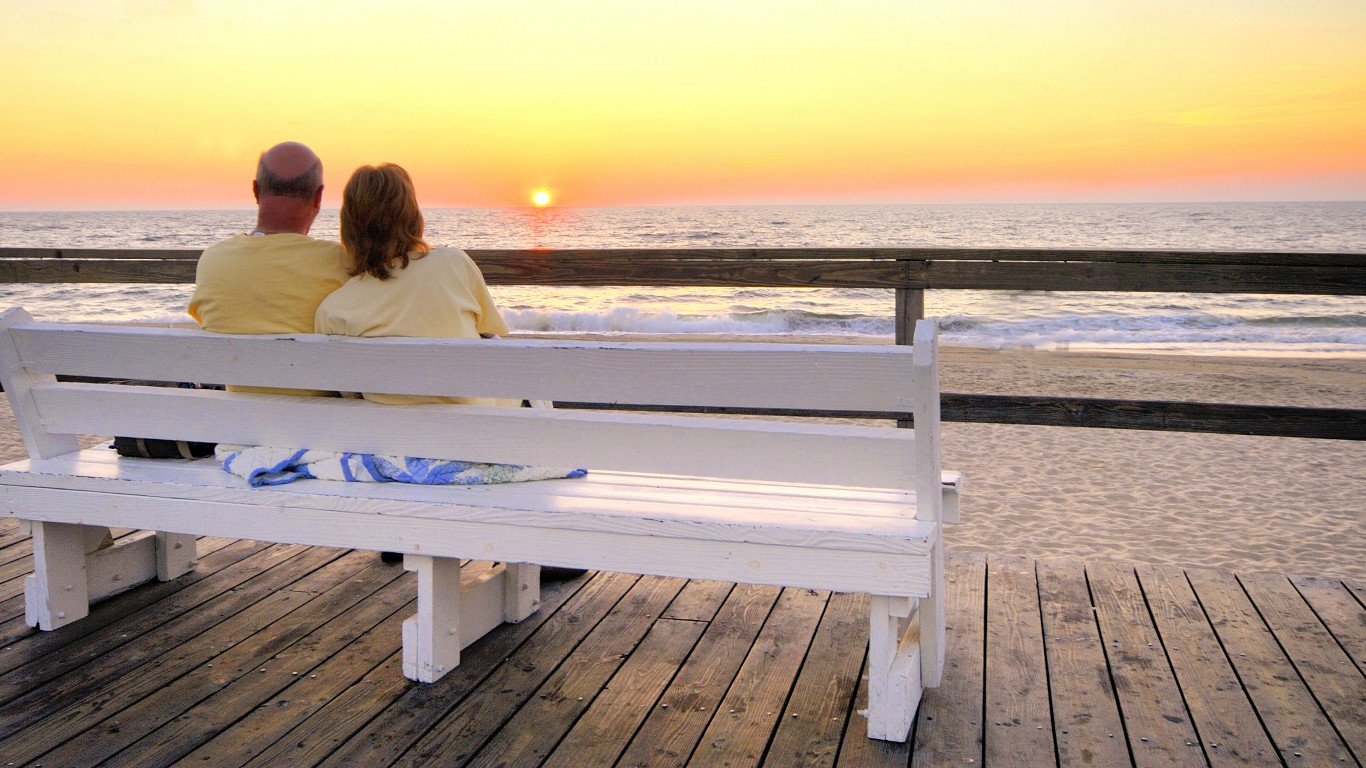
This is the question nobody asks before signing. Talk to retirees who bought oceanfront five years back and a recognizable pattern emerges. The first year, they go constantly. By year three, it is a Saturday morning walk and a sunset once a week. By year seven, the visits are reserved for when grandkids arrive. The view from the lanai stays pleasant, but it fades into the background of daily life. Errands, doctors, pickleball, and the grocery store require none of it.
That reality creates a real opportunity. A retiree living in Ocala, Lakeland, or another inland community can still reach either coast in roughly one to two hours. The beach becomes an easy day trip, a weekend getaway, or a special occasion when friends and family visit. In exchange, retirees gain lower housing costs, lower insurance premiums, less tourist congestion, and easier access to everyday services.
There is also an unexpected benefit to a little distance. Experiences that happen occasionally tend to hold their novelty. A sunset over the water feels more meaningful when it is chosen rather than something passed every evening on the way home from the store. The goal of retirement is proximity to financial flexibility, not just proximity to the ocean. Whether that flexibility funds travel, healthcare reserves, or simply a retirement spent without watching a budget too closely, the math tends to favor those who treat the coast as a destination rather than a doorstep.
What the Savings Actually Buy
Roll the full cost picture together for a middle-class couple: a lower purchase price, lower insurance, lower property taxes, and lower routine maintenance on a house that never sees salt air. The realistic annual savings runs $15,000 to $25,000. Over 25 years, before any investment return, that is $375,000 to $625,000 in preserved capital.
Put that money to work and it becomes genuine optionality. At a 4% withdrawal rate, $400,000 of additional portfolio assets funds roughly $16,000 a year of extra income for life. That covers the $202.90 standard 2026 Medicare Part B premium for both spouses with room to spare, builds a reserve against the $1,736 Part A inpatient deductible, and still leaves enough for two real trips a year. Delaying Social Security to age 70 instead of claiming at 62 raises monthly benefits by roughly 8% for each year of delay, and the lower inland cost structure is precisely what makes that delay financially survivable.
The Moves Most People Should Make
If you want a Florida retirement to succeed on a middle-class portfolio, three things have to happen:
- First, evaluate the full cost of homeownership rather than the purchase price alone. Insurance, storm exposure, deductibles, HOA fees, and ongoing maintenance often matter more than the mortgage payment retirees no longer carry. The biggest financial surprises tend to come from coastal expenses that stay hidden behind an attractive listing, including flood insurance that only becomes apparent when you check FEMA flood maps.
- Second, be realistic about how often you will actually use the beach. If the honest answer is a few dozen times a year rather than a few hundred, living inland and treating the coast as a destination will almost certainly make more financial sense. Occasional hotel stays, weekend rentals, and day trips cost a fraction of what it takes to carry beachfront real estate and its associated insurance year after year.
- Third, put the savings to work where they can strengthen the retirement plan. Additional healthcare reserves, a larger emergency fund, delayed Social Security benefits, or a larger investment portfolio can provide far more long-term security than an ocean view. A stronger balance sheet gives retirees options when markets struggle, healthcare costs rise, or unexpected expenses appear.
The beach is the attraction, not the objective. For many retirees, inland Florida provides access to the same coastline while preserving the financial flexibility that makes the rest of retirement possible.
Editor’s note: This pass corrects the statewide all-residential median home price to $385,000 using Redfin’s August 2026 data (up from the prior $383,000 figure), updates Citizens Property Insurance’s policy count to 266,231 as of August 31, 2026 (reflecting more than an 80% decline from the September 2023 peak of roughly 1.4 million), and replaces the statewide homeowners insurance average with Insurance.com’s 2026 figure of $8,471 for a $300,000 dwelling, the highest of any state.
Contact [email protected] for any questions or corrections.
Drew Wood has edited or ghostwritten nine books and published more than 1,500 articles on investing, business, politics, travel, world cultures, wildlife, and earth science. He holds a doctorate and four master's degrees and has nearly 30 years of college teaching experience. His travels have taken him to 25 countries, including three years living in Ukraine.