He Saved $1 Million For Retirement. Can He Finally Buy The Corvette?
At 67, Mike has done almost everything right. His house is paid off, the kids are grown, and after decades of saving, his retirement accounts have finally crossed the $1 million mark. Now he wants something he has dreamed about…

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
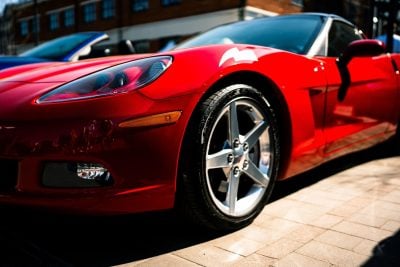
At 67, Mike has done almost everything right. His house is paid off, the kids are grown, and after decades of saving, his retirement accounts have finally crossed the $1 million mark. Now he wants something he has dreamed about since high school: a Corvette.
It sounds like a simple question. Isn’t this what retirement savings are for? For retirees like Mike, though, the real issue is not the car itself. It is whether a six-figure purchase fits into a retirement plan that may need to last another 30 years.
The Dream That Never Went Away
Plenty of people enter retirement carrying a long-deferred dream. A Corvette. A Harley. A bass boat. A motorhome. For many, retirement is the first moment in life when money, time, and freedom finally converge.
That is what makes Mike’s question so relatable. A $1 million portfolio is not just a survival fund. It represents a lifetime of sacrifice, of foregone vacations and delayed gratifications. The central question is not whether he can buy the Corvette. It is whether the rest of the retirement plan still holds together after he does.
The Real Cost Of The Corvette
Mike is not hunting for a collectible 1967 Corvette or a range-topping Z06. He has his eye on a new C8 Stingray, the mid-engine model that has become America’s attainable supercar. The 2026 Stingray 1LT Coupe starts at $71,995, but the well-optioned 3LT Convertible he wants carries a base price of $90,745 before taxes and dealer fees. That figure has kept climbing: GM raised the mandatory destination charge to $2,495 in December 2025, pushing the real out-the-door price past $93,000 in most markets. Buyers with flexibility may also want to consider the 2027 Stingray, which launched this summer with a new 6.7-liter LS6 V8 producing 535 horsepower and a starting price of $73,495. A well-optioned 2027 3LT Convertible with the Z51 package runs roughly $90,640 before additional options, putting it in nearly the same territory as its 2026 predecessor.
The sticker is just the beginning. A new mid-engine Corvette typically costs $2,500 to $3,500 a year to insure for a 67-year-old with a clean record, and more in high-rate states like Florida or Michigan. Maintenance, premium fuel, and performance tires every few years add another $1,500 to $2,000 annually. Registration, personal property tax, and climate-controlled storage push the all-in carrying cost to roughly $5,000 to $7,000 a year, depending on location and mileage.
Then there is the opportunity cost. Pulling $90,000 out of a portfolio at a 4% withdrawal rate permanently removes about $3,600 a year of sustainable income. Over a 25-year retirement, that amounts to roughly $90,000 in foregone withdrawals on top of the original purchase price. Combined with ongoing ownership costs, the true lifetime price lands closer to $200,000 in today’s dollars.
The Retirement Math
Start with what Mike has. A $1 million portfolio supports about $40,000 a year at a 4% draw. Social Security at $3,000 a month, well above the national average of approximately $2,083 for retired workers as of May 2026, adds $36,000 a year. That puts gross retirement income near $76,000 before taxes, a comfortable middle-class budget in most of the country for a household carrying no major debt.
Buy the Corvette outright and the portfolio drops to $910,000. The same 4% draw now produces about $36,400, and total income falls to roughly $72,400. He gives up about $3,600 of annual income while taking on $5,000 to $7,000 in new annual carrying costs. The real swing in discretionary spending is closer to $9,000 a year.
That gap is the line that matters. If his baseline spending was $60,000, he absorbs the hit and keeps a cushion. If he was already planning to spend the full $76,000, the Corvette forces a 12% lifestyle cut elsewhere, or it pushes his withdrawal rate above 4.5%. That gets uncomfortable over a long retirement. The inflation backdrop makes the calculus more demanding still: headline CPI peaked at 4.2% year-over-year in May 2026, an energy-shock high driven largely by conflict in the Middle East, before easing to 3.5% in June and holding at 3.4% in both July and August. Core PCE reached approximately 3% as of August 2026, still well above the Fed’s 2% target. The Federal Reserve held its benchmark rate at 3.5% to 3.75% at its July meeting, then hiked by 25 basis points at its September 2026 meeting, lifting the target range to 3.75% to 4% and signaling at least one more increase before year’s end. Purchasing power will erode faster than it did in the low-inflation decade before 2021, and that erosion matters greatly over a 25-year retirement horizon.
When The Corvette Makes Sense
The purchase becomes reasonable when the rest of the plan is already on solid ground. Mike’s spending sits comfortably below what his portfolio can support. The house is paid off, the kids are independent, and he has a cash reserve that can handle emergencies without forcing portfolio sales at the wrong time. He is healthy enough to enjoy the car, and he has given serious thought to how future healthcare and long-term care costs will be covered. In that situation, the Corvette is not a threat to retirement. It is one of the reasons he saved in the first place.
A million-dollar portfolio is more than a survival fund. For someone who spent forty years delaying gratification, retirement is supposed to include a few rewards. When the numbers still work after the purchase, the dream car is a victory lap, not a financial mistake.
When It Doesn’t
The math gets far less forgiving when the portfolio is already doing all the heavy lifting. If Mike needs every dollar his retirement income can generate just to cover normal living expenses, a $90,000-plus purchase combined with ongoing ownership costs can push the plan into dangerous territory. A market decline early in retirement, paired with larger-than-planned withdrawals, can permanently impair a portfolio’s ability to recover. Sequence-of-returns risk is especially acute in the first five years of retirement, and the Fed’s renewed rate-hiking cycle means bond portfolios are absorbing fresh mark-to-market pressure at the same time.
The risks compound when there is still a mortgage, outstanding debt, looming healthcare expenses, or only a thin emergency fund. In those circumstances, the Corvette stops being a reward for successful planning and becomes another bill competing with necessities.
The key number is straightforward: how much room exists between annual spending and the combination of guaranteed income and sustainable portfolio withdrawals? If that cushion is comfortably in the five figures, the Corvette may fit without threatening the plan. If the budget is already running close to the edge, the answer is probably no.
Beyond the Spreadsheet
There is another factor that never shows up in retirement calculators: the people affected by the decision. If Mike is single with no dependents, the Corvette is largely his choice alone. With a spouse, children, or other family members who may eventually play a role in his care, the purchase becomes a family conversation as much as a financial one.
A $90,000 sports car can mean very different things to different people. To one spouse, it represents a lifelong dream finally realized. To another, it may look like money that could have strengthened the emergency fund, helped cover future healthcare needs, assisted grandchildren with college, or simply provided greater peace of mind. And once one retirement dream gets funded, others tend to follow. The spouse who supports the Corvette today may have a comparable dream of their own tomorrow, whether that is a swimming pool, a home addition, years of international travel, or a vacation property.
Retirement spending is not just about what the portfolio can afford. It is also about what the household can comfortably support together. A Corvette that creates resentment in the passenger seat may wind up costing far more than the sticker price.
Editor’s note: This update adds context on the 2027 Corvette Stingray, which launched this summer at $73,495 with a new 6.7-liter LS6 V8 producing 535 horsepower, giving buyers like Mike an additional option to consider. The inflation section was updated to include the August 2026 headline CPI reading of 3.4% (matching July) and to note the Federal Reserve’s September 2026 rate hike to 3.75%-4.0%, its first increase since 2023, with the central bank signaling at least one more move before year’s end. The Social Security average benefit was also adjusted to approximately $2,083 per month, reflecting May 2026 data from CNBC.
Contact [email protected] for any questions or corrections.
Drew Wood has edited or ghostwritten nine books and published more than 1,500 articles on investing, business, politics, travel, world cultures, wildlife, and earth science. He holds a doctorate and four master's degrees and has nearly 30 years of college teaching experience. His travels have taken him to 25 countries, including three years living in Ukraine.