For Most Retirees, Only One Texas City Actually Makes Sense. Here’s Which.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
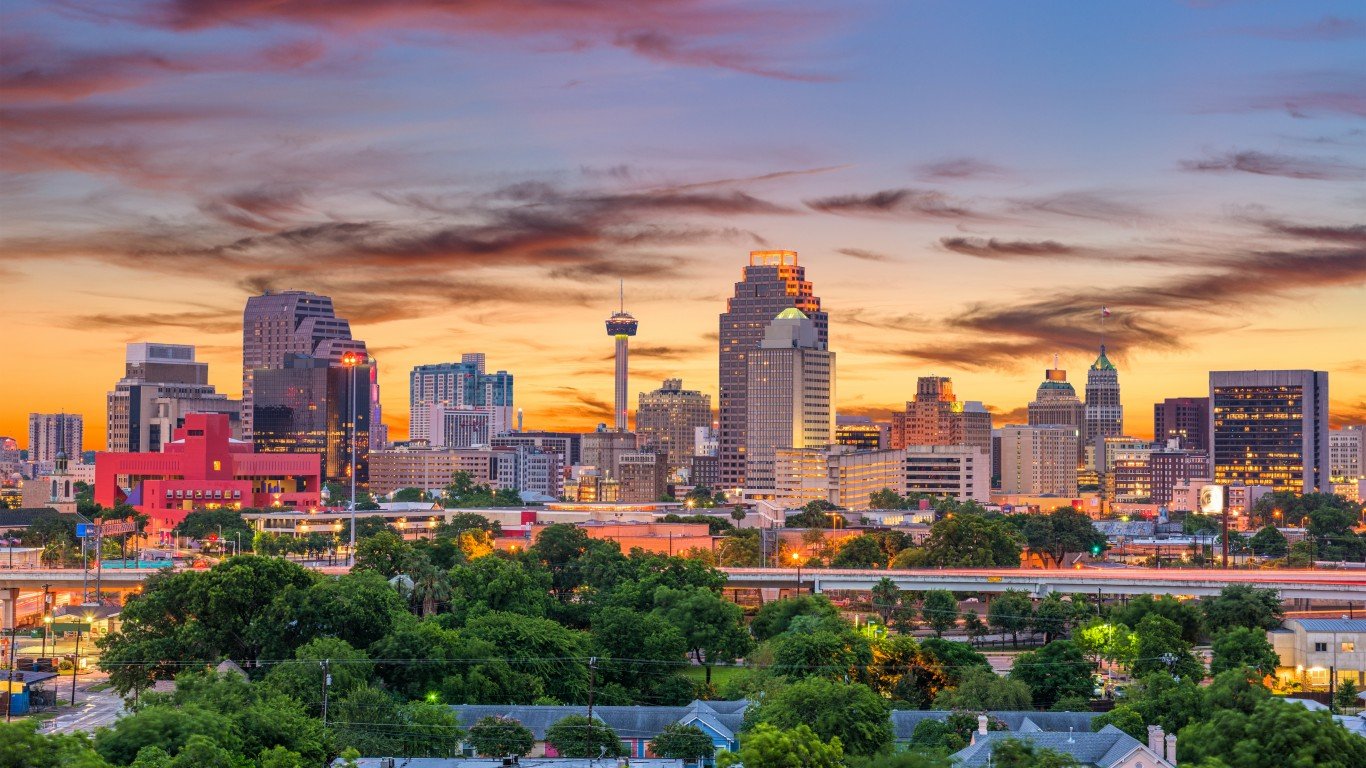
A couple in their late 50s or early 60s with a decent nest egg hears that Texas has no state income tax and starts pricing out Austin. Then they see the property tax bill and the home prices and begin to wonder whether the state is the retirement bargain everyone promised. Texas still works, but only if you pick the right city. For most retirees, that city is San Antonio.
Why San Antonio Beats the Other Texas Contenders
Austin’s composite cost-of-living index sits at roughly 106 in 2026, about 6% above the U.S. average, driven almost entirely by housing. The city of Austin’s median home price has corrected from its 2022 peak but still comes in near $426,000 to $530,000, depending on whether you measure the city proper or the broader metro. The Austin metro median was $435,000 as of July 2026. That is not California pricing, but it is not retirement-friendly pricing either, especially once you layer in Texas property taxes. Dallas and Houston carry their own big-metro property tax bills and traffic that undermine much of the financial case for moving. El Paso is genuinely affordable but remains thin on the specialist medical care a 75-year-old will eventually need.
San Antonio lands in the sweet spot: a major medical hub anchored by the South Texas Medical Center and a robust VA system, housing well below the national benchmark, and a cost of living that lets a middle-class portfolio breathe. San Antonio’s cost-of-living index runs roughly 90 to 95, between 8% and 12% below Austin and a few points below even the Texas statewide figure of approximately 93. That gap compounds meaningfully over a 30-year retirement.
The Real Cost Picture for a San Antonio Retirement
Assume a 65-year-old couple buying a modest single-family home in an established neighborhood inside Loop 1604. San Antonio’s median home price has stabilized after the 2025 correction. SABOR (San Antonio Board of Realtors) data through September 2026 puts the median sale price at approximately $302,000, with homes averaging roughly 90 days on market and about 6 months of supply on hand. Well-maintained homes inside the loop can price somewhat higher, but buyers have more negotiating room today than at any point since the pandemic run-up. Here is a realistic annual working budget in current dollars:
- Housing: $4,800 for a paid-off home covers insurance and HOA. Property taxes run roughly $6,500 on a $325,000 home before exemptions, closer to $4,200 after the over-65 homestead exemption and school tax ceiling kick in.
- Healthcare: Two Medicare Part B premiums at $202.90 per month each, plus Medigap and Part D, comes to roughly $9,600 annually for the couple. Add $2,500 for dental, vision, and out-of-pocket costs. The annual Part B deductible is $283 in 2026, a detail that catches many new Medicare enrollees off guard.
- Food: $9,600 on a USDA moderate-cost plan for two, below national averages because San Antonio grocery prices run soft.
- Utilities and transportation: $4,800 for electric (summer AC is the dominant cost), water, internet, and two older paid-off vehicles with insurance and fuel.
- Miscellaneous and reserves: $12,000 covering home maintenance, vehicle replacement, travel, gifts, and personal spending.
- Federal income tax on withdrawals: Roughly $3,500.
That lands around $55,000 to $58,000 a year for a comfortable San Antonio retirement. The Bureau of Labor Statistics reported that average annual household spending was $78,535 in 2024, so this budget comes in well below the national norm without feeling austere.
The Math That Gets You There
Social Security does most of the heavy lifting. The 2026 COLA of 2.8%, tied to the Consumer Price Index for Urban Wage Earners and Clerical Workers running from the third quarter of 2024 through the third quarter of 2025, pushed the average monthly retirement benefit for retired workers to approximately $2,089 as of September 2026, according to the Social Security Administration’s Monthly Statistical Snapshot. A dual-earner couple claiming at full retirement age with average lifetime earnings can pull in roughly $50,000 a year combined. After Social Security, the couple faces a gap of about $7,000 to $8,000 a year to draw from the portfolio, though households with below-average Social Security benefits will face a wider gap.
At a 4% withdrawal rate, closing a $14,000 annual gap requires $350,000 invested. Add a healthcare reserve of $75,000 and a home-repair sinking fund of $50,000, and the total lands around $475,000 in liquid assets plus the paid-off house. Delay one spouse’s Social Security to age 70 and the portfolio target drops closer to $325,000, because each year of delay beyond full retirement age adds about 8% to that check for life.
For early retirees bridging to Medicare, plan for roughly $18,000 to $24,000 per year for two ACA silver plans in Bexar County, and manage withdrawal income carefully to stay inside the subsidy cliffs. The Retiree’s Tax Trap Map walks through these interactions in detail.
The Texas Twist Most Analyses Miss
The over-65 property tax ceiling is the structural feature that determines whether Texas actually works for a retiree’s budget. Texas ranks seventh nationally on property tax burden, with an effective rate of about 1.40%, which sounds disqualifying at first glance. But something shifts at age 65. Once you or your spouse files the over-65 homestead exemption, your school district taxes (the largest single slice of a Texas property tax bill) are frozen at that year’s dollar amount for as long as you own the home. Home values can climb, but your school tax does not follow them up.
Texas levies no state income tax, so property taxes carry the bulk of public school funding, with the school district levy accounting for the dominant share of any Texas property tax bill. That structure is precisely what makes the freeze so valuable. In Austin, you lock the ceiling at a much higher starting bill. In San Antonio, you lock it lower, and the compounding advantage over 25 years adds up to real money. Miss the filing deadline, and you pay the escalating rate like everyone else.
San Antonio’s housing market in 2026 further strengthens the retirement case. The city led all Texas metros with a 39% surge in new listings from February to March 2026, giving buyers more selection and negotiating room than they had seen since before the pandemic run-up. By September 2026, SABOR data showed inventory at approximately 6 months of supply and homes averaging about 90 days on market, firmly in buyer-favorable territory. That inventory expansion matters when purchasing a long-term home: more supply means less pressure to overpay, and seller concessions have returned to the table across most neighborhoods.
The Bottom Line
To retire comfortably in San Antonio at 65 as a couple, you need a paid-off modest home, roughly $475,000 in invested assets, both Social Security checks running, a 4% withdrawal discipline, and the over-65 homestead exemption filed the moment you qualify. San Antonio works because it is the one Texas metro where the state’s no-income-tax advantage actually survives the property tax bill. The school tax freeze makes the next 25 years affordable rather than just the first one.
Editor’s note: This pass updates San Antonio’s median home price to approximately $302,000 per SABOR September 2026 data (replacing the earlier $265,000 Redfin August figure), revises the average Social Security retirement benefit to approximately $2,089 per month per the SSA Monthly Statistical Snapshot for September 2026 (up from $2,084), and corrects Texas’s national property tax ranking to seventh with an effective rate of about 1.40%, in line with current Tax Foundation and comparable data sources.
Contact [email protected] for any questions or corrections.
I am a long time investor and student of business, and believe finding good companies that can become great investments is the best game on earth. After 20 years of writing and researching the public markets it is clear that individuals have never had more tools and information to take control of their financial lives. From ETFs and $0 commissions to cryptos and prediction markets there has never been a greater democratization of access to investing.
I write to help people understand the investments available to them so they can make the best choice for their portfolio, whether they're starting out or looking for income in retirement.