Your Inheritance Is 100% Yours Until You Deposit It in the Wrong Account. The One-Word Rule (“Commingling”) That Decides Whether It Stays Yours
A single bank deposit can quietly strip inherited money of its legal protections, and most heirs trigger the trap within weeks of the estate settling, long before they realize anything went wrong.

This post may contain links from our sponsors and affiliates, and Flywheel Publishing may receive compensation for actions taken through them.
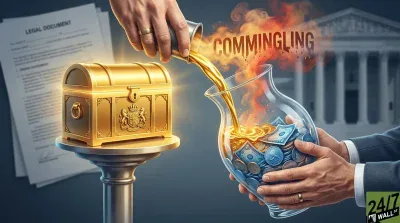
If you just inherited money from a parent, aunt, or grandparent, here is a rule the funeral-home paperwork will not mention: your inheritance is legally 100% yours, separate from your spouse, until the moment you deposit it into the wrong account. One wire transfer into a joint checking account can flip that money from separate property to marital property, and in a divorce, your spouse may walk away with half. The legal term for this trap is commingling, and it ranks as the single most expensive mistake heirs make in the first 90 days after a check clears.
What Commingling Actually Does to Your Money
Under family law in every U.S. state, property you inherit is treated as separate from marital assets, even if you are married when you receive it. That protection is automatic; you do not have to file anything to claim it. But the protection is also fragile. Once inherited funds get mixed with marital money in a way that cannot be untangled, courts can reclassify the balance as marital property subject to division. Deposit $200,000 from a parent’s estate into the joint account you use to pay the mortgage, let a few paychecks flow through, and by the time a divorce is filed, that money can become “ours.”
The word “can” is doing real work in that sentence. Commingling does not erase separate property status automatically. What it does is create a documentation crisis. If you cannot produce records tracing every inherited dollar back to its original source, courts default to treating the balance as marital. The burden lands entirely on the inheriting spouse, and meeting it requires years of meticulous paperwork most people never think to keep.
The Legal Anchor
The rule flows from state family law, not the IRS. In the nine community property states (Arizona, California, Idaho, Louisiana, Nevada, New Mexico, Texas, Washington, and Wisconsin), statutes like California Family Code §770 explicitly define inheritances as separate property, covering all assets acquired after marriage “by gift, bequest, devise, or descent.” California case law built a demanding tracing framework on top of that statute. The California Supreme Court’s 1966 decision in See v. See (64 Cal. 2d 778) established that a spouse who commingles separate and community funds bears the full burden of maintaining records sufficient to trace each dollar back to its source. The 1975 decision in In re Marriage of Mix (14 Cal.3d 604) reinforced that framework, holding that the tracing must be documented through bank statements and a dollar-by-dollar accounting, not merely asserted. Without adequate records, the community property presumption takes over.
Both decisions also recognized a rule known as the family expense presumption: when separate and community funds sit in the same account, courts presume that withdrawals for household and living expenses came from community funds first. That presumption sounds favorable to the spouse claiming separate property, but it cuts both ways. Each time the account balance falls below the original inherited amount, a portion of the separate property is deemed consumed, and no future deposit can restore it. Applied over years of ordinary household spending, this rule can quietly erase an inheritance even when the account balance looks healthy.
A related concept worth understanding is transmutation: the conversion of separate property into marital property, either intentionally or through how the asset is used. Under California Family Code §852, transmutation requires a written agreement, but in practice, retitling an inherited asset into joint names or using inherited funds to improve jointly held property can achieve a similar result. Commingling and transmutation can both happen without any deliberate intent.
In equitable distribution states, the same core principle applies through state divorce statutes and decades of case law: the inheriting spouse must prove separate-property status through documentary evidence, or risk the court treating the commingled funds as marital assets subject to division.
The Washington Exception Worth Knowing
Washington state deserves a separate mention because it operates on two statutory tracks that pull in opposite directions. Under RCW 26.16.010, inheritances are classified as separate property and are generally not subject to division. That protection, however, sits alongside the broad equitable authority Washington courts hold under RCW 26.09.080, which requires judges to distribute property in a manner that is “just and equitable” after weighing four statutory factors: the nature and extent of community property, the nature and extent of separate property, the duration of the marriage, and the economic circumstances of each spouse at the time of division.
In long marriages where significant economic disparity exists between spouses, judges have exercised that authority to award portions of an inheritance to the non-inheriting spouse, even when the funds were never commingled. This is the exception rather than the rule, but Washington residents face a risk that goes beyond the commingling problem and that no amount of careful account management can fully eliminate.
Who This Hits and Who It Doesn’t
Single? This does not apply to you. Spend, invest, and deposit the money wherever you want. Married? This issue reaches you whether you live in a community-property state or an equitable-distribution state, though the mechanics and thresholds differ by jurisdiction.
Prenuptial and postnuptial agreements can override the default rules, but only when they specifically address inherited assets. A prenup that is silent on inheritance leaves you under standard state law. On the other end of the spectrum, if the person leaving you money placed the inheritance into a properly drafted trust, the trust structure itself can shield the assets, making a separate account unnecessary.
How to Keep the Money Yours
- Open a brand-new account in your name only, at a bank where you and your spouse hold nothing jointly. Route the inheritance directly from the estate to that account.
- Never deposit a paycheck, tax refund, or any joint-source money into that account. Not once. Not $20.
- Never pay a joint bill, joint mortgage, or joint credit card out of that account. Paying marital expenses from separate funds can trigger a “gift to the marriage” presumption in some states.
- Keep the closing statement from the estate, the executor’s distribution letter, and every account statement going forward. This is your tracing paper trail, and it is the document set a court will demand.
- To invest the money, open a brokerage account in your name only and fund it exclusively from the separate bank account.
- If you must use inherited money to buy a house or pay down a joint debt, consult a family-law attorney first and document the transaction with a written agreement before any funds move.
The Trap Almost Everyone Falls Into
The subtler danger involves appreciation and income. Even when the principal stays clean, interest, dividends, and investment gains earned on inherited assets can be treated as marital property in many states, particularly when the growth resulted from active effort such as trading the account regularly. Passive appreciation on a stock you inherited and never touched usually stays separate. Gains on a rental property you inherited but personally managed throughout the marriage often do not. Courts have consistently drawn a line between growth that happened on its own and growth that required spousal time, energy, or marital funds.
What remains consistent across jurisdictions is the documentation requirement. If you cannot show which dollars in a mixed account originated from the inheritance, courts presume the whole balance is marital. The clock on protecting this money starts the day the estate distributes. By the time a marriage is in serious trouble, it is almost always too late to reconstruct the paper trail.
Editor’s note: This version adds RCW 26.16.010 as the Washington statute that classifies inheritances as separate property, supplements the Washington section with the four statutory factors courts must weigh under RCW 26.09.080, and introduces the family expense presumption from See v. See and In re Marriage of Mix, which can erode a separate property balance even when the account balance remains above the inherited amount.
Contact [email protected] for any questions or corrections.
Jake has been been working in financial media for almost 15 years. He focuses on all things personal finance for 24/7 Wall St. with high hopes to educate and entertain. Most recently, Jake spent 12 years working various roles at The Motley Fool. He started copy editing fool.com content, worked on premium and marketing campaigns, and helped launch The Ascent, a personal finance brand.
His work has been featured on platforms like MSN, Yahoo Finance, USA Today, and more. He's written about credit cards, social security, ETFs, savings accounts, and just about anything else you can imagine when thinking about money. Jake love to cook, play golf, and tell people he's never had a cavity. (It's true!)